Q3 Earnings Season: Strong Base, Higher Revision Trends, and Promising 2027 Outlook
We have a third of S&P 500 members on deck to report Q3 results this week, including three Mag 7 members – Alphabet GOOGL and Microsoft MSFT on Wednesday and Amazon AMZN on Thursday. By the end of this week, we will have seen Q3 results from more than 50% of S&P 500 members.
With results from about a quarter of S&P 500 members already out, we see a continuation of the broad-based strength we've seen in the last few reporting cycles. While the growth pace remains strong, it does not compare favorably with other recent periods, particularly when some of the outlier numbers are excluded. Most importantly, the revisions trend remains positive, with estimates for 2026 Q4 and full-year 2027 continuing to rise.
Looking at overall expectations for the quarter, combining the actual results from the 121 S&P 500 members that have reported already with estimates for the still-to-come companies, Q3 earnings are currently expected to increase by +26.2% from the same period last year on +12.2% higher revenues, the 8th straight quarter of double-digit earnings growth for the index.
The Tech sector continues to be a major growth contributor, but the momentum is broad-based, with 14 of the 16 Zacks sectors on track to enjoy positive earnings growth and 6 generating double-digit earnings growth in Q3.
The quarterly chart below details actual results alongside Q3 2026 growth expectations and forward projections.
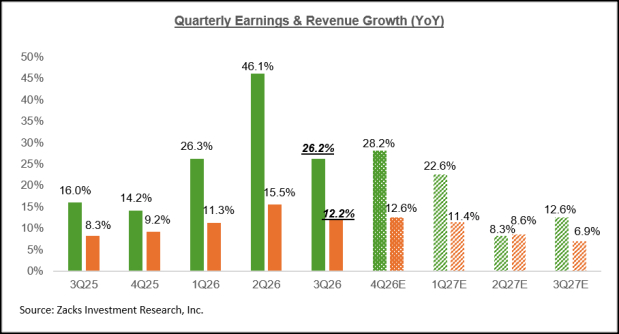
Image Source: Zacks Investment Research
As noted earlier, the revisions trend has been positive, sustaining the favorable trend in place for almost a year. Estimates for Q3 increased after the quarter got underway, and we are seeing a similar trend at play for 2026 Q4 estimates, as the chart below shows.
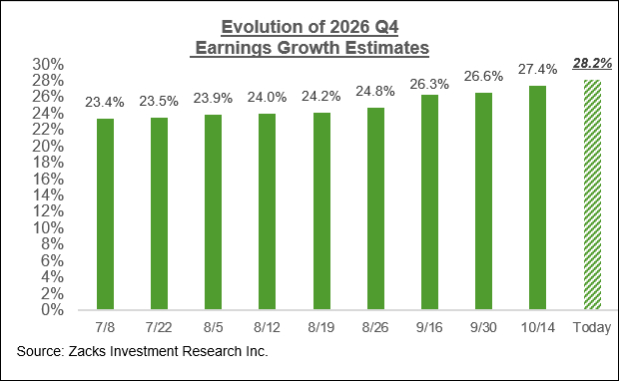
Image Source: Zacks Investment Research
This positive revision behavior is not new; it extends a tailwind that has been building for nearly a year. The positive revisions were at first concentrated in Technology and, more recently, Energy following Middle East supply disruptions. However, for 2026 Q4 and also what we saw for Q3, the favorable estimate revisions have broadened significantly, rising across 7 of the 16 Zacks sectors—including Industrials, Basic Materials, Finance, Aerospace and Conglomerates alongside Tech and Energy since the start of October.
On the negative side, Q4 estimates have come down since the start of October for 9 sectors, with the major declines at the Transportation, Autos, Consumer Staples, Consumer Discretionary, Construction, and Utilities sectors.
It is important to note that estimates for full-year 2027 have also been similarly trending higher, which we show a little later in this note.
Sector Focus: Broad-Based Strength
This week’s reporting line-up, comprising 172 S&P 500 members, is a representative sample of the index as a whole, ranging from the aforementioned Mag 7 members to Coca-Cola, Boeing, Caterpillar, Visa, Eli Lilly, and a host of Finance and other companies.
The 6 sectors expected to enjoy double-digit earnings growth in Q3 are Aerospace (up +186.7%), Energy (+128%), Tech (+45.3%), Basic Materials (+32.6%), Transportation (+11.1%), and Industrial Products (+14.4%).
Q3 earnings growth for the S&P 500 index drops to +21.6% from +26.2% once the Energy sector’s contribution is excluded from the index. Excluding the Tech sector, Q3 earnings growth for the rest of the index drops to +16.1%.
For the Mag 7 group, we already have actual results from Meta META and Tesla TSLA, and this week will bring results from Alphabet, Amazon, and Microsoft. The expectation is that Q3 earnings for the Mag 7 will increase by +22.3% on +23.1% revenues, as the chart below shows.
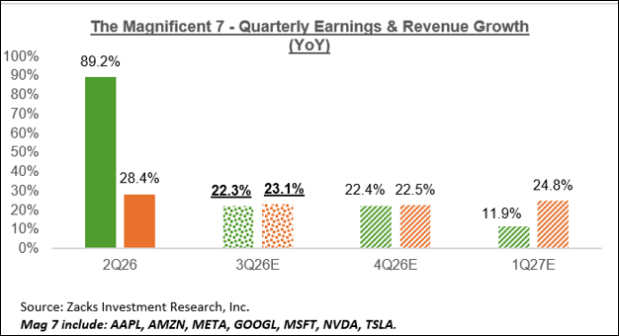
Image Source: Zacks Investment Research
Excluding the Mag 7 group’s contribution, Q3 earnings for the rest of the index would actually improve to +27.6% (from +26.2%).
The chart below shows quarterly earnings and revenue growth expectations for the Tech sector as a whole.
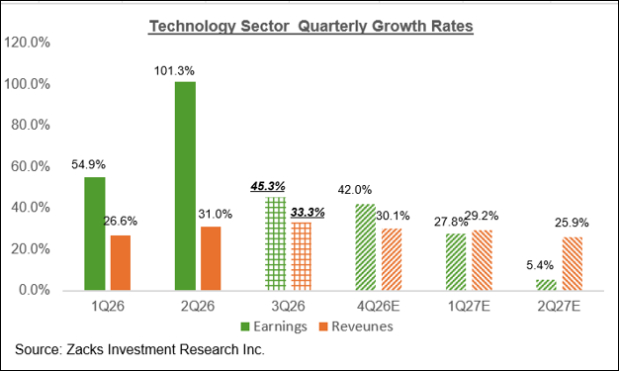
Image Source: Zacks Investment Research
The Q3 earnings and revenue growth rate drops to +23.1% from +45.3% once the substantial contributions from Nvidia NVDA, Micron MU, and Alphabet GOOGL are excluded, as the chart below shows.
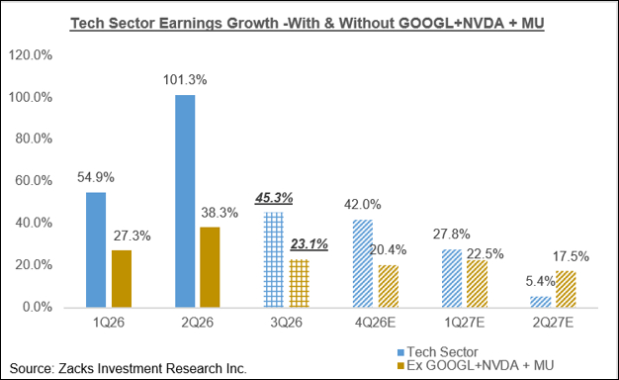
Image Source: Zacks Investment Research
Q3 Earnings Season Scorecard
Through Friday, October 23rd, we have seen Q3 results from 121 S&P 500 members, or 24.2% of the index’s total membership. Total earnings for these companies are up +31.5% from the same period last year on +12.2% higher revenues, with 80.7% beating EPS estimates and 69.7% beating revenues estimates.
The comparison charts below show the earnings and revenue growth rates for these companies compared to other recent periods.
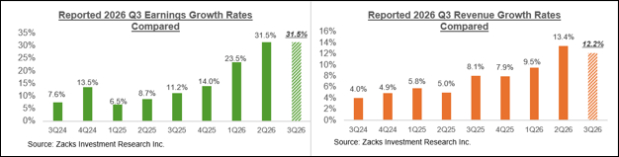
Image Source: Zacks Investment Research
The very strong earnings and revenue growth pace for this group of 45 S&P 500 members is mostly due to Micron, whose Q3 earnings increased +1075.7% from the year-earlier level. Excluding the Micron contribution, Q3 earnings for the remaining 120 index members that have reported would be up +14%.
The chart below shows the Q3 earnings growth pace for the companies that have reported, with and without Micron, across recent periods.
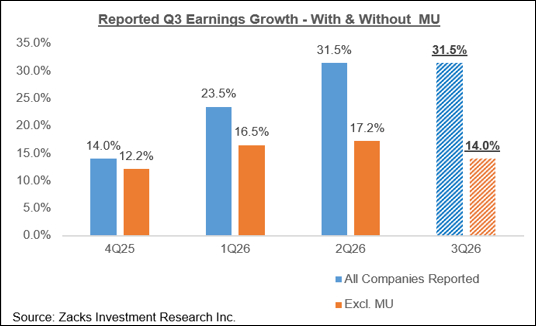
Image Source: Zacks Investment Research
The comparison charts below show the Q3 EPS and revenue beat percentages for these companies compared to other recent periods.
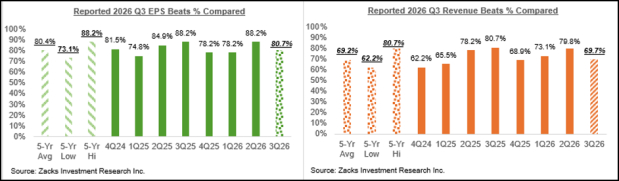
Image Source: Zacks Investment Research
For the Finance sector, we now have Q3 results from 55.3% of the sector’s market capitalization in the S&P 500 index. Total earnings for these Finance sector companies are up +10% from the same period last year on +8.7% higher revenues, with 80.6% beating EPS estimates and 52.8% beating revenue estimates.
The comparison charts below put the Q3 earnings and revenue growth rates in a historical context.
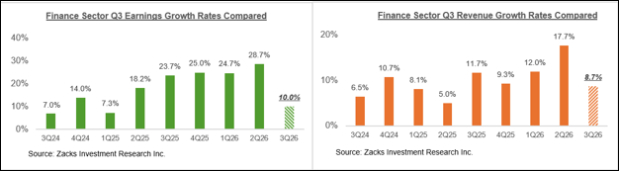
Image Source: Zacks Investment Research
The comparison charts below show the Q3 EPS and revenue beat percentages in a historical context.
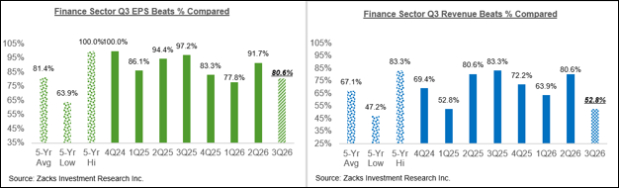
Image Source: Zacks Investment Research
As you can see above, not only are the growth rates tracking below other recent periods, but Finance sector companies also seem to be struggling to beat consensus EPS and revenue estimates.
The Earnings Big Picture
The chart below shows the aggregate growth picture for the S&P 500 index on a calendar year basis.
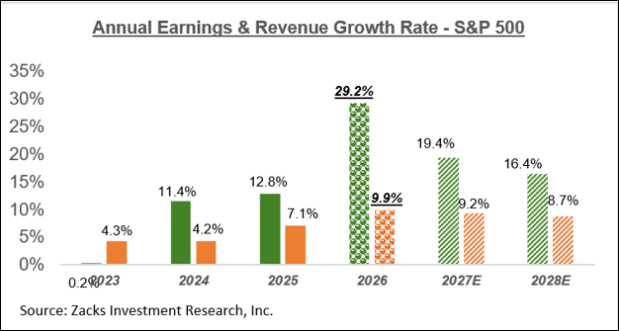
Image Source: Zacks Investment Research
As we noted earlier, estimates for full-year 2027 are experiencing the same positive and broad-based revisions trend that we noted earlier in the context of 2026 Q4. The chart below shows how aggregate 2027 earnings expectations have evolved since the start of July.
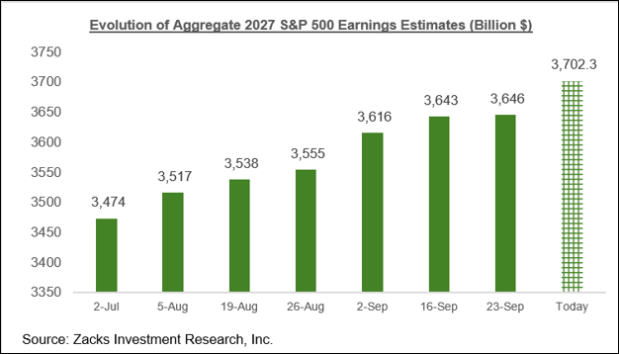
Image Source: Zacks Investment Research
For a detailed view of the evolving earnings picture, please check out our weekly Earnings Trends report here >>>> Q3 Earnings Season Ramps Up, Outlook for Q4 and Full-Year 2027 Improves
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Amazon.com, Inc. (AMZN): Free Stock Analysis Report
Microsoft Corporation (MSFT): Free Stock Analysis Report
Micron Technology, Inc. (MU): Free Stock Analysis Report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
Tesla, Inc. (TSLA): Free Stock Analysis Report
Alphabet Inc. (GOOGL): Free Stock Analysis Report
Meta Platforms, Inc. (META): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Mentioned In This Article
Latest News
| 3 min | |
| 49 min | |
| 54 min | |
| 1 hour | |
| 1 hour |
Nvidia Analyst Warns 45% of AI Data Center Capacity Planned for 2027 May Not Get Built
MSFT AMZN NVDA
Benzinga Prediction Markets
|
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 2 hours |
