Stock Futures Higher as Crude Prices Cool, Chips Surge
Cooling crude prices and rising chip are driving gains across Wall Street in premarket trading, with futures on the Dow Jones Industrial Average (DJI) and Nasdaq-100 Index (NDX) both up triple digits at last glance. Futures on the S&P 500 Index (SPX) are sporting modest gains as well, as buzz surrounding Anthropic's initial public offering (IPO) filing grows, which is expected to be made sometime today.
West Texas Intermediate (WTI) crude was last seen down 2.2% at $101, easing from last week's response to rising Middle East tensions. This week all eyes will be on the Federal Reserve's two-day October meeting, where the latest rate hike decision will be released Wednesday at 2 p.m. ET. CME's FedWatch tool is pricing in a 91.7% chance rates will remain unchanged.
Continue reading for more on today's market, including:
- 5 'frightening' options trading strategies for Halloween week.
- Everything you missed during last week's tumultuous tech tumble.
- Plus, Verizon's post-earnings pop; Meta stock looks to pivot higher; and another win for SPCX,
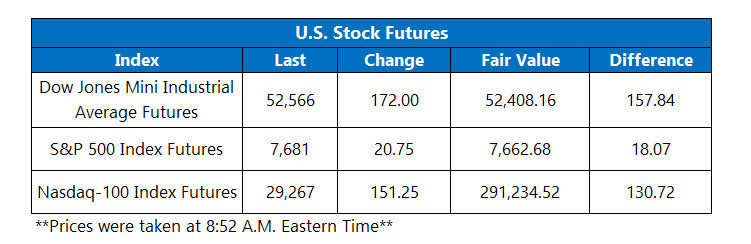
5 Things You Need to Know Today
- The Cboe Option Exchange saw roughly 2.2 million call contracts and 1.5 million put contracts traded on Friday. The single-session equity put/call ratio fell to 0.67, while the 21-day moving average remained at 0.59.
- Verizon Communications Inc (NYSE:VZ) is sliding 0.6% before the bell, despite posting a beat-and-raise and hiking its full-year 2026 outlook. The telecom giant also signed a $2 billion AI infrastructure partnership with Amazon Web Services (AWS). VZ is roughly 10% higher year-to-date, consolidating around the $44 level ahead of its report.
- Meta Platforms Inc (NASDAQ:META) is making buzz, down 1% in premarket trading, after the Magnificent 7 name announced a $35 billion stock offering to help fund it AI infrastructure growth. META has been struggling on the charts, Friday logging its seventh loss in eight sessions, trading back below its year-to-date breakeven mark after its Q3 report.
- Space Exploration Technologies Corp (NASDAQ:SPCX) is 0.9% higher ahead of the open, after Elon Musk's aerospace concern penned a deal with $40 billion with Apollo Global Management to lease data center supplies and AI chips. SPCX has been a hot topic of late, after last week posting a blowout third-quarter report.
- All eyes on this week's October Fed meeting.
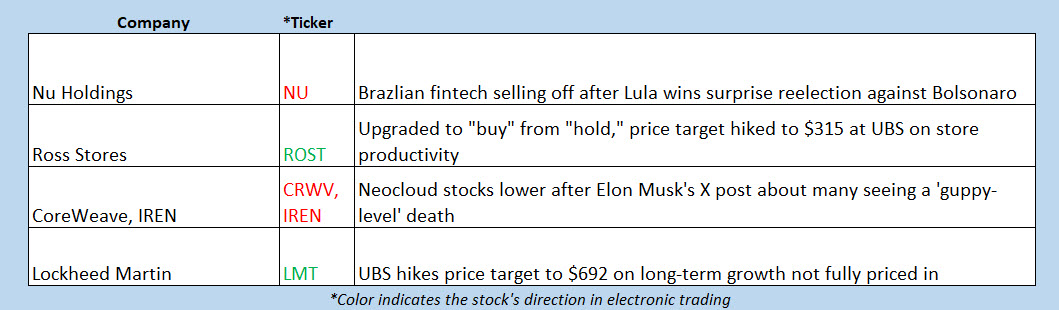
European Stocks Higher Ahead of U.K. Budget
Asian markets started the week mixed as the tech sector weighed. China's Shanghai Composite added 0.2%, despite worries about AI demand and curbs on Chinese exports. Financial stocks also struggled, with CITIC Securities plunging 20.2% amid concerns that a weak stock market was weighing on investor income. Japan’s Nikkei fell 0.8%, while Hong Kong’s Hang Seng gained 0.5% and South Korea’s Kospi lost 1.5%.
European markets moved higher Monday, with investors looking ahead to a busy week of economic developments and drawing support from a stronger euro. The U.K. government is preparing to unveil its first budget under Prime Minister Andy Burnham. Easing French borrowing costs also lifted sentiment, as the country’s 10-year bond yield fell 5 basis points. At last check, London’s FTSE 100 was up 0.4%, France’s CAC 40 had gained 0.8%, and Germany’s DAX was 1% higher.
Mentioned In This Article
Latest News
| 12 hours | |
| Oct-23 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-16 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-09 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 |
