Marriott's Q3 Test: Can US Momentum And New Card Deals Clear A Bar Above Guidance?
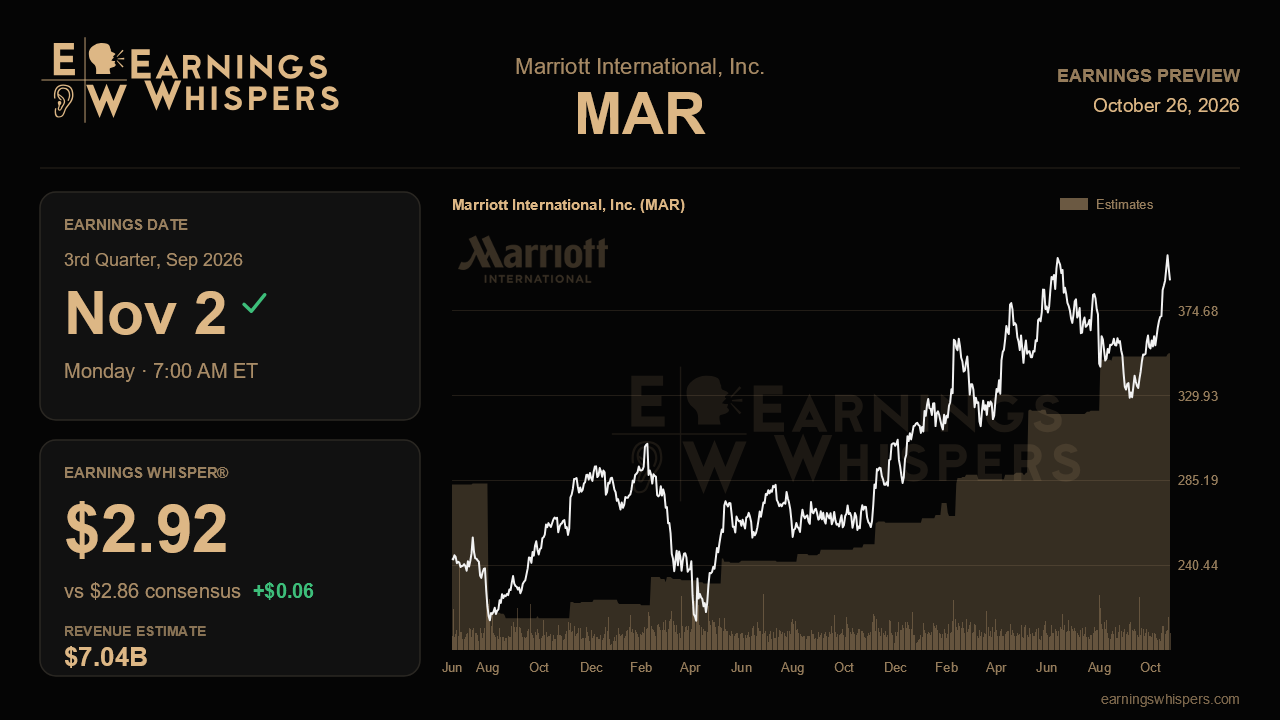
Marriott heads into its third-quarter report with something hotel investors have not seen in a while: a story of acceleration rather than resilience. Over four straight quarters, management has nudged its full-year global RevPAR outlook higher, from 1.5% to 2.5% at the start of the year to 3% to 3.5% after the second quarter. The question for the November 2 release, due before the opening bell, is whether that momentum carried through the summer strongly enough to justify a Street estimate that already sits above the company's own quarterly guidance.
Analysts expect earnings of $2.86 a share on revenue of roughly $7.04 billion, which would mean growth of about 16% in profit and 8.5% in sales from a year ago. That is a healthy pace for an asset-light franchisor whose revenue is largely fees tied to room revenue. Management guided to $2.74 to $2.82 for the quarter, so consensus is perched just above the top of the range, and the whisper number of $2.92 lifts the bar a bit further. The gap is not dramatic, but it tells you the market assumes Marriott's habit of conservative guidance will hold. For the full year, by contrast, the $11.66 consensus sits near the low end of the raised $11.64 to $11.81 outlook, leaving room for another upward revision if the third quarter lands well.
The operating test starts in the United States and Canada, where second-quarter RevPAR rose 5%, the best result in 13 quarters, with gains spread from luxury to select service. That breadth was the most encouraging part of the last call, because select service had been slipping only a few quarters earlier. Management guided third-quarter global RevPAR up 3.5% to 4%; a result at or above that range with US select service still positive would confirm demand is broadening, while a fade back toward low single digits would suggest the spring was a peak rather than a new trend. Fee lines matter as much as room rates. Gross fees were lifted to roughly 11% growth, incentive management fees moved from roughly flat to up 3% to 5%, and the newly signed Chase and American Express co-brand card deals were expected to add about $30 million in the second half. This quarter offers the first real look at whether that card uplift is showing up as promised, a down payment on the $100 million to $125 million management has framed for 2028.
The soft spots deserve equal attention. The Middle East conflict dragged EMEA RevPAR down 5% last quarter, with the region itself off 43%, and construction delays pushed net rooms growth toward the low end of 4.5% to 5%. Owned and leased profit guidance has been cut twice, investment spending was raised to as much as $1.35 billion on higher key money, and an owner letter hinted at friction over hotel economics. Any further trimming in these areas, or caution about a fourth quarter facing tough Middle East comparisons and a midterm election, could blunt an otherwise clean beat. Updates on the record 629,000-room pipeline and early 2027 commentary will also shape how much growth investors are willing to pay for.
The market has already rewarded the improving narrative. Shares are up 8.7% since the last report versus 1.4% for the S&P 500, trade about 10% above their 200-day moving average, and sit roughly 4% below the post-earnings high of $407. Sentiment has edged up modestly from the prior quarter, consistent with expectations that are optimistic but not euphoric. Ultimately, this report turns on whether US strength and the new card economics are robust enough to offset Middle East weakness and still support another raise. If they are, the acceleration thesis holds; if guidance merely stands pat, a stock priced for momentum may find little to celebrate.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 10 hours | |
| Oct-25 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-20 | |
| Oct-19 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 |
