Apple Heads Into Ternus Era With Memory Costs And Supply Limits Testing A Rally
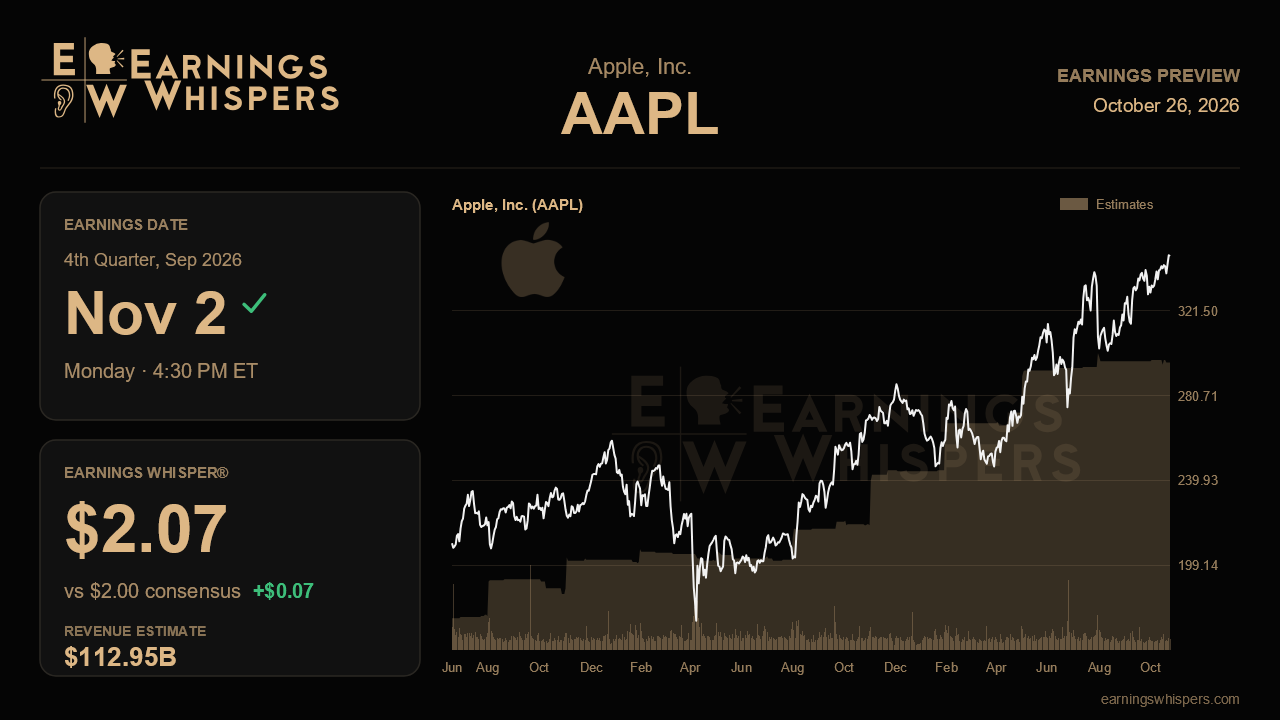
Apple has a problem most companies would envy: customers want more iPhones and Macs than it can build. The trouble is that this happy problem now comes with real costs. When Apple reports fiscal fourth-quarter results after the close on November 2, the question is whether surging demand can outrun broadening supply constraints and a historic spike in memory prices. Investors have bid the shares up 14.1% since the last report while the S&P 500 gained just 2.1%, so the market has already chosen an answer.
Wall Street expects earnings of $2.00 a share on revenue of $112.95 billion, which would mean growth of roughly 8% on the bottom line and 10% on the top line from a year ago. Those figures sit squarely inside management's guidance for $1.91 to $2.04 a share and $111.69 billion to $113.74 billion in revenue. Revenue consensus lands just above the midpoint, while the EPS estimate leans toward the upper half. Analysts have also trimmed their numbers since guidance came out, having previously sat above the range on revenue. The Earnings Whisper of $2.07, however, sits above both consensus and the top of Apple's own outlook, a sign that the real bar is higher than the published estimates suggest. Notice too that earnings are expected to grow more slowly than sales. That gap is the margin story in miniature.
The prior call marked a clear shift in tone. Apple's guidance for growth of 9% to 11% was a meaningful step down from the 14% to 17% and 13% to 16% ranges of the two previous quarters. Supply limits that had mostly affected the Mac were expected to worsen sharply and spread to iPhone and iPad. Meanwhile memory costs went from a negligible factor early in the fiscal year to what management likened to a once-in-a-century flood, pushing the gross margin outlook to 47% to 48%. That range includes roughly a point of benefit from tariff refunds, implying an underlying margin closer to 46.5%, well below the prior quarter's adjusted figure. Apple responded with reluctant price increases across iPhone, iPad and Mac, so this report offers an early read on whether customers absorb those increases without flinching.
Validation would look like iPhone growth holding near the 22% pace of the past three quarters despite tighter supply, a gross margin landing at or above the top of the guided range, and services stabilizing rather than sliding further below 10% amid currency drag, App Store softness in mobile gaming and a tough comparison against last year's F1 film. A challenge would be iPhone growth fading sharply, margins drifting toward the low end, or commentary suggesting price increases are dampening demand. Equally important is the December-quarter outlook. Management warned that memory pricing keeps rising and the cushion from cheaper inventory on hand is shrinking, so the margin guide for the holiday quarter may matter more than the September print itself.
There are offsetting positives worth tracking: early momentum from the Siri and Apple Intelligence beta and any sign of iCloud+ upsell, regulatory clearance to ship AI features in China, a new US upgrade leasing program, and enterprise and education wins that saw MacBook Neo displacing Windows and Chromebook machines in several school districts. This will also be John Ternus's first report as chief executive, adding a layer of scrutiny to every forward-looking comment.
Sentiment has warmed from modestly bearish heading into the last report to roughly neutral, and the stock at $347.73 sits about 18% above its 200-day moving average and within about 1% of its post-earnings high of $351.73, effectively testing a breakout. That leaves little room for a merely in-line quarter. The narrative holds if Apple shows that demand strength and pricing power can protect margins as memory costs climb. If the holiday margin guide slips further, the rally will have gotten ahead of the numbers.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 35 min | |
| 47 min | |
| 2 hours | |
| 2 hours | |
| 4 hours | |
| 5 hours | |
| 6 hours | |
| 9 hours | |
| Oct-25 | |
| Oct-25 | |
| Oct-24 | |
| Oct-24 | |
| Oct-24 | |
| Oct-23 | |
| Oct-23 |
