Diamondback's Green-Light Pivot Faces Its First Real Cost And Cash Test
Diamondback Energy heads into its third-quarter report with a story that has changed character in under a year. Management spent late 2025 and early 2026 describing a yellow-light posture and holding output flat, then flipped to growth mode in the spring, added rigs and a completion crew, and used the August call to sound more confident than at any point in the cycle. The November 2 release, due after the close, is the first quarter where that growth posture has to show up cleanly in volumes, costs and cash at the same time.
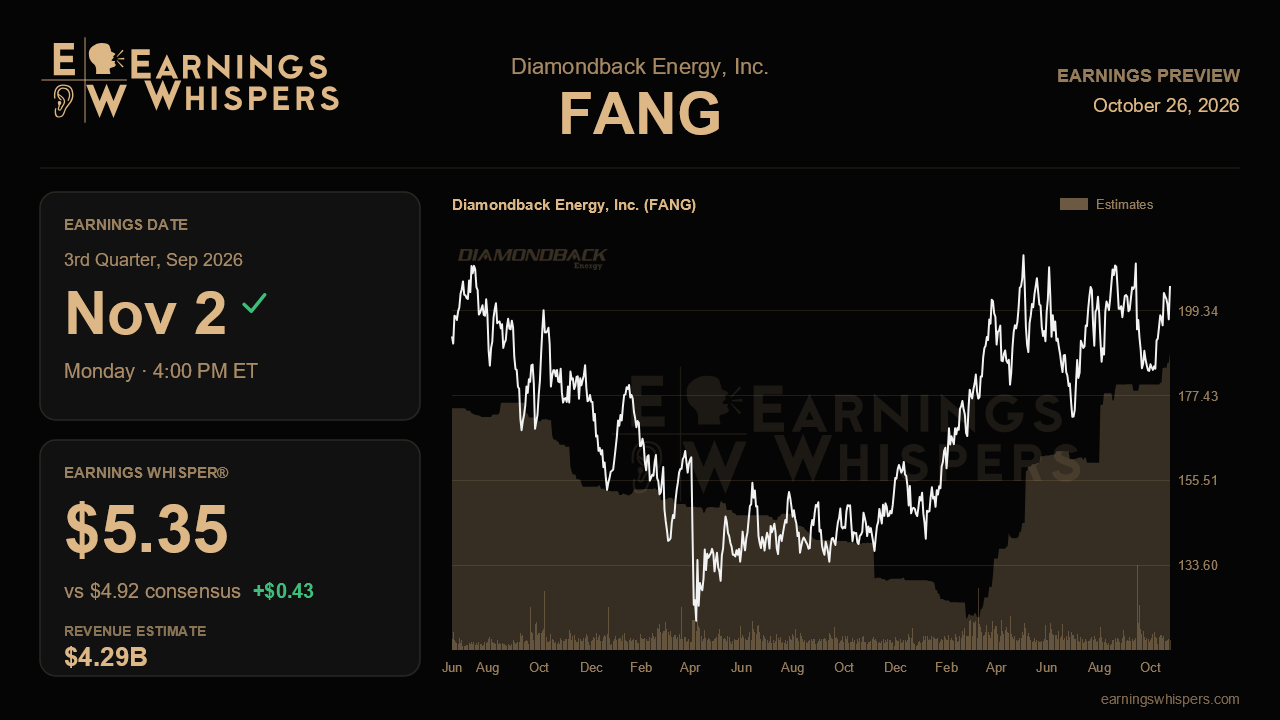
The Street is looking for earnings of $4.92 per share on revenue of about $4.29 billion. That would be roughly 60% EPS growth from the $3.08 earned a year ago on revenue growth of about 9%, a gap that speaks to operating leverage and lower debt rather than a dramatic jump in the top line. It is also a sizable step down from the $6.48 per share and $5.56 billion posted last quarter, so the consensus already bakes in a softer sequential print. The earnings whisper of $5.35 sits about 9% above consensus, a meaningful cushion that suggests the more engaged crowd expects Diamondback to clear the published bar with room to spare. Absent fresh formal guidance, management's own framing from August is the yardstick.
That framing gives investors a specific checklist. Oil production should hold near the elevated 520,000 barrels per day plus level, about 4% above the original 2026 plan, and any slippage would undercut the claim that 2027 can deliver low-single-digit organic growth. Capital spending is the second test. Management signaled a run rate of roughly $1 billion to $1.1 billion per quarter and warned that casing and tubular costs would add a little over 1% to well costs in the back half. Spending that lands inside that range, with drilling efficiencies such as near-continuous pumping offsetting steel inflation, would validate the plan; a creep above it would raise doubts about how much growth costs. Lease operating expense around $6 per barrel is the other line to watch, since management already conceded it may not fall.
The balance sheet and gas marketing should tell the rest of the story. After cutting net debt by $1.6 billion in the second quarter, management talked about building a fortress and retaining cash for its 2029 to 2032 maturities rather than maximizing buybacks. Continued deleveraging would reinforce that message, though shareholders hoping for heavier near-term returns may be disappointed. On gas, Waha pricing turned positive in July as new pipelines advanced, and the company aims to cut its Waha exposure to about 40% by year end from roughly 70%. Better gas realizations would be early proof that the fix is structural rather than temporary.
The longer-dated catalysts need progress reports rather than numbers. The Bryant Ranch power and data center project was awaiting an ERCOT Batch 0 determination in late August that gates its grid connection as soon as 2028, so the outcome and the next steps will matter for how much value investors assign to the concept. Updates on the first full Barnett pad, drilling costs approaching $400 per foot, and the surfactant recovery program now built into new pads would show whether these are maturing on schedule.
Sentiment has warmed noticeably, moving from mildly bearish before the last report to solidly bullish now, and the stock has gained about 9% since August while the S&P 500 was flat. At $205.75 it trades well above its 200-day average of roughly $188, though still about 5% below its post-earnings high of $216.90. Expectations are clearly higher than three months ago. The central question is whether Diamondback can keep volumes elevated while holding spending and unit costs near plan, because that combination is what turns the confident green-light narrative into durable free cash flow.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Oct-23 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-08 | |
| Sep-30 | |
| Sep-23 | |
| Sep-20 | |
| Sep-18 | |
| Sep-16 | |
| Sep-16 | |
| Sep-11 |
