Palantir Must Outrun Its Own Q3 Guide As Expense Ramp Tests Record Momentum
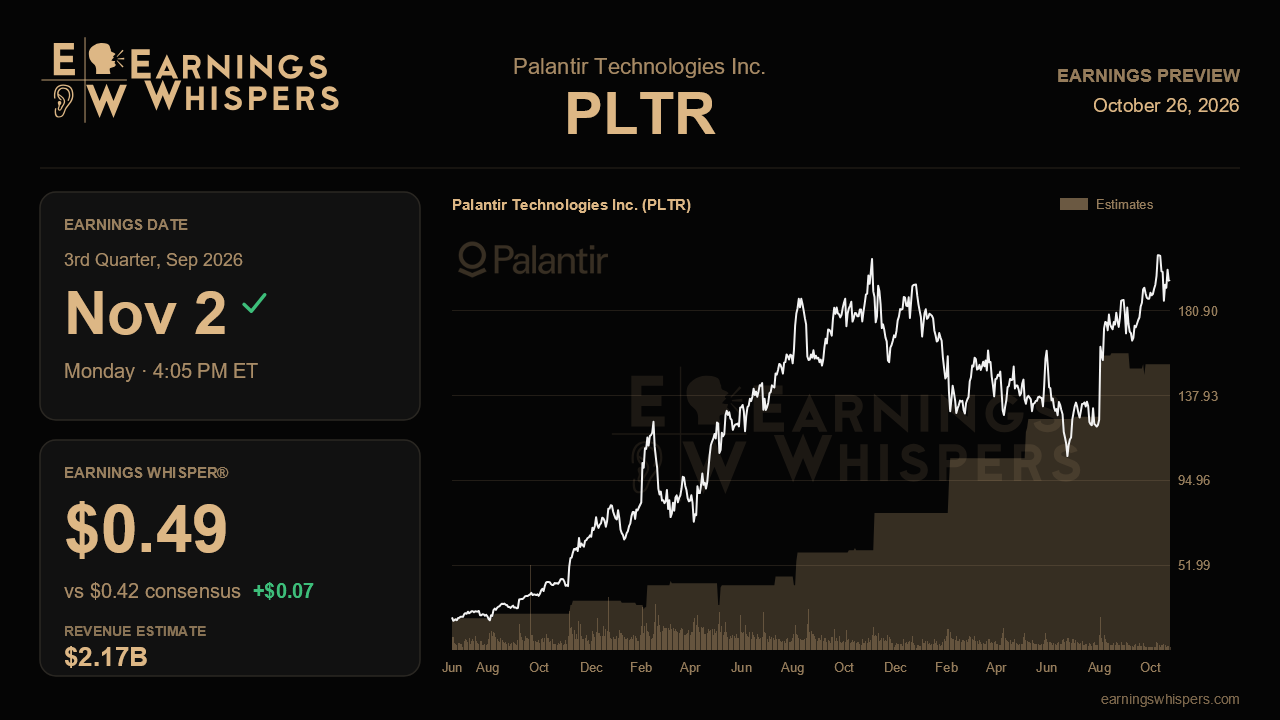
Palantir enters its third-quarter report with an awkward luxury: Wall Street now expects more than the company promised. Management guided to revenue of $2.16 billion to $2.164 billion, yet consensus sits at $2.17 billion, just above the top of that range. When the guidance first landed, the Street was looking for only $2.00 billion. That gap has since flipped. Analysts have effectively priced in Palantir's habit of clearing its own targets, which means an in-line print would read as a disappointment.
The headline numbers are still extraordinary. Consensus calls for earnings of $0.42 a share on an adjusted basis, more than double the $0.18 earned a year ago, with revenue expected to climb about 84%. The whisper number of $0.49 is meaningfully above consensus, suggesting the more aggressive crowd expects another sizable beat. There is a wrinkle, though. Second-quarter growth hit a record 93%, and an 84% pace would mark the first visible deceleration after four straight quarters of acceleration from 63%. A clean beat that keeps growth near or above 90% would protect the story; a print near guidance would invite questions about whether the curve has peaked.
The previous call was Palantir's most emphatic yet. Management delivered its largest-ever full-year raise, lifting 2026 revenue to roughly $8.15 billion, or 82% growth, and pushed the U.S. commercial target above $3.42 billion. U.S. commercial revenue grew 149%, net dollar retention rose to 157%, and U.S. commercial bookings hit a record $2.13 billion, up 153%. Those bookings are the key to this quarter. A contract haul that large should begin converting into recognized revenue, so U.S. commercial growth holding near the high-140% range would validate the pipeline. A sharp drop-off in new bookings after such an outsized quarter would not be shocking, but it would make the full-year raise look more front-loaded than durable. Alex Karp's stated aim of driving total growth at or above the U.S. commercial rate for the next 18 months sets an unusually explicit benchmark.
Profitability is where the whisper gets tested. Management warned of a significant third-quarter expense ramp tied to seasonal hiring and product and marketing spending, and adjusted gross margin slipped to 86% from 88% as Palantir absorbed cloud hosting costs for a government customer. If margins hold steady and operating leverage still shows through, a number near $0.49 is plausible. If hosting costs widen and hiring weighs more heavily, earnings could land closer to consensus even on strong revenue. The raised full-year targets for adjusted operating income of about $4.89 billion and free cash flow of $4.5 billion to $4.7 billion give a yardstick for whether spending is running on plan.
The newer catalysts need early proof. Management highlighted sovereign AI, in which customers own and post-train model weights inside their own security perimeter, along with an NVIDIA partnership and boot camps that reactivated dormant Foundry-only customers. Evidence that those reactivations are expanding into paying deployments would strengthen the case that growth has a fresh leg. Maven's emergence as a government program-of-record platform should show up in continued strength in U.S. government revenue, which grew 90%. International commercial, stuck at 26% growth with Europe lagging, remains the weak link; any improvement would be a bonus, while further stagnation keeps the business heavily dependent on the U.S.
The market has already voted. Shares have surged about 36% since the last report while the S&P 500 was flat, and sentiment has improved to 22.7% bullish from 14.9%. At roughly $197, the stock trades well above its 200-day average near $153 but about 8% below its post-earnings high of $212.94, so it is not pressing a breakout. The real question is whether Palantir can beat a consensus that already sits above its guidance and raise the full year again while absorbing heavier spending. Anything less than another raise may struggle to justify the rally.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 9 hours | |
| Oct-25 | |
| Oct-24 | |
| Oct-24 | |
| Oct-23 | |
| Oct-23 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 |
