Roku Nears A Breakout As Wall Street Tests Whether Its Profit Surge Can Last
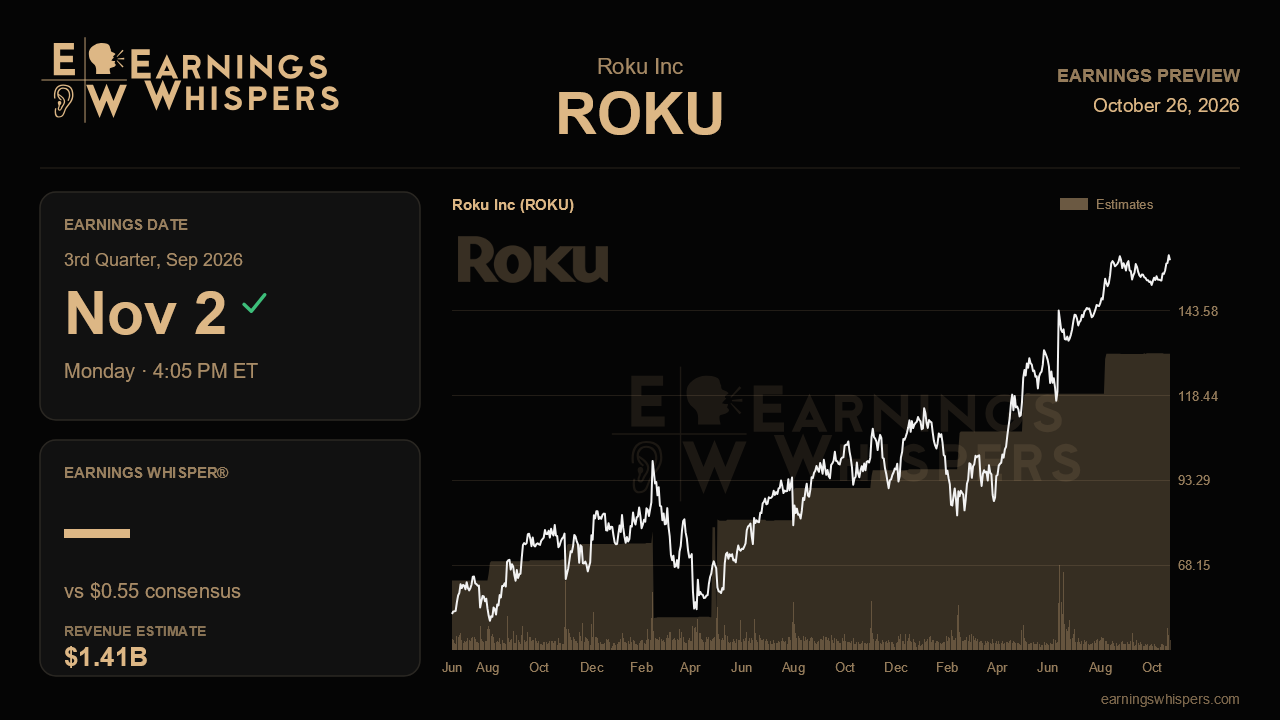
Roku heads into its third-quarter report with an unusual puzzle. Last quarter the company earned $1.18 a share, yet Wall Street expects only $0.55 this time, less than half that figure. Even so, the consensus implies earnings more than triple the $0.16 Roku posted a year ago. The question is not whether Roku has become a profitable company. The year-over-year math says it has. The question is which of the last two quarters better represents its true earning power, and whether the stock, trading just below its post-earnings high, has already priced in the more generous answer.
Analysts are looking for revenue of about $1.41 billion, up 16.5% from $1.21 billion a year earlier and roughly 4% above the $1.35 billion reported last quarter. That is solid double-digit growth for a platform of Roku's size, though not spectacular, and it puts the burden of the story on margins rather than the top line. A 244% jump in expected earnings on 16.5% revenue growth is operating leverage in its purest form: each additional dollar of revenue is expected to fall to the bottom line at a much higher rate than it did a year ago. With no updated company outlook available, the Street's figures are the bar Roku must clear.
The sharp sequential step down in expected EPS is the most important detail in the setup. Analysts plainly are not extrapolating last quarter's result. That could reflect a view that the prior quarter benefited from favorable items that won't repeat, or an expectation of heavier spending in the back half. Either way, the gap creates an opening. If Roku lands well above $0.55, it would suggest last quarter was closer to a new baseline than an outlier, and the profitability story would gain real credibility. A result near consensus would confirm the more cautious reading, while a miss against a deliberately lowered bar would raise questions about cost discipline just as revenue growth is supposed to be compounding.
Under the surface, the quality of revenue matters as much as the total. Roku's long-term thesis rests on advertising, particularly monetized video ad impressions from The Roku Channel and the continued migration of traditional TV ad budgets into streaming, supported by its OneView ad platform. Growth led by high-margin platform and advertising revenue would support the margin expansion the consensus assumes. Growth tilted toward lower-margin hardware would make the earnings forecast harder to hit even if revenue matches expectations. Engagement and active account trends will also show whether the audience base feeding that ad business is still widening.
The market has been receptive. Roku shares have gained 4.4% since the last report while the S&P 500 slipped 1.4%, a 5.8-point edge. At $158.58, the stock sits roughly 25% above its 200-day moving average of $126.29 and within about 1% of its post-earnings high of $160.22, effectively testing a breakout. Notably, the entire post-earnings range, from $150.03 to $160.22, sits above the prior quarter's high of $150.61, a sign the stock has reset to a higher plateau and held it. Sentiment is modestly bullish at 8.5%, edging up from 7.8% a quarter ago, a change too small to signal euphoria but consistent with steady confidence.
That combination raises the stakes. A stock pressing against resistance with a tighter, higher trading range typically needs fresh evidence to push through. For Roku, that evidence comes down to one issue: whether its margin gains are durable. If the company shows that advertising-driven revenue growth is converting into earnings at a rate closer to last quarter's than to the Street's cautious estimate, the profitability narrative stays intact and likely strengthens. If not, the recent rally may prove to have run ahead of the fundamentals.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 10 hours | |
| 10 hours | |
| Oct-22 | |
| Oct-19 | |
| Oct-19 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Sep-30 | |
| Sep-30 | |
| Sep-24 | |
| Sep-24 | |
| Sep-24 | |
| Sep-11 |
