Verizon Beats On Earnings And Raises Guidance Again, But A Revenue Miss And Souring Sentiment Complicate The Story
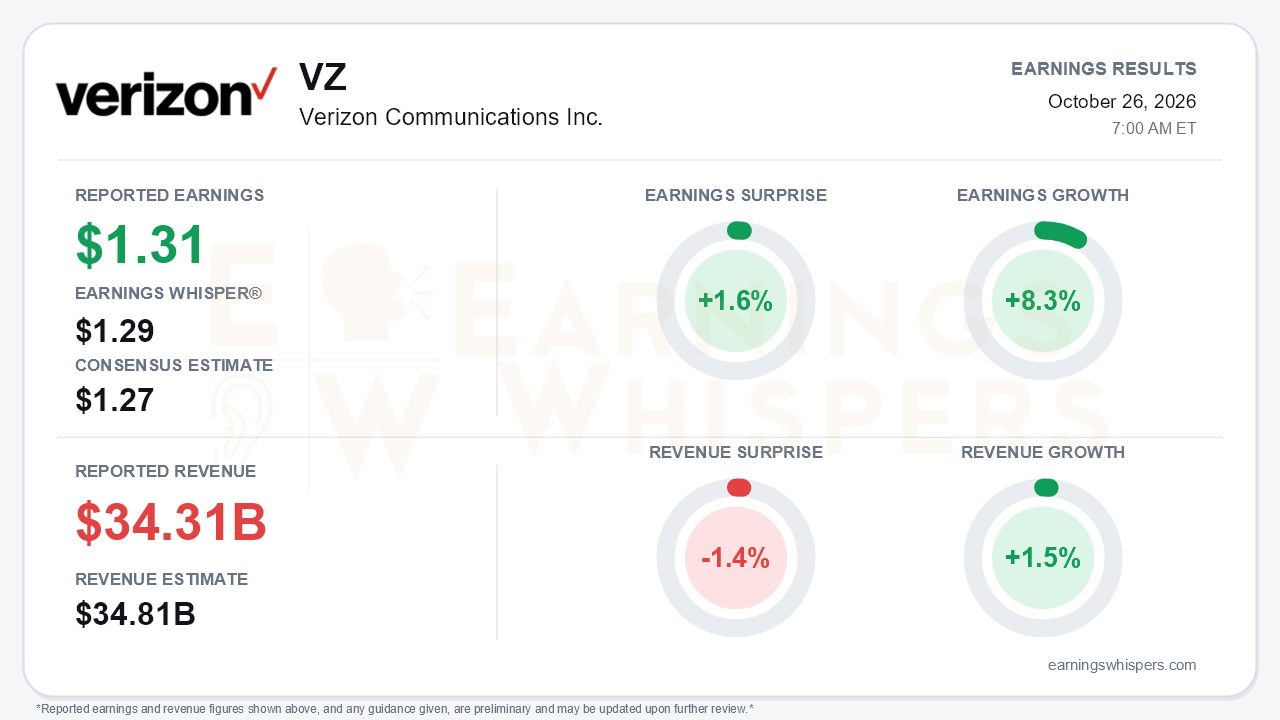
Verizon delivered the kind of quarter its transformation narrative needed, even if the top line did not cooperate. Adjusted EPS of $1.31 beat the $1.27 consensus by 1.6% and edged past the $1.29 Earnings Whisper number, with earnings up 8.3% year over year. Revenue of $34.31 billion, however, missed the $34.81 billion consensus by 1.4% and grew only 1.5%. That is the central tension. The miss came almost entirely from a 9% drop in equipment revenue, which management attributes to longer device holding periods and a deliberate pullback in subsidies. The revenue that drives profits, mobility and broadband service revenue, rose 2.9% to $23.5 billion. Management also raised full-year guidance for a third consecutive quarter.
The beat is cleaner than most. GAAP EPS was $1.25, up 6.8%, and the adjustments to reach $1.31 were limited to $0.07 of acquisition amortization and integration costs. That contrasts with the heavy severance and disposal charges in the second quarter. Adjusted EBITDA rose 8.0% to a record $13.8 billion, and margin expanded 240 basis points to 40.2%. Both segments contributed: Consumer EBITDA margin climbed to 45.3% from 43.0%, and Business improved to 27.6% from 25.1%. Free cash flow rose 12.1% to $7.8 billion. Lower third-quarter capex, $3.7 billion versus $4.3 billion a year ago, helped that figure, and the full-year capex guide of $16.0 billion to $16.5 billion implies spending rises again in the fourth quarter. Interest expense also deserves watching. It was roughly $1.95 billion versus $1.66 billion a year earlier, a drag that strong operating leverage is currently absorbing.
The operating data are what changed the conversation. Postpaid phone net adds reached 406,000, the best third quarter in five years, up from just 55,000 in the first quarter. Net accounts rose by 137,000, the best result in more than a decade. Customer acquisition also became cheaper. Promotional acquisition costs fell 41% and retention costs fell 30%, while postpaid phone churn improved 4 basis points to 0.94%. Service revenue growth has stepped up from 1.6% to 2.8% to 2.9% across the year, and management guided to roughly 4% in the fourth quarter. Full-year postpaid phone net add guidance jumped to 1.1-1.2 million from the upper half of 750,000-1 million. Adjusted EPS growth guidance moved to 7-7.5%, compared with 4-5% at the start of the year. Free cash flow growth is now expected to approach 12%. Management's tone was markedly more confident, including open talk of value-backed price increases.
The strategic catalyst list lengthened. A $2 billion-plus dark fiber deal with AWS follows last quarter's Google agreement and brings AI Connect signed contracts to roughly $4 billion. Verizon also unveiled a millimeter-wave 1-gig fixed wireless product intended to add 10-15 million premises beyond its 40-50 million fiber passings target, along with a multi-year Corning fiber supply agreement. Management promised 2027 guidance, including AI Connect's revenue contribution, on the next call.
Bears still have legitimate ammunition:
- **Wireless service revenue is not yet growing.** At roughly $20.9 billion, it is not expected to grow year over year until the fourth quarter.
- **Broadband momentum is fading.** Net adds slid to 314,000 from 341,000 in the first quarter and 372,000 in the fourth quarter of 2025, as Verizon restricts fixed wireless sales where speeds fall short.
- **Pricing could undo the churn gains.** The price increases management is signaling could pressure the improvement in customer retention.
- **Competition is a longer-term overhang.** SpaceX's terrestrial network ambitions add a competitive threat, though management frames it as four to six-plus years away.
Investors were not leaning bullish into the print. Earnings Whispers sentiment weakened from slightly negative (-0.07) to more clearly negative (-0.21) ahead of the report. The stock has been volatile but has gone nowhere. At $44.66, shares were up just 1.3% from the open after the July report. In that span, they rallied to $51.67 in mid-September, fell to $40.81 on October 9, and rebounded about 9% off that low. They remain 4.3% below the 200-day moving average of $46.69, and the Earnings Whispers price and AVWAP trend readings are still negative even as momentum has turned positive.
The bottom line is that Verizon's quarter was stronger beneath the surface than the revenue miss suggests. Service revenue is accelerating, margins hit a record, cash flow outpaced plan, and guidance rose across the board for the third straight time. The market setup is more complicated. Skeptical sentiment and a stock still below its long-term average leave room for a re-rating if fourth-quarter wireless service revenue growth and roughly 4% service growth materialize. Fading broadband adds and the untested durability of churn under price increases are the variables to monitor.
Read our earnings preview for Verizon Communications Inc.: https://www.earningswhispers.com/article/VZ/20638
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 47 min | |
| 58 min | |
| 1 hour | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 7 hours | |
| 8 hours | |
| 8 hours | |
| 8 hours | |
| 8 hours | |
| 8 hours |
Verizon Earnings Top Estimates, Revenue Light. Wireless Subscriber Adds Beat.
VZ
Investor's Business Daily
|
| 9 hours |
