Vertex Heads Into Q3 With Raised Guidance As Casgevi And Gernavix Ramps Face Proof Test
Vertex Pharmaceuticals spent its last report telling investors that the company is no longer just a cystic fibrosis franchise with a pipeline attached. Management raised full-year revenue guidance, described five commercial pillars instead of four, and pointed to quickly accelerating launches for Casgevi and Gernavix. The third-quarter report, due after the close on November 2, is the first real check on whether that broader story is translating into dollars at the pace the company implied, or whether the core CF business is still doing most of the heavy lifting.
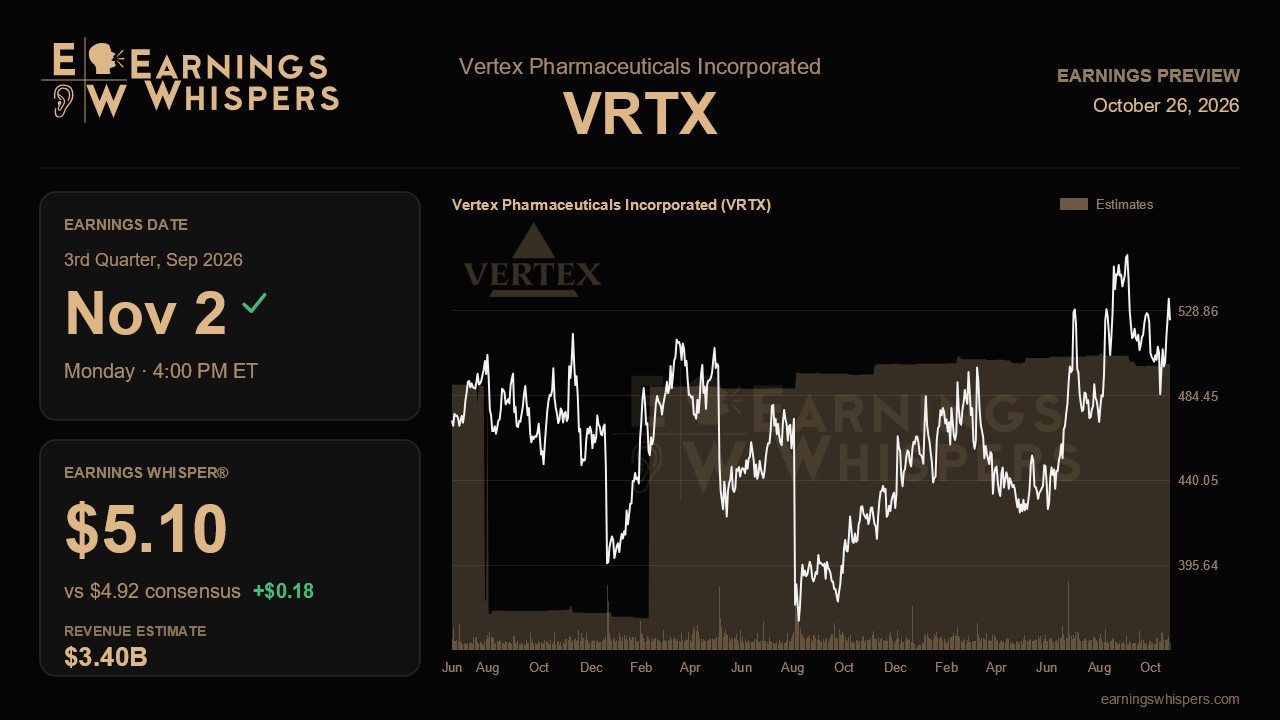
Wall Street expects non-GAAP earnings of $4.92 per share on revenue of $3.40 billion. That revenue figure implies growth of roughly 10.5% from the year-ago $3.08 billion. It is solid, but a touch slower than the 12% pace Vertex posted in the second quarter, which fits management's warning that second-half CF growth would get less help from prior-year US pricing and currency. The earnings whisper sits at $5.10, meaningfully above consensus, so the informal bar is higher than the published one. Notably, the full-year consensus of $13.06 billion still sits below management's raised range of $13.1 billion to $13.2 billion. Hitting even the low end of that guide implies second-half revenue of about $6.8 billion, so a Q3 print merely in line with estimates would leave Vertex comfortably on track, while anything above $3.45 billion would argue the range is conservative.
The launches carry the most narrative weight. Casgevi revenue jumped to $76 million last quarter, and patient initiations have topped 100 for three straight quarters, with the recently approved pediatric label widening the funnel. Another sequential step up would validate that infusions, not just initiations, are scaling. Gernavix is the trickier case. Prescriptions roughly doubled on a monthly basis during the first half and covered lives reached 260 million, yet management pushed gross-to-net normalization into the first half of 2027. That means revenue may keep lagging scripts. Investors should judge Gernavix less on the headline sales number and more on whether prescription growth stays brisk and whether pricing commentary holds steady rather than slipping again.
Profitability is the likely friction point. Gross margin dipped to 85.6% last quarter, and management flagged larger mix and manufacturing headwinds in the back half. Operating expenses are tracking toward the high end of the $5.65 billion to $5.75 billion range as Vertex staffs up for pain and renal launches. The roughly $8.8 billion Krenetics acquisition, expected to close in the third quarter and partly financed with a $4.5 billion term loan, adds interest costs and integration spending without contributing to operating income until 2029. Clean disclosure on how the deal reshapes 2026 expense and earnings guidance matters as much as the quarter itself. A beat built on revenue rather than expense timing would be the higher-quality outcome.
The market has already leaned in. Shares have gained about 11% since the last report while the S&P 500 was flat, and sentiment has warmed noticeably from barely positive to moderately bullish. At around $524, the stock is well above its 200-day moving average but roughly 6% below its post-earnings high of $560, so it is not pressing a breakout. That leaves room for upside on a convincing print, but also little patience for a soft one, especially with the November 30 decision date for povetacicept in IgA nephropathy looming just weeks later.
Ultimately, the report hinges on whether the non-CF launches are growing fast enough to offset slower CF tailwinds, heavier spending and acquisition dilution. If Casgevi and Gernavix extend their sequential gains while CF holds near double-digit growth, the five-pillar story looks earned. If revenue conversion stalls and margins slide further, the guidance raise starts to look like a first-half phenomenon.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-23 | |
| Oct-23 |
How Halozyme, Up 80% This Year, Is Rivaling Merck And Hitting New Highs
VRTX
Investor's Business Daily
|
| Oct-21 | |
| Oct-20 | |
| Oct-13 | |
| Oct-09 | |
| Oct-09 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 | |
| Sep-24 | |
| Sep-23 | |
| Sep-22 | |
| Sep-22 |
