Apollo's Record Momentum Faces A Skeptical Market As Stock Trades Near Post-Earnings Lows
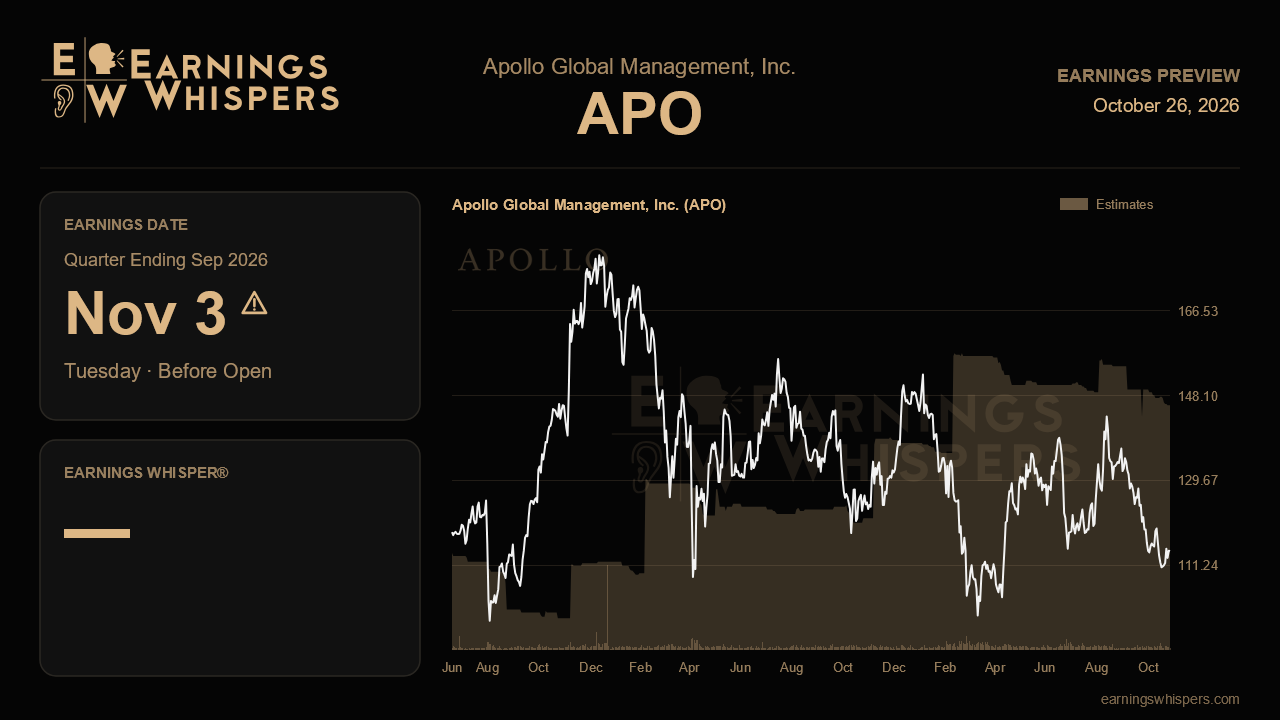
Apollo Global Management heads into its third-quarter report with an awkward mismatch between what the business said last time and what the stock has done since. Management called its second quarter a story of momentum, backed by records in fee-related earnings, spread-related earnings and capital solutions fees. The market has not bought the pitch. Shares have fallen 11.8% since that report while the S&P 500 was essentially flat, leaving the stock near $112.83. That is less than 3% above its post-earnings low and well beneath its 200-day moving average of about $124. This report needs to show that the momentum was real and not a single strong quarter.
The Street is looking for earnings of $2.04 per share, up 7.4% from $1.90 a year ago and a step up from the $1.95 posted last quarter. That is modest growth rather than a breakout. The revenue consensus of $1.34 billion implies an 86% drop from the year-ago $9.82 billion. That gap appears to reflect a narrower revenue measure than the consolidated figure, which includes Athene's insurance results, rather than any collapse in the business. Investors should focus on earnings quality and the underlying fee and spread engines rather than the headline revenue line.
Management reaffirmed full-year targets of more than 20% growth in fee-related earnings and roughly 10% growth in spread-related earnings, but did not raise them. That leaves room for an upgrade if the third quarter holds near second-quarter levels. Fee-related earnings reached $785 million, up 25% from a year earlier, with margins at 58.5% and on track for about a point of expansion this year. Another quarter near or above that level, with margins holding, would support the guidance. Spread-related earnings hit $877 million as net spread recovered to 114 basis points from 97. Keeping spreads above 100 basis points would confirm management's view that spreads bottomed in the first half of 2025. A slip back toward the high 90s would revive concerns about retail annuity competition, with roughly three dozen asset managers now crowding the broker channel.
Origination is the variable that matters most for the 2027 story. Volume of $74 billion was solid but flat for several quarters and well below the $97 billion record. Management pointed to $50 billion of signed or announced deals that will land in future quarters. The landmark $35 billion Broadcom financing will not start producing fees until the fourth quarter, so this report is a bridge quarter. The test is whether capital solutions fees can stay above $200 million for a sixth straight quarter without that help. Clear evidence that the deferred pipeline is converting would ease worries that growth depends on a few mega-deals.
The newer growth initiatives also deserve scrutiny. Estimated daily pricing for Apollo's credit funds was due to cover all credit assets by October 1. That is meant to open doors with traditional asset managers and retirement plans, so early commentary on demand matters. Market-making volume more than doubled to over $30 billion last quarter, and continued growth would show the trading platform scaling. Wealth fundraising softened to $3 billion amid industry-wide redemptions from non-traded vehicles. Management said third-quarter redemption requests were running at about half the second-quarter pace, and a rebound in flows would validate that read. Athene's inflows, at $42 billion in the first half, need to stay on pace for the $85 billion annual target. Alternative investment returns of about 10%, still short of the 11% target, remain a lingering drag.
Sentiment has improved to modestly bullish from slightly bearish heading into the last report, even as the stock lagged. With shares sitting near the bottom of their range, expectations embedded in the price look restrained. The central question is simple. Apollo must show that record fee and spread earnings are a sustainable run rate, with spreads holding and the origination backlog converting ahead of Broadcom. If it does, the gap between fundamentals and the share price becomes hard to ignore. If spreads or flows wobble, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 8 hours | |
| 9 hours | |
| 10 hours | |
| 12 hours |
Apollo Takes Strategic Stake in Mubadala Capital, Deepening Middle East Investment Ties
APO
Benzinga Private Markets
|
| 13 hours | |
| 13 hours | |
| 14 hours | |
| 14 hours | |
| 15 hours | |
| 15 hours | |
| 15 hours | |
| Oct-25 | |
| Oct-25 | |
| Oct-24 |
