Fiserv's First Report After A Guidance Reset Tests Whether The Shortfall Was Only Timing
Three months ago Fiserv cut every headline number in its 2026 outlook and installed its second chief executive in roughly a year, all while insisting the damage was about timing rather than anything structural. The third-quarter report, due before the open on November 3, is the first real chance to check that claim. Investors will not get a full verdict in one quarter, but they should learn whether the reset was big enough or merely the first step in a longer climb down.
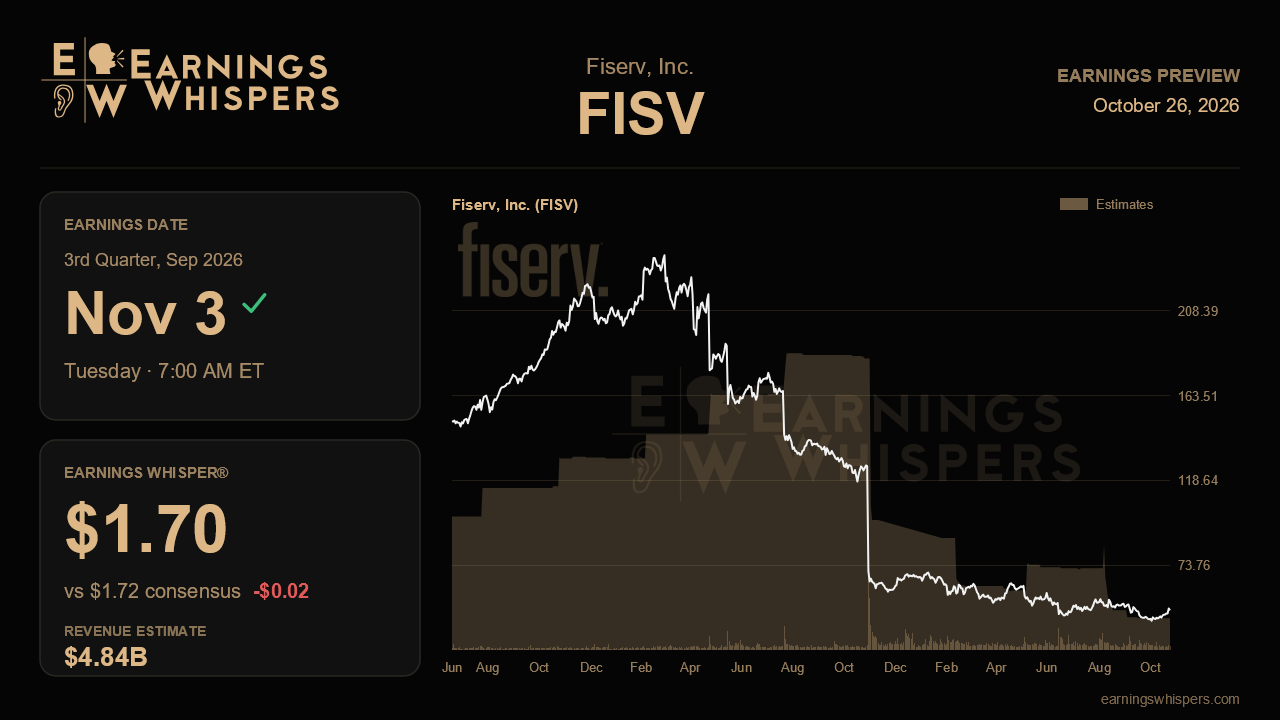
The Street is braced for contraction. Consensus calls for earnings of $1.72 a share, down about 16% from $2.04 a year ago, on revenue of $4.84 billion, roughly 8% lower than last year and a noticeable step down from the $5.29 billion reported last quarter. The earnings whisper sits at $1.70, a hair below consensus. That gap is too small to signal much, but it suggests no one is quietly expecting upside. Management now guides to full-year earnings of $7.20 to $7.40 a share on revenue of $19.6 billion to $19.8 billion, down from $8.00 to $8.30 and $20.0 billion to $20.4 billion. The full-year consensus of $8.13 still sits above the top of the new range, a sign that some estimates have not fully caught up. The quarterly target looks more realistic, so the bigger risk is less about this quarter and more about the full-year number coming down further.
The operational questions follow from last quarter's breakdown of the cut. Management blamed about two points of second-half pressure on delayed client and enterprise ramps, including one large go-live pushed back a quarter by a client's merger. If that conversion lands on schedule and implementation timelines look steadier, the timing argument gains real credibility. If more projects slip, the explanation starts to sound like a cover for weaker demand. Hardware weakness in the merchant business and lower anticipation revenue in Argentina were the other main drags. Both are outside management's control, so the question is whether they stabilized or got worse.
Clover remains the swing factor. Its revenue outlook fell from low double digits to mid-single digits, yet the underlying engine looked healthier than the headline: payment volume rose 11% excluding gateway, and value-added services climbed to 25% of Clover revenue. The worrying number was small-business volume, which slowed to 2% growth from 7% in the first quarter. Another slowdown would undercut the case that Clover's problems are mostly about hardware and Argentina. Margins deserve equal attention. The guide fell to about 31% from roughly 34%, partly because of more than $100 million in new technology and cybersecurity spending. After segment operating income fell 14% in Merchant and 27% in Financial Solutions last quarter, any sign of a floor would matter. So would continued free cash flow strength after last quarter's 112% conversion, which remains the clearest support for the stock.
The newer catalysts, including the Mastercard partnership, Western Alliance going live on Clover, and Flagstar choosing Finzact, will not move this quarter's results much. Still, signs of momentum would support management's reaffirmed medium-term targets. Updates on the new CEO's portfolio review, which could reach as far as the debit networks, could easily overshadow the quarterly figures.
The market's mood has thawed slightly. Sentiment sits at 50% bearish, versus 53.1% heading into last quarter, and the stock is unchanged since the last report while the S&P 500 slipped 1.3%. At $49.86, shares have bounced well off the post-report low of $43.87 but still trade below the 200-day average of $55.27, roughly midway through their recent range. The central question is simple. If Fiserv holds its lowered guidance, shows delayed revenue starting to come back, and keeps Clover's small-business volumes from slipping further, the reset looks like a floor. Another trim would suggest the new leadership is still uncovering problems.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 |
