Marathon Petroleum Faces A Higher Bar Than Its Record Quarter As Seasonal Caution Meets Lofty Estimates
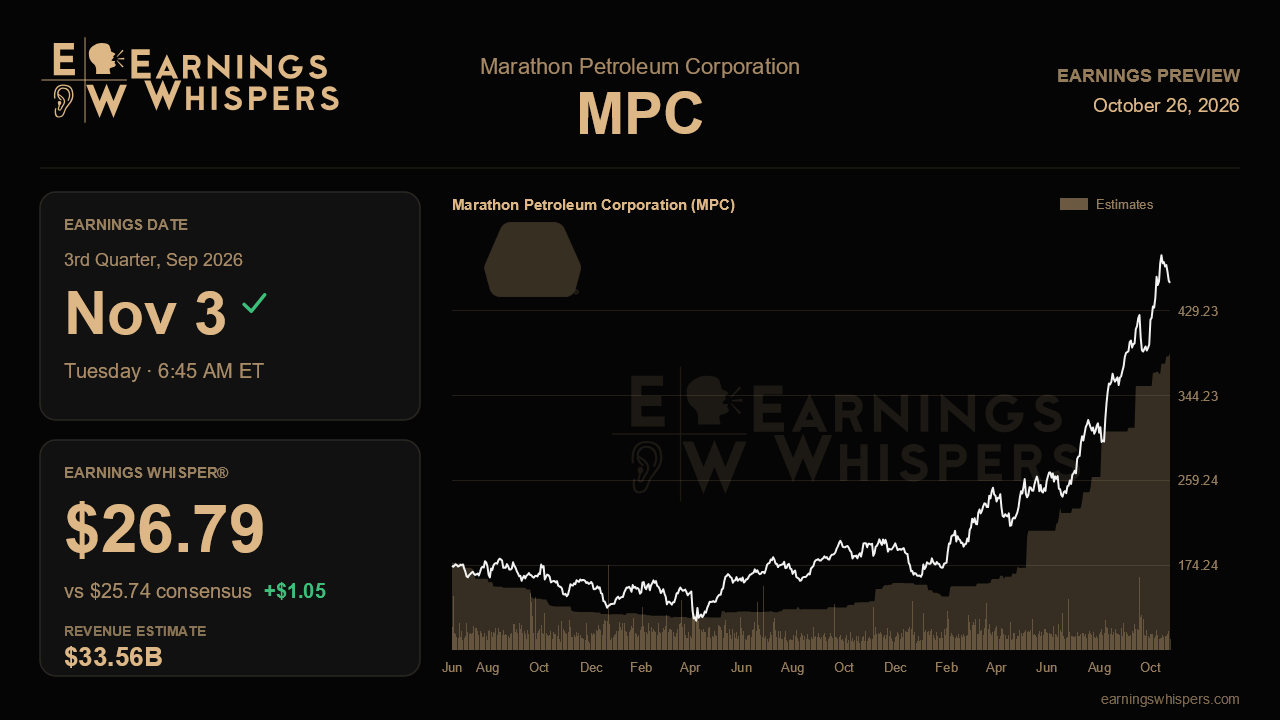
Three months ago, Marathon Petroleum delivered the kind of quarter refiners rarely see, then spent much of its conference call warning that the third quarter is usually its weakest for margin capture. Wall Street seems to have heard the caution and decided it doesn't apply. Analysts expect earnings of $25.74 a share when the company reports before the bell on November 3, well above the $17.73 it earned in the second quarter and roughly eight and a half times the $3.01 posted a year ago. The whisper number of $26.79 sits about 4% above consensus. That gap is modest, but it suggests the informal bar is higher still.
The revenue picture tells a different story. Consensus calls for $33.56 billion, down 6.4% from a year ago and far below the $52.34 billion reported last quarter. Lower sales paired with sharply higher profit means this report is entirely a margin story. Volume and pricing at the top line matter far less than how much Marathon keeps on each barrel it refines. With no formal guidance to anchor the estimate, the Street is effectively betting that the global refining tightness management described has outlasted the softening it flagged in July.
That tightness was the core of the prior narrative. Management pointed to more than 9 million barrels a day of refining capacity offline worldwide, Russian refinery outages and a Russian diesel export ban. Those conditions helped push refining and marketing EBITDA to $24.84 per barrel and capture to 112%. Marathon also leaned on self-help. It processed advantaged crude, including record Canadian heavy volumes, more Venezuelan barrels and SPR crude bought directly from the government. It finished its Robinson jet project ahead of schedule and lifted jet yield capability to 12%. The test now is whether those gains survive a quarter management itself described as the most muted, with capture averaging about 95% from 2023 to 2025. Capture near or above 100% would show the structural improvements are real rather than a one-quarter windfall. A drop toward the historical seasonal level would make the consensus look stretched, especially since executives said product margins and the jet-to-diesel spread had already pulled back a month into the quarter.
Cash flow deserves equal scrutiny. The second quarter got a $3.8 billion lift from working capital, which management expects to reverse as inventories rebuild and SPR and crude-exchange obligations are repaid. Analysts questioned why the company held roughly $7.8 billion in cash instead of spending more on buybacks. Management said the buildup reflected timing and SPR repayment rather than doubts about how long strong margins would last. A step-up from the $2.5 billion repurchased last quarter would support that explanation. Another quarter of hoarding would invite the same doubts. Two secondary items are worth checking. One is renewable diesel, which benefited from tight RIN supply that management called unsustainable. The other is MPLX, where Blackcomb commissioning and the accelerated Gulf Coast fractionation spending fall under a growth capital budget raised to $2.9 billion.
The stock has already priced in a great deal of optimism. Shares have climbed 48.1% since the last report while the S&P 500 was essentially flat. At $457.22 they sit far above the 200-day moving average of $283.24, but about 7% below the post-earnings high of $493.98, so this is not a breakout setup. Meanwhile, sentiment has swung from mildly bullish before the last report to 20.4% bearish now. That suggests a meaningful slice of the market suspects the easy gains are behind it.
The central question is simple. Can Marathon show that its capture improvements and crude advantages hold up in a seasonally weak quarter strongly enough to beat its own record? If capture holds and buybacks accelerate, the bulls keep their story. If capture fades toward the seasonal norm, the run in the stock will look like it got ahead of the barrels.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-16 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-09 | |
| Oct-09 | |
| Oct-09 | |
| Oct-09 |
