Pfizer Rallies Into Third Quarter As Whisper Bets Cost Cuts Can Offset Shrinking COVID Sales
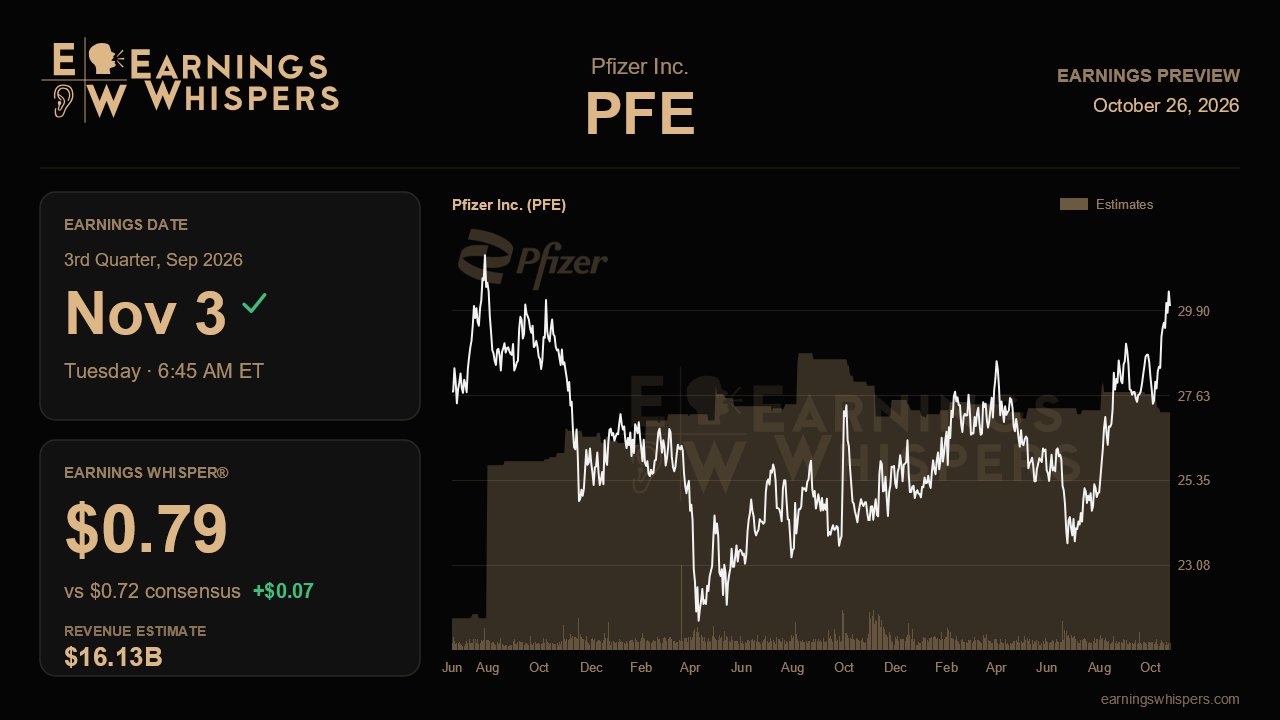
Pfizer heads into its third-quarter report with something it has lacked for a while: momentum in the share price. The stock has climbed nearly 20% since the company raised its full-year revenue outlook in the summer, while the S&P 500 has gone nowhere. That rally changes the question for November 3. It is no longer whether Pfizer can avoid disappointing. It is whether the improving story management described last quarter is solid enough to justify a stock now pressing against its post-earnings high.
On paper, the bar looks modest. Analysts expect earnings of $0.72 a share on revenue of roughly $16.13 billion, which would mark a 17% drop in profit and a 3% decline in sales from a year ago, when Pfizer earned $0.87 on $16.65 billion. That is a contraction quarter, and the main culprit is well known: management cut its COVID revenue expectation for the year to about $4 billion from about $5 billion, citing persistently low infection rates that weigh on Paxlovid. The more telling figure is the earnings whisper of $0.79, a meaningful seven cents above consensus. The market appears to believe Pfizer's expanded cost programs will cushion more of the COVID decline than published estimates assume.
Guidance supports that view without demanding heroics. Pfizer kept its full-year earnings target at $2.80 to $3.00 a share even while absorbing a roughly $0.10 charge tied to the InnoVent deal, and it lifted the bottom of its revenue range to put the outlook at $60.5 billion to $62.5 billion. Consensus sits at $2.96 a share and $61.86 billion, toward the upper end of both ranges. In other words, the Street is already leaning optimistic, which leaves little room for a soft quarter and makes the fourth-quarter implied run rate an important part of whatever management says.
The operating test centers on the non-COVID business, where management raised its expectations by about $1.5 billion on strength in Eliquis, PADSEV and Nurtec. Confirmation would look like PADSEV sustaining growth above 20% as its expanded bladder cancer label gains traction, and launched and acquired products holding growth near the high teens or better. Growth in that bucket cooled to 18% in the second quarter from 22% in the first, though management said it ran closer to 27% excluding a one-time item from last year. Another step down would challenge the idea that new products can carry Pfizer through its patent cliff. On the expense side, investors should look for visible margin benefit from cost savings that now total about $9.7 billion through 2029, including a manufacturing optimization target that doubled to roughly $3 billion. Any early read on how the voluntary pricing agreement with the U.S. government is affecting results will also matter.
There are softer spots to monitor. The failed lung cancer trial and resulting $4.3 billion impairment thinned oncology optionality, business development capacity has shrunk to about $6 billion to $7 billion, and an interim CFO will be presenting the numbers. Updates on the MEVPRO-1 prostate cancer readout expected this quarter and the obesity candidate verubenatide could shape the pipeline conversation more than the quarter itself.
Sentiment has improved but remains negative, with bearishness easing to about 31% from 37% ahead of the last report. Paired with a stock trading well above its 200-day average and within about 1.5% of its range high, that suggests skepticism is fading faster than the fundamentals are changing. The verdict hinges on whether non-COVID growth and cost discipline can deliver earnings closer to the whisper while keeping full-year guidance anchored near the top. If they do, the summer raise looks like the start of a trend. If not, the rally may have gotten ahead of the evidence.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 34 min | |
| 4 hours | |
| 5 hours | |
| 8 hours | |
| 8 hours | |
| Oct-24 | |
| Oct-23 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-20 | |
| Oct-20 | |
| Oct-17 | |
| Oct-16 | |
| Oct-16 |
