Shopify's Q3 Test: Can Revenue Beat Its Own Upgraded Guide As AI Costs Climb?
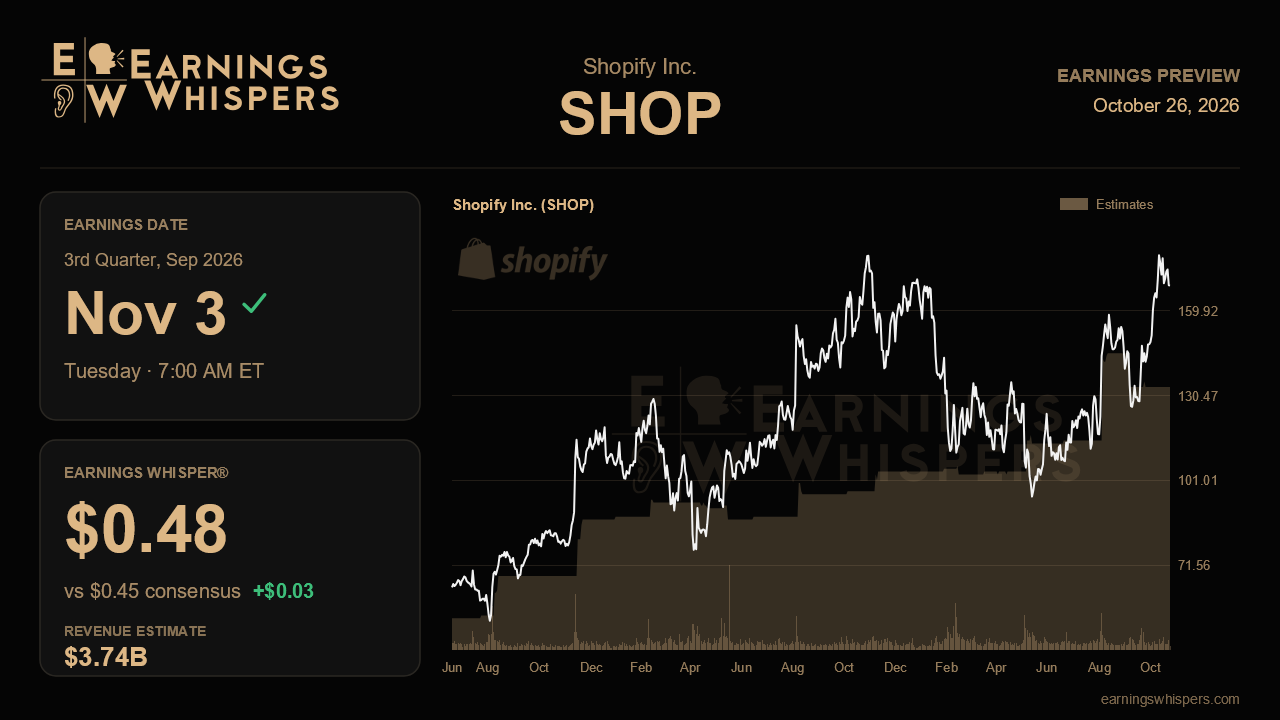
Shopify heads into its third-quarter report with an unusual problem: the company has already done much of Wall Street's work for it. After guiding to high-20s growth for the second quarter and then delivering 34%, management set a third-quarter revenue target of roughly $3.76 billion, well above the $3.57 billion the Street expected at the time. Analysts have since moved up to $3.74 billion, which sits just below the company's own figure. When Shopify reports before the bell on November 3, beating consensus will matter less than beating its own guide by a margin that resembles last quarter's.
The consensus revenue figure implies growth of about 31.5% from $2.84 billion a year ago. That is strong growth for a business of this size, and it compares with mid-to-high-20s growth in the year-ago quarter, but it would be a modest deceleration from the second quarter's 34%. On profits, analysts expect non-GAAP earnings of $0.45 per share, up sharply from $0.30 last quarter and $0.27 a year ago. The Earnings Whisper sits at $0.48, a few cents above consensus. The gap is not dramatic, but it suggests that more aggressive forecasters expect the operating leverage story to keep showing up in the bottom line.
That leverage is central to the thesis management laid out last quarter. Operating expenses fell to 34% of revenue from 37% in the first quarter, and the company guided the third quarter to 33% to 34%, against 37% a year earlier. Free cash flow margin improved to 18%. Holding or bettering those levels would confirm that Shopify can grow above 30% while spending less of each revenue dollar. The offsets are real, however. AI costs tied to Sidekick have kept subscription gross margins just below 80%, transaction and loan losses reached 3.9% of revenue as the capital business expanded, and gross profit was guided to mid-to-high-20s growth, below the revenue pace. If margins slip further or loss rates rise faster than lending volume, the earnings beat the Whisper implies becomes harder to deliver.
Under the headline numbers, the health checks are gross merchandise volume, payments penetration and merchant revenue. GMV grew 32% to $116 billion in the second quarter, the fifth straight quarter above 30%, and it accelerated against a tougher comparison. Another 30%-plus print would show the momentum is broad rather than a one-quarter spike. Payments penetration at 68% and monthly recurring revenue growth that rebounded to 19% after trial-related distortions faded are the clearest signs that Shopify is capturing more of each merchant relationship. Newer levers, including Managed Markets in Canada and the UK, Shopify Payments in the UAE, local payments in Mexico, broader B2B tools and enterprise wins such as Canada Goose, Aritzia and Balmain, should start to show up in commentary even if they are not yet material to revenue.
Agentic commerce is the narrative piece most exposed to scrutiny. Management argued last quarter that the effort had moved from building infrastructure to real adoption, citing dozens of retailers on its Universal Commerce Protocol and opening its catalog to outside builders. Yet AI-driven orders grew about 3 times year over year, down from double-digit multiples earlier in the year, and the company acknowledged that agentic GMV remains small. Investors should want evidence of monetization, such as attribution data from the new agentic dashboard, rather than another slowing growth multiple.
The market has already paid for confidence. Shares are up 12.5% since the last report while the S&P 500 fell 2.1%, and at $168.68 the stock trades well above its 200-day average of $130.06, though still several percent below its post-earnings high of $180.88. Sentiment has improved slightly but remains only mildly bullish. The verdict likely hinges on whether Shopify clears its own $3.76 billion target while showing that AI spending is not eroding the margin gains that made last quarter so convincing.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| Oct-25 | |
| Oct-24 | |
| Oct-23 | |
| Oct-22 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-17 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 |
