Yum Brands Earnings: Taco Bell's Food-Safety Recovery Faces Its First Full-Quarter Test
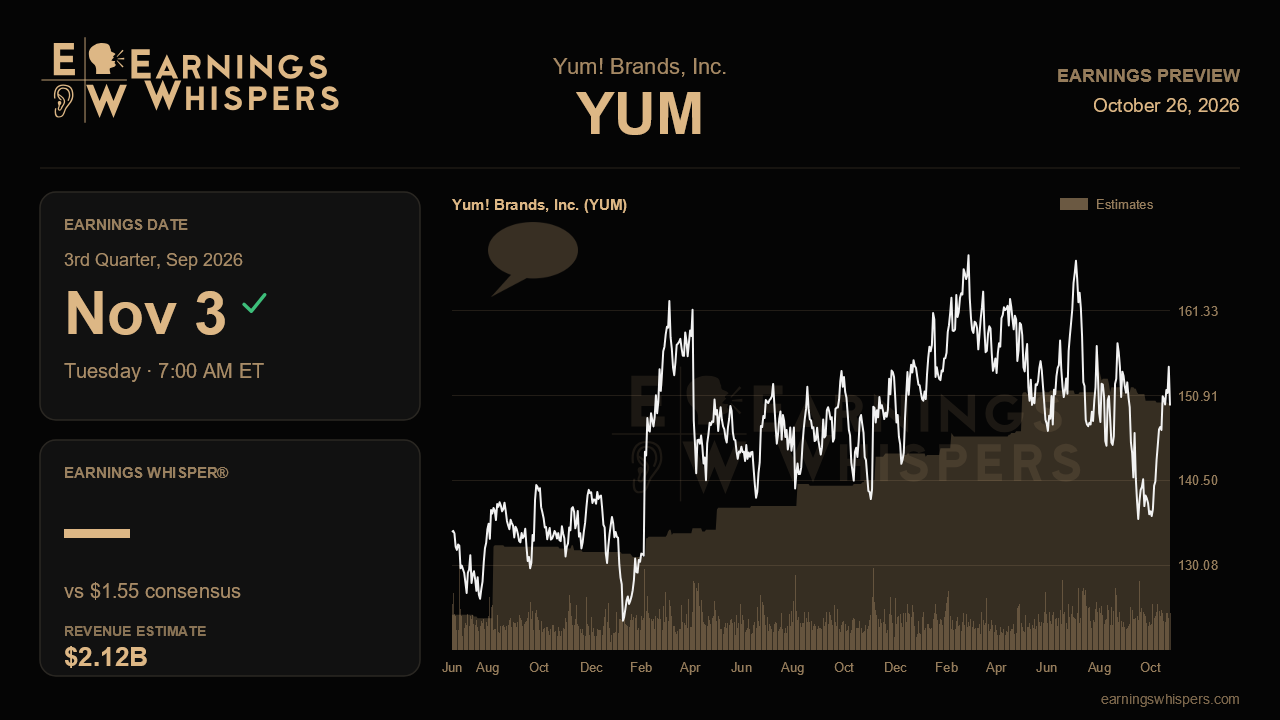
Three months ago, Yum Brands looked like a company finally getting simpler and stronger. The Pizza Hut sale was signed, KFC was posting some of its best numbers in years, and Taco Bell US had just outpaced the quick-service industry for a ninth straight quarter. Then an industry-wide US food-safety scare knocked Taco Bell, the company's most profitable domestic engine, from high single-digit comparable sales growth into negative territory almost overnight. The third-quarter report, due before the open on November 3, is the first full accounting of how much damage that shock did and how quickly the brand has climbed back.
Wall Street expects earnings of $1.55 per share, down about 1.9% from $1.58 a year ago, on revenue of roughly $2.12 billion, up 7.1%. That combination tells the story neatly: the top line is still growing, but profit per share is expected to slip as Taco Bell's margins absorb the hit. The EPS bar also sits below last quarter's $1.62, which suggests analysts have already baked in a meaningful step down rather than a quick snapback.
The most concrete yardstick is management's own warning. Executives guided Taco Bell US company-owned restaurant margins to just 19% to 21% for the quarter, well below the 24.5% to 25.5% full-year target they had laid out only a quarter earlier and far from the 26.2% achieved in the second quarter. They blamed lost sales leverage, promotional spending to win customers back, and the fact that company-operated stores were concentrated in the hardest-hit markets. A margin at or above the top of that range would signal the recovery ran faster than feared. A figure near or below 19% would imply the damage lingered and raise doubts about the full-year algorithm, which management notably stopped describing with unqualified confidence.
Comparable sales will matter just as much. When management last spoke, Taco Bell US was running down about 2% quarter to date, with the worst days far deeper than that, but sales had reportedly recovered about halfway in the prior few days and social sentiment had improved. That was a mere ten days of recovery data. The key question now is whether the brand exited September back near its prior growth trajectory or whether a cautious customer has kept traffic below where it stood in the spring. The redesigned Taco Bell app, slated for a third-quarter launch, could offer early evidence of whether digital engagement is helping lure guests back.
Outside the US, the story should be steadier. KFC was building momentum in the UK, Korea, Japan and Brazil and was on pace for its best development year ever, while its new modern chicken push around boneless tenders and an expanded sauce lineup is just beginning to roll out. Continued strength there would reinforce the argument that the Taco Bell problem is a temporary dent in an otherwise improving portfolio. Capital returns add another lever: with the Pizza Hut deal expected to close in August and most of the roughly $2.3 billion in net proceeds earmarked for buybacks, a shrinking share count could cushion per-share results.
The market has not been patient. Shares have fallen 7.6% since the last report while the S&P 500 gained 3.3%, and at about $150 the stock sits below its 200-day moving average, roughly midway between its post-earnings low of $134 and high of $166. Sentiment remains bearish but somewhat less so than heading into the prior report, hinting that the worst fears may have eased. Ultimately, this report hinges on one question: was the Taco Bell setback a contained, one-quarter event, or a lasting crack in the brand's traffic and margin story? Clear evidence of a rebound would let KFC and the cleaner post-Pizza Hut structure take center stage again.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 7 hours | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 |
Dow Jones Leader Coca-Cola Breaks Out As Stock Market Volatility Ramps Up
YUM
Investor's Business Daily
|
| Oct-20 |
