Amgen Faces Margin Test As Spending Climbs After Two Straight Guidance Raises
Amgen heads into its third-quarter report with a curious mismatch. Management has raised its full-year outlook twice, the stock has surged to the edge of a new high, and yet the Street is modeling a quarter that looks almost flat on earnings. The question for November 3 is whether the commercial momentum management described in the summer can absorb a deliberately heavier spending quarter without denting the story.
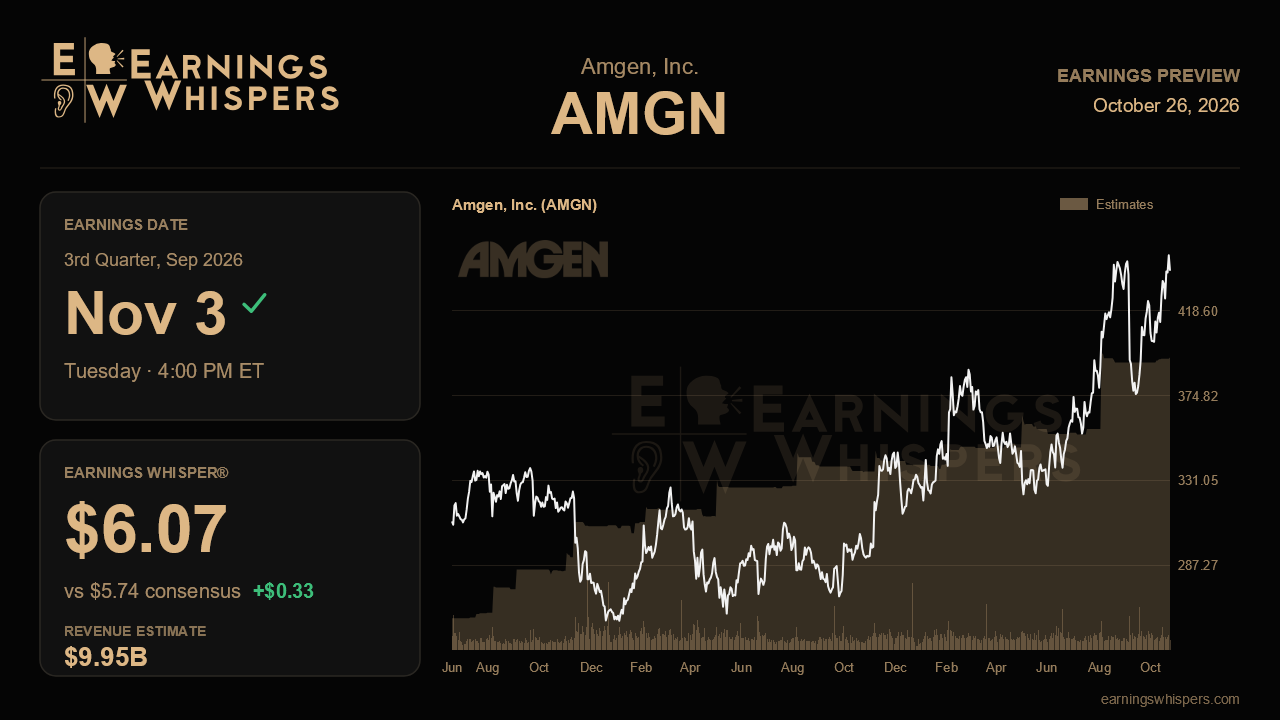
Consensus calls for earnings of $5.74 per share on revenue of $9.95 billion, which works out to growth of about 1.8% on the bottom line and 4.1% on the top. That is modest progress for a company that grew second-quarter revenue roughly 10% and posted $6.29 per share. Part of the gap is self-inflicted and telegraphed: management warned of a meaningful sequential step-up in operating expenses, including a $100 million upfront payment on a business development deal that runs through non-GAAP research and development. The Earnings Whisper of $6.07 sits well above consensus, signaling that the informal bar is closer to last quarter's pace than the published estimate suggests.
The guidance comparison sharpens that point. Amgen now expects 2026 earnings of $22.30 to $23.50 per share on revenue of $38.2 billion to $39.4 billion, up from $21.70 to $23.10 and $37.1 billion to $38.5 billion previously. Consensus earnings of $22.31 sit essentially at the bottom of that range, and the revenue estimate of $37.73 billion is actually below management's floor. Either analysts are skeptical of the second-half trajectory or their models have not caught up. A third-quarter print near $10 billion in revenue would make the low-end assumptions hard to defend.
The operational evidence that matters most is whether the six growth drivers keep compounding. They accelerated to 26% aggregate growth last quarter from 24%, with Repatha up 37%, Evenity up 38%, Uplizna up 90%, Imdeltra up 115% and Pavblu up 121%. Repatha deserves particular scrutiny. Strong cardiovascular outcomes data and a favorable European regulatory opinion support a broader label, but Merck's newly approved oral PCSK9 introduces the first real in-class challenger. Management downplayed its label breadth and food restrictions; continued acceleration in Repatha volume would validate that confidence, while a noticeable slowdown would give the competitive worry real weight. On the other side of the ledger, Prolia and Xgeva fell 33% on biosimilar competition. That erosion is expected, so the test is whether it stays on its known path rather than steepening.
Margins are the other swing factor. Operating margin jumped to 48% from 45% and free cash flow more than doubled to $3.5 billion. Some compression is baked in given the spending build, but a margin that holds up better than feared would argue that operating leverage from the growth portfolio is outrunning investment. Investors will also want updates on MariTide's Phase III enrollment and tolerability, the new Uplizna programs in autoimmune hepatitis and CIDP, lingering overhangs from the IRS tax dispute and Tavneos, and the first look at incoming CFO Thomas Dittrich's style.
The market has already rewarded the story. Shares have climbed 11.7% since the last report while the S&P 500 slipped 2.1%, and at $439.26 the stock trades about 18% above its 200-day average and within 3% of its post-earnings high of $450.98, an entire range sitting above last quarter's ceiling. Sentiment, however, has cooled from mildly bullish to mildly bearish, suggesting some wariness after the run. The deciding issue is straightforward: if growth-driver volumes stay strong enough to keep full-year guidance comfortably intact despite higher spending, the narrative of durable growth holds. If the expense build reveals softer underlying momentum, the stock's premium leaves little cushion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-24 | |
| Oct-23 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 |
