Booking Holdings Faces A Growth Test As The Street Sits Atop Its Cautious Guide
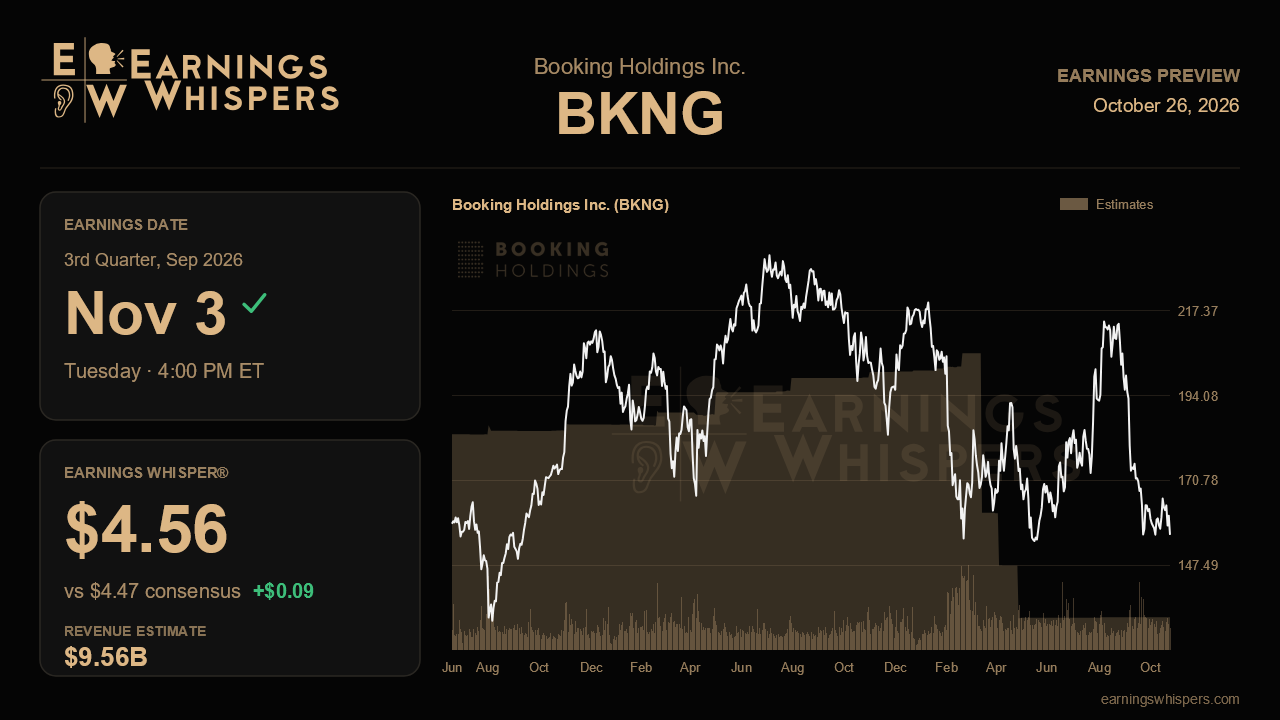
Booking Holdings heads into its third-quarter report with a peculiar mismatch: the business keeps getting more profitable, yet the stock has been treated as if something is broken. Shares have fallen 25% since the last report while the S&P 500 slipped about 2%. The question for the November 3 release, due after the close, is whether slowing travel demand is a temporary flight-driven wobble or the start of a longer deceleration that margin discipline can no longer disguise.
Wall Street expects earnings of $4.47 per share on revenue of $9.56 billion, which would be roughly 6.1% top-line growth. The headline EPS comparison, a decline of about 95%, is not a useful signal. The year-ago figure of $99.50 sits on a very different per-share basis than today's estimates and the recent $2.54 quarterly result, so the comparison distorts rather than informs. Revenue is the cleaner gauge. Management guided to $9.37 billion to $9.55 billion, and consensus has since been pulled down from $9.78 billion to land just above the top of that range. In growth terms, the company framed revenue, gross bookings and adjusted EBITDA all rising 4% to 6%, so analysts are effectively assuming Booking performs at the high end again. The whisper number of $4.56 sits about 2% above consensus, a modest signal that some investors expect the company's habit of clearing its own targets to continue.
That habit matters, because last quarter Booking beat across the board yet still trimmed its full-year gross bookings outlook to high single digits from the low double digits it projected at the start of the year. The cut came mostly from flights, where ticket growth collapsed to 4% from 28% a quarter earlier as Middle East conflict reduced capacity and pushed up fares. Management described its accommodation outlook as largely unchanged, but the core metric has been sliding anyway. Room nights grew 5%, down from 9% two quarters earlier, and the third-quarter guide calls for just 3% to 5%. Alternative accommodations, historically a roughly 10% grower, managed only 4%. Room nights landing at or above 5% would support the view that lodging is holding steady; a print near 3% would suggest the weakness is spreading beyond air travel.
Geography is the second tell. Domestic and U.S. travel carried the last quarter, with U.S. room nights up high single digits, while long-haul international was only slightly positive. Management assumed indirect Middle East effects would persist through the third quarter, so any stabilization in international trips would be upside. Signs that flight growth has bottomed and that rental cars have stopped shrinking would also help rebuild confidence in the connected trip strategy, where transactions had been growing at more than twice the company-wide rate.
The profit side is where Booking has earned credibility. Transformation savings were raised to about $650 million, merchant mix climbed to roughly 73% of gross bookings, AI is cutting customer service cost per booking by double digits, and buybacks reduced the share count by about 6%. Continued margin expansion and heavy repurchases should cushion EPS even if revenue lands mid-range, which is why the earnings line is less likely to disappoint than the growth metrics.
Sentiment has turned from mildly bullish heading into last quarter to mildly bearish now, and the stock trades near $156, well below its 200-day average of about $179 and just above its post-report low of $154. Expectations, in other words, look subdued. The central issue is whether room nights and fourth-quarter commentary show the deceleration leveling off. If they do, the self-help story regains its footing; if not, cost cuts alone may not be enough to restore the growth narrative.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-21 | |
| Oct-19 | |
| Oct-16 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 |
AI Agents Are a Threat to Travel Businesses. Airbnb Could Still Be a Winner.
BKNG
The Wall Street Journal
|
| Oct-11 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Oct-06 | |
| Oct-06 | |
| Oct-05 |
