Supermicro's Raised $18.5 Billion Floor Faces A Street That Still Doubts Delivery
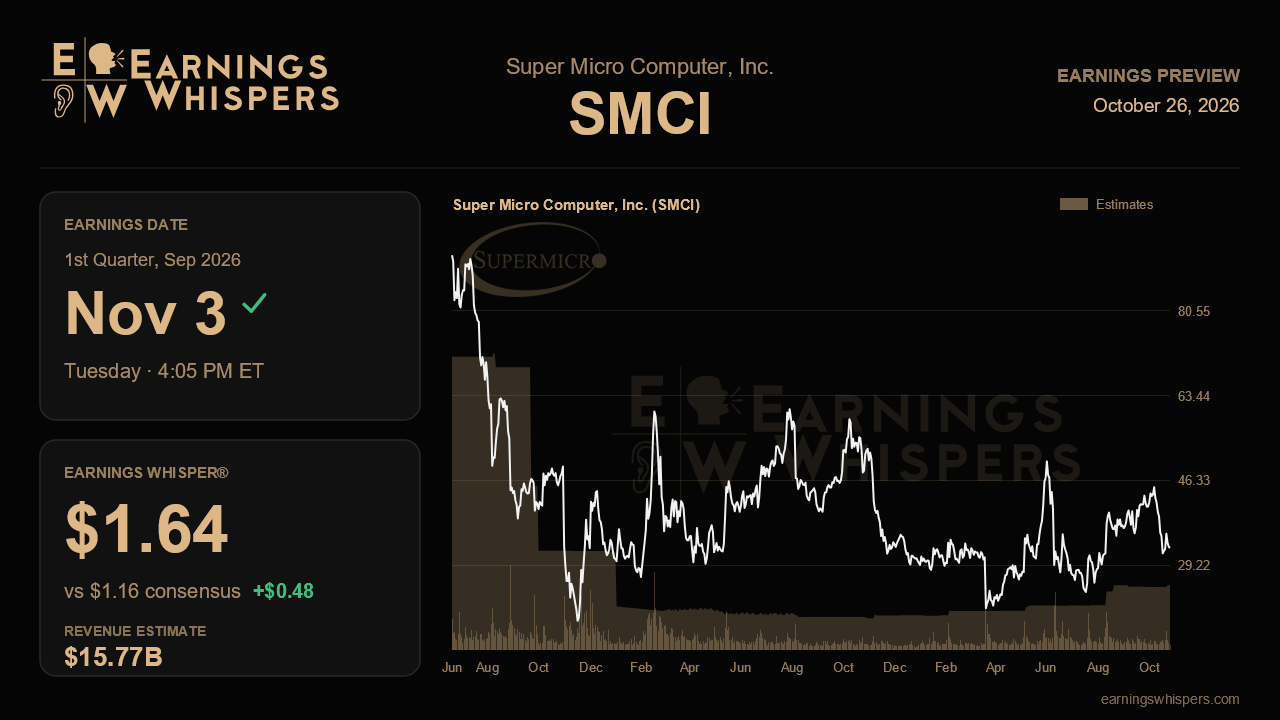
Supermicro heads into its fiscal first-quarter report with an unusual gap between what management has promised and what Wall Street has penciled in. After its last report, the company lifted its revenue outlook for the September quarter to a range of $18.5 billion to $19.5 billion, up from $14.5 billion to $15.5 billion. Consensus has moved only partway, to about $15.77 billion, which sits well below even the low end of the new range. For a company that has missed or barely scraped by its revenue targets three quarters in a row, that skepticism is earned. The report on November 3 will show whether it is still warranted.
Analysts expect non-GAAP earnings of $1.16 per share. Revenue at consensus would be up roughly 214% from the $5.02 billion reported a year ago, so even the cautious view assumes explosive growth. The Earnings Whisper of $1.64 is far above consensus and closer to the $1.57 earned last quarter, which suggests the informal bar is set nearer to management's guidance than published estimates imply. One wrinkle: reported EPS now falls under a two-class method because of the $4.2 billion mandatory convertible preferred issued in June, which mechanically dilutes the per-share figure. Comparing quarters on headline EPS alone could mislead.
The central question is whether delayed AI deployments finally convert into recognized revenue. Last quarter's $11.1 billion landed near the bottom of guidance as customers struggled with power, cooling and site readiness, and management said some contracts slid from June into this quarter. That deferral is a big part of why the September guide jumped. A print inside the $18.5 billion to $19.5 billion range would validate the idea that the slippage was timing, not lost demand, and that the record $60 billion-plus in orders booked last quarter is real and shippable. Another result near the low end, or below it, would revive the concern that Supermicro's backlog moves at the speed of its customers' data centers rather than its own factories, a meaningful worry for a company building toward more than 6,000 racks a month of capacity.
Margins are the second test, and expectations need calibrating. The 17.6% non-GAAP gross margin reported in the June quarter was a dramatic jump, but management attributed roughly three-quarters of the beat to favorable mix, including the deferral of low-margin contracts, plus one-time inventory reserve and tariff benefits. Guidance of 10.4% to 10.8% for this quarter reflects those low-margin deals coming back. Landing in that range while shipping far more volume would be a solid outcome. The more telling signals are whether enterprise and channel business, which reached half of revenue last quarter, holds its share as AI shipments return, and whether the new software and service offerings start to support a structurally higher margin floor. Cash conversion, which stretched to 149 days, also deserves attention given that growth this fast consumes working capital.
The market has not given the company much credit. Shares are down 6.6% since the last report against a 1.2% dip in the S&P 500, and they trade at $32.69, barely above the 200-day moving average and much closer to the post-earnings low of $30.92 than the $45.77 high. Sentiment has also soured, with a bearish reading of 35.5% compared with 25.6% heading into the prior report. An unresolved board and Justice Department review of export violations by former employees adds an overhang that a clean quarter alone may not lift.
That combination of low expectations and an aggressive guide sets up a clear verdict. If Supermicro delivers revenue inside its raised range with margins on target and reaffirms its $65 billion to $72 billion fiscal 2027 outlook, the profitability-plus-scale story gains real credibility. If revenue slips again, the record backlog will start to look less like a forecast and more like a promise.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 26 min | |
| Oct-26 | |
| Oct-25 | |
| Oct-23 | |
| Oct-23 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 |
