SoFi Reports Third Quarter 2026 with Record Net Revenue of $1.4 Billion, Net Income of $241 Million and Raises Full-Year Guidance
Adjusted Net Revenue up 44% to a record $1.4 billion
Adjusted EBITDA up 70% to a record $470 million
Adjusted Net income of $243 million, with $0.18 EPS
Member growth up 35% to a record 17.1 million members
Product growth up 44% to a record 26.7 million products
Raised 2026 guidance to $5.04 billion adjusted net revenue, $1.66 billion adjusted EBITDA
Introduced 2027 outlook of $6.4 billion adjusted net revenue, $2.24 billion adjusted EBITDA, $0.90 of EPS
SAN FRANCISCO--(BUSINESS WIRE)--SoFi Technologies, Inc. (NASDAQ: SOFI), a member-centric, everything app for digital financial services that helps members borrow, save, spend, invest and protect their money, reported financial results today for its third quarter ended September 30, 2026.
“We had exceptional Q3 results against the backdrop of any environment, but they are even more remarkable given how 2026 has unfolded,” said Anthony Noto, CEO of SoFi. “Our focus is simple. We are adding more members, who are using more products, and generating more revenue per product to create the most value for our shareholders over the long run. In less than a decade, we have transformed SoFi from a single-product company into an everything financial app with eight different businesses each generating over $100 million in annualized revenue. Our conviction in the opportunity ahead has never been greater.”
Consolidated Results Summary
|
|
Three Months Ended
|
| % Change |
|
Nine Months Ended
|
| % Change | ||||||||||||||
($ in thousands, except per share amounts) |
| 2026 |
| 2025 |
|
| 2026 |
| 2025 |
| ||||||||||||
Consolidated – GAAP |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Total net revenue |
| $ | 1,385,099 |
|
| $ | 961,600 |
|
| 44 | % |
| $ | 3,704,143 |
|
| $ | 2,588,303 |
|
| 43 | % |
Net income |
|
| 240,989 |
|
|
| 139,392 |
|
| 73 | % |
|
| 564,312 |
|
|
| 307,771 |
|
| 83 | % |
Net income attributable to common stockholders – diluted |
|
| 240,989 |
|
|
| 139,738 |
|
| 72 | % |
|
| 564,704 |
|
|
| 308,807 |
|
| 83 | % |
Earnings per share attributable to common stockholders – diluted |
| $ | 0.18 |
|
| $ | 0.11 |
|
| 64 | % |
| $ | 0.41 |
|
| $ | 0.25 |
|
| 64 | % |
Consolidated – Non-GAAP(1) |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Adjusted net revenue |
| $ | 1,371,124 |
|
| $ | 949,626 |
|
| 44 | % |
| $ | 3,663,906 |
|
| $ | 2,578,576 |
|
| 42 | % |
Adjusted EBITDA |
|
| 469,818 |
|
|
| 276,881 |
|
| 70 | % |
|
| 1,167,540 |
|
|
| 736,301 |
|
| 59 | % |
Adjusted net income |
|
| 242,986 |
|
|
| 139,392 |
|
| 74 | % |
|
| 570,123 |
|
|
| 307,771 |
|
| 85 | % |
Adjusted net income attributable to common stockholders – diluted |
|
| 242,986 |
|
|
| 139,738 |
|
| 74 | % |
|
| 570,515 |
|
|
| 308,807 |
|
| 85 | % |
Adjusted earnings per share – diluted |
| $ | 0.18 |
|
| $ | 0.11 |
|
| 64 | % |
| $ | 0.43 |
|
| $ | 0.26 |
|
| 65 | % |
| ____________________ | ||
(1) | For more information and reconciliations of these non-GAAP measures to the most comparable GAAP measures, see “Non-GAAP Financial Measures” and Table 2 to the “Financial Tables” herein. | |
Highlights
- Raising Guidance on Continued Business Momentum. Given the strength and visibility across the business, SoFi raised its 2026 guidance above analyst estimates1, reflecting both the third quarter beat and higher expectations for the fourth quarter of 2026. SoFi now expects $5.04 billion of adjusted net revenue which is a year-over-year increase of 40%, $1.66 billion of adjusted EBITDA, $840.0 million of net income and $0.61 of EPS. The company also introduced 2027 guidance of approximately $6.4 billion adjusted net revenue, $2.24 billion of adjusted EBITDA, $1.28 billion of net income and $0.90 of EPS, all of which are well ahead of analyst estimates1. The 2027 outlook represents approximately 27% adjusted net revenue growth and an adjusted net income margin of approximately 20%.
- Delivering Record Results with Durable Growth and Strong Returns. Adjusted net revenue increased 44% year-over-year to $1.4 billion, while adjusted EBITDA increased 70% to $469.8 million, representing a 34% margin. SoFi achieved the Rule of 40 for the 20th consecutive quarter, with a score of 79. SoFi also delivered its 12th consecutive profitable quarter with adjusted net income of $243.0 million, and a return on tangible common equity of approximately 10%. Fee-based revenue reached approximately $570.6 million, representing 42% of total revenue.
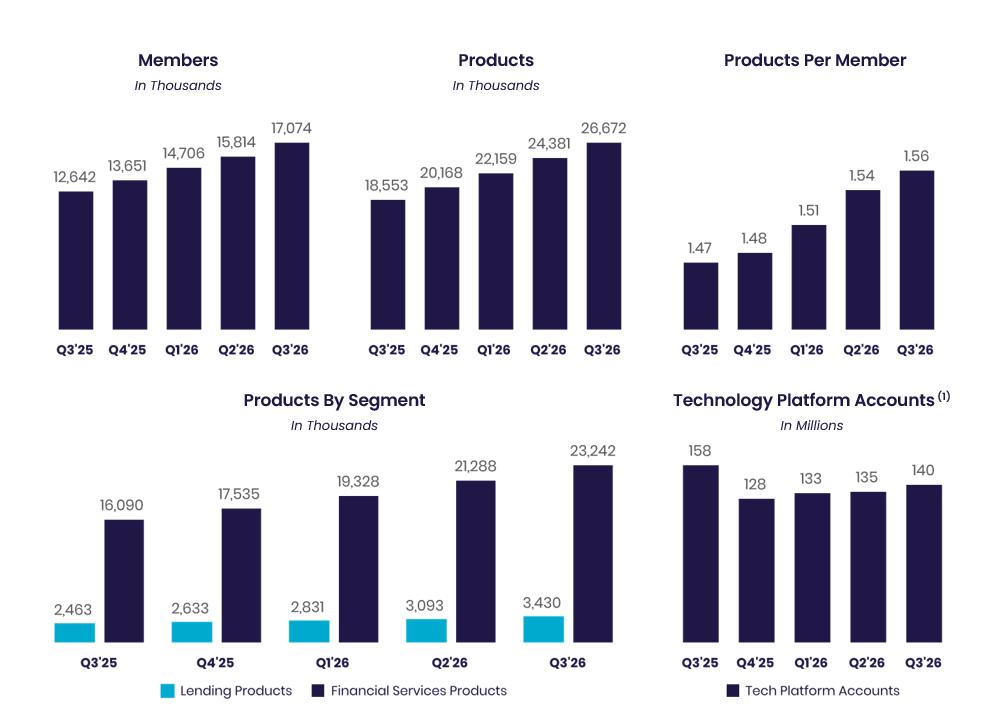
- Growing Members, Products and Revenue Per Product. SoFi grew members 35% year-over-year to 17.1 million, adding a record 1.2 million members during the quarter, while products increased 44% to 26.7 million, including a record 2.2 million products added. Products per member increased to approximately 1.56 from 1.47 a year ago and 51% of new products were opened by existing members. This continued growth reflects the strength of SoFi’s Financial Services Productivity Loop (FSPL) strategy, as members use more products, relationships deepen and the opportunity to generate revenue from each relationship expands.
- Achieving Record Loan Originations While Maintaining Strong Credit Performance. Total loan originations reached a record $16.9 billion, including approximately $3.8 billion of Loan Platform Business originations. Lending adjusted net revenue reached approximately $807.4 million, while Lending products increased 39% year-over-year to 3.4 million, and credit performance remained strong and in line with expectations. Personal Loan products reached approximately 2.6 million, Student Loan products reached approximately 760,000 and Home Loan products reached approximately 72,000. Lending adjusted revenue per product increased to approximately $942, compared with approximately $920 in the second quarter of 2026 and $782 in the third quarter of 2025.
- Driving Financial Services Revenue Through Product Growth and Monetization. Financial Services revenue increased 25% year-over-year to approximately $525.1 million, while products grew 44% to 23.2 million. Money and Relay drove the greatest absolute growth, each surpassing 8 million products and increasing 34% and 45%, respectively. Invest grew 37% to more than 4 million products, while Credit Card grew 67% to approximately 656,000 products, with a high percentage of primary card users and strong credit performance. Annualized Financial Services revenue per product increased to approximately $90 in the third quarter from $88 in the second quarter of 2026, reflecting continued monetization through deposits, spending, brokerage, lending referrals, subscriptions, credit card balances and other fee-based services.
- Setting Bold Ambitions for 2030. SoFi now has eight businesses that each generated over $100 million in annualized revenue. By 2030, the Company plans on reaching 100 million products and scaling five businesses to more than $1 billion in revenue, five businesses to more than $500 million in revenue and five businesses to more than $100 million in revenue. This reflects SoFi's strategy to evolve from a single-product student loan refinancing business in 2018 to an everything financial app serving 17.1 million members today.
| ____________________ | ||
1 | Analyst estimates per FactSet, as of October 26, 2026. | |
Consolidated Results
SoFi reported a number of record financial achievements. For the third quarter of 2026, record GAAP net revenue of $1.4 billion increased 44% relative to the prior-year period's $961.6 million. Adjusted net revenue of $1.4 billion was also a record, increasing 44% from the prior-year period of $949.6 million.
For the third quarter of 2026, total fee-based revenue reached $570.6 million, representing 42% of total revenue in the quarter and increasing 21% from the prior quarter. This was driven by strong contributions from origination fees, SoFi Tech Solutions revenue, strong performance from our Loan Platform Business, interchange revenue, and brokerage fee revenue.
Net interest income of $929.5 million for the third quarter was up 59% year-over-year. This was driven by a 51% increase in average interest-earning assets and a 38 basis point decrease in cost of funds, partially offset by a 3 basis point decrease in average asset yields year-over-year. For the third quarter, net interest margin of 6.14% increased 16 basis points from the prior quarter.
During the quarter, average total deposits comprised 90% of average total liabilities. The average rate paid on deposits in the third quarter was 145 basis points lower than that paid on warehouse facilities, which translates to approximately $745.0 million of annualized interest expense savings due to the successful remixing of our funding base.
Third quarter record adjusted EBITDA of $469.8 million increased 70% from the prior year period's $276.9 million. This represents an adjusted EBITDA margin of 34%.
For the third quarter of 2026, GAAP net income reached $241.0 million and diluted earnings per share reached $0.18.
Equity grew by $218.9 million during the quarter to $11.3 billion and $8.71 of book value per share. Tangible book value grew by $234.7 million during the quarter, ending the period at $9.7 billion. Tangible book value per share was $7.48 at quarter-end, up from $5.97 per share in the prior year period, a 25% increase.
Member and Product Growth
Continued growth in both total members and products in the third quarter is the result of our continued investments in innovation and brand building and reflects the benefits of our broad product suite and unique FSPL strategy. SoFi has reached significant scale whereby member growth, product growth, and revenue per product are key drivers of business performance.
SoFi added a record 1.2 million members in the third quarter of 2026, bringing total members to 17.1 million, up 35% from 12.6 million at the end of the same prior year period.
SoFi also achieved record product additions of 2.2 million in the third quarter of 2026, bringing total products to nearly 26.7 million, up 44% from 18.6 million at the end of the same prior year period.
Financial Services products increased by 44% year-over-year to 23.2 million, primarily driven by continued demand for our SoFi Money, Relay and Invest products, and drove 88% of our total product growth. Financial Services products account for 87% of total products.
Lending products increased by 39% year-over-year to 3.4 million, driven by continued demand for personal, student, and home loan products.
Technology Platform-enabled accounts decreased 11% year-over-year to 140 million, including the impact from a large client which fully transitioned off the platform prior to December 31, 2025. Technology Platform-enabled accounts increased 6 million from the prior quarter.
Financial Services Segment Results
For the third quarter of 2026, Financial Services segment net revenue of $525.1 million increased 25% from the prior year period. Financial services revenue per product was $90 compared to $88 in the second quarter of 2026.
Financial Services segment performance was driven by a combination of noninterest income which increased 13% year-over-year to $243.8 million and net interest income which increased 38% year-over-year to $281.3 million, primarily driven by growth in consumer deposits.
In the third quarter, SoFi's Loan Platform Business added $153.4 million to our consolidated adjusted net revenue. Of this, $151.2 million was driven by $3.8 billion of loans originated on behalf of third parties as well as referrals to third parties.
In addition to our Loan Platform Business, SoFi continued to see healthy growth in interchange fee revenue and brokerage fee revenue. In the third quarter, Financial Services interchange fee revenue was up 77% year-over-year, as a result of $31 billion in total annualized spend in the quarter across SoFi Money and Credit Card. Brokerage fee revenue was up 47% year-over-year, reflecting strong member demand and increased monetization.
Contribution profit for the third quarter of 2026 reached $261.0 million, a $35.5 million improvement over the prior year period, while contribution margin declined 4 percentage points year-over-year to 50%.
Financial Services – Segment Results of Operations | ||||||||||||||||||||||
|
|
Three Months Ended
|
|
|
|
Nine Months Ended
|
|
| ||||||||||||||
($ in thousands) |
| 2026 |
| 2025 |
| % Change |
| 2026 |
| 2025 |
| % Change | ||||||||||
Net interest income |
| $ | 281,254 |
|
| $ | 203,660 |
|
| 38 | % |
| $ | 758,046 |
|
| $ | 570,181 |
|
| 33 | % |
Noninterest income |
|
| 243,841 |
|
|
| 215,963 |
|
| 13 | % |
|
| 661,870 |
|
|
| 515,094 |
|
| 28 | % |
Total net revenue – Financial Services |
|
| 525,095 |
|
|
| 419,623 |
|
| 25 | % |
|
| 1,419,916 |
|
|
| 1,085,275 |
|
| 31 | % |
Provision for credit losses |
|
| (14,737 | ) |
|
| (9,199 | ) |
| 60 | % |
|
| (37,383 | ) |
|
| (24,869 | ) |
| 50 | % |
Directly attributable expenses |
|
| (249,344 | ) |
|
| (184,867 | ) |
| 35 | % |
|
| (713,259 | ) |
|
| (498,285 | ) |
| 43 | % |
Contribution profit – Financial Services |
| $ | 261,014 |
|
| $ | 225,557 |
|
| 16 | % |
| $ | 669,274 |
|
| $ | 562,121 |
|
| 19 | % |
Contribution margin – Financial Services(1) |
|
| 50 | % |
|
| 54 | % |
|
|
|
| 47 | % |
|
| 52 | % |
|
| ||
| ____________________ | ||
(1) | Contribution margin is defined for each of our reportable segments as contribution profit divided by net revenue. | |
By continuously innovating with new and relevant offerings, features and rewards for members, SoFi grew total Financial Services products by 7.2 million, or 44%, year-over-year, bringing the total to 23.2 million at quarter-end. SoFi Money reached 8.5 million products, Relay (Coach) reached 8.7 million products, SoFi Invest reached 4.2 million products, Crypto reached 503 thousand products and SoFi Plus reached 273 thousand products by the end of the third quarter.
In the third quarter of 2026, total deposits grew $5.8 billion to $51.3 billion, which included strong growth in member deposits.
Financial Services – Products |
| September 30, |
|
| |||||||
|
| 2026 |
| 2025 |
| % Change | |||||
Money(1) |
|
| 8,501,822 |
|
|
| 6,336,705 |
|
| 34 | % |
Invest(2) |
|
| 4,180,957 |
|
|
| 3,045,078 |
|
| 37 | % |
Credit Card(3) |
|
| 656,132 |
|
|
| 392,008 |
|
| 67 | % |
Referred loans(4) |
|
| 194,465 |
|
|
| 135,535 |
|
| 43 | % |
Crypto(5) |
|
| 503,070 |
|
|
| — |
|
| n/m | |
SoFi Plus(3) |
|
| 272,835 |
|
|
| — |
|
| n/m | |
At Work |
|
| 202,554 |
|
|
| 147,348 |
|
| 37 | % |
Relay (Coach) |
|
| 8,729,690 |
|
|
| 6,033,791 |
|
| 45 | % |
Total financial services products |
|
| 23,241,525 |
|
|
| 16,090,465 |
|
| 44 | % |
|
|
|
|
|
|
| |||||
Financial Services revenue per product |
| $ | 90 |
|
| $ | 104 |
|
| (13 | )% |
| ____________________ | ||
(1) | Includes checking and savings accounts held at SoFi Bank, and cash management accounts. | |
(2) | Beginning in the first quarter of 2026, we updated our SoFi Invest product metric to reflect four products. Prior to this, our SoFi Invest service was composed of two products, self-directed accounts and robo-advisory accounts. Self-directed accounts were previously referred to as active investing accounts. The impact to prior periods was determined to be immaterial, and prior periods were not recast. Beginning in the third quarter of 2026, we further updated our SoFi Invest product metric to reflect two additional products. The two new products, systematic taxable accounts and systematic IRA accounts, reflect our acquisition of Composer, through which members create and deploy systematic portfolio strategies in separate brokerage accounts. The impact to prior periods was determined to be immaterial, and prior periods were not recast. | |
(3) | Beginning in the second quarter of 2026, we updated our Financial Services products to include (i) SoFi Plus, which we relaunched during the quarter with significantly enhanced benefits, while fully transitioning the product to a paid subscription model; and (ii) Smart Card, our secured card (presented above within Credit Card). Beginning in the third quarter of 2026, we updated these products to include Credit Card with Personal Loan Rollover, which is a product that allows members to consolidate their credit card balances to SoFi for a period of time, after which any remaining balance automatically converts to a personal loan. The impact to prior periods for each of these products was determined to be immaterial, and prior periods were not recast. | |
(4) | Limited to loans wherein we provide third party fulfillment services as part of our Loan Platform Business. | |
(5) | During the fourth quarter of 2025, we returned to crypto investing with the launch of SoFi Crypto. | |
Technology Platform Segment Results
Technology Platform segment net revenue of $87.4 million for the third quarter of 2026 increased 3% from the prior quarter. Compared to the prior year period, segment revenue decreased 24%. This includes the impact from a large client which fully transitioned off the platform prior to December 31, 2025. Excluding that impact, segment revenue increased 18% from the prior year. Contribution profit of $14.2 million reflected a contribution margin of 16%.
Technology Platform – Segment Results of Operations | ||||||||||||||||||||||
|
|
Three Months Ended
|
|
|
|
Nine Months Ended
|
|
| ||||||||||||||
($ in thousands) |
| 2026 |
| 2025 |
| % Change |
| 2026 |
| 2025 |
| % Change | ||||||||||
Net interest income |
| $ | 1,030 |
|
| $ | 432 |
|
| 138 | % |
| $ | 2,407 |
|
| $ | 1,111 |
|
| 117 | % |
Noninterest income |
|
| 86,338 |
|
|
| 114,146 |
|
| (24 | )% |
|
| 244,552 |
|
|
| 326,727 |
|
| (25 | )% |
Total net revenue – Technology Platform |
|
| 87,368 |
|
|
| 114,578 |
|
| (24 | )% |
|
| 246,959 |
|
|
| 327,838 |
|
| (25 | )% |
Directly attributable expenses |
|
| (73,165 | ) |
|
| (82,207 | ) |
| (11 | )% |
|
| (208,985 | ) |
|
| (231,359 | ) |
| (10 | )% |
Contribution profit |
| $ | 14,203 |
|
| $ | 32,371 |
|
| (56 | )% |
| $ | 37,974 |
|
| $ | 96,479 |
|
| (61 | )% |
Contribution margin – Technology Platform(1) |
|
| 16 | % |
|
| 28 | % |
|
|
|
| 15 | % |
|
| 29 | % |
|
| ||
| ____________________ | ||
(1) | Contribution margin is defined for each of our reportable segments as contribution profit divided by net revenue. | |
Technology Platform-enabled accounts increased 6 million from the prior quarter. Technology Platform-enabled accounts decreased 11% year-over-year to 140 million.
Technology Platform |
| September 30, |
|
| |||||
|
| 2026 |
| 2025 |
| % Change | |||
Total accounts |
| 140,440,864 |
|
| 157,859,670 |
|
| (11 | )% |
Lending Segment Results
For the third quarter of 2026, Lending segment GAAP net revenue of $821.3 million increased 66% from the prior year period, while adjusted net revenue for the segment of $807.4 million increased 68% from the prior year period. Lending GAAP revenue per product was $958 compared to $801 in the prior year period. Lending adjusted revenue per product was $942 compared to $782 in the prior year period, driven by growth in personal loan originations.
Lending segment performance in the third quarter was driven by net interest income, which rose 57% year-over-year. The balance of the growth was primarily driven from loan origination fees which increased 158% from the prior year.
Lending segment third quarter contribution profit of $454.9 million was up 74% from $261.6 million in the corresponding prior-year period. Lending segment adjusted contribution margin was strong at 56%. This strong performance reflects our ability to capitalize on continued strong demand for our lending products.
Lending – Segment Results of Operations | ||||||||||||||||||||||
|
|
Three Months Ended
|
|
|
|
Nine Months Ended
|
|
| ||||||||||||||
($ in thousands) |
| 2026 |
| 2025 |
| % Change |
| 2026 |
| 2025 |
| % Change | ||||||||||
Net interest income |
| $ | 670,230 |
|
| $ | 427,973 |
|
| 57 | % |
| $ | 1,743,759 |
|
| $ | 1,161,269 |
|
| 50 | % |
Noninterest income |
|
| 151,115 |
|
|
| 65,409 |
|
| 131 | % |
|
| 444,804 |
|
|
| 188,998 |
|
| 135 | % |
Total net revenue – Lending |
|
| 821,345 |
|
|
| 493,382 |
|
| 66 | % |
|
| 2,188,563 |
|
|
| 1,350,267 |
|
| 62 | % |
Servicing rights – change in valuation inputs or assumptions |
|
| (13,952 | ) |
|
| (11,989 | ) |
| 16 | % |
|
| (40,257 | ) |
|
| (9,789 | ) |
| 311 | % |
Residual interests classified as debt – change in valuation inputs or assumptions |
|
| (23 | ) |
|
| 15 |
|
| (253 | )% |
|
| 20 |
|
|
| 62 |
|
| (68 | )% |
Directly attributable expenses |
|
| (352,436 | ) |
|
| (219,808 | ) |
| 60 | % |
|
| (911,973 | ) |
|
| (595,295 | ) |
| 53 | % |
Contribution profit – Lending |
| $ | 454,934 |
|
| $ | 261,600 |
|
| 74 | % |
| $ | 1,236,353 |
|
| $ | 745,245 |
|
| 66 | % |
Contribution margin – Lending(1) |
|
| 55 | % |
|
| 53 | % |
|
|
|
| 56 | % |
|
| 55 | % |
|
| ||
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Adjusted net revenue – Lending (non-GAAP)(2) |
| $ | 807,370 |
|
| $ | 481,408 |
|
| 68 | % |
| $ | 2,148,326 |
|
| $ | 1,340,540 |
|
| 60 | % |
Adjusted contribution margin – Lending (non-GAAP)(2) |
|
| 56 | % |
|
| 54 | % |
|
|
|
| 58 | % |
|
| 56 | % |
|
| ||
| ____________________ | ||
(1) | Contribution margin is defined for each of our reportable segments as contribution profit divided by net revenue. | |
(2) | For more information and a reconciliation of these non-GAAP financial measures to the most comparable GAAP measure, see “Non-GAAP Financial Measures” and Table 2 to the “Financial Tables” herein. | |
Lending – Loans At Fair Value |
|
|
|
|
|
|
|
|
|
|
|
|
| |||||||
($ in thousands) | Personal Loans |
| Student Loans |
| Home Loans |
| Small Business Loans |
| Total | |||||||||||
September 30, 2026 |
|
|
|
|
|
|
|
|
| |||||||||||
Unpaid principal | $ | 30,902,941 |
|
| $ | 18,067,482 |
|
| $ | 1,777,471 |
|
| $ | 11,481 |
|
| $ | 50,759,375 |
| |
Accumulated interest |
| 213,783 |
|
|
| 102,620 |
|
|
| 8,102 |
|
|
| 69 |
|
|
| 324,574 |
| |
Cumulative fair value adjustments(1) |
| 1,023,785 |
|
|
| 348,553 |
|
|
| 26,721 |
|
|
| 440 |
|
|
| 1,399,499 |
| |
Total fair value of loans(2)(3) | $ | 32,140,509 |
|
| $ | 18,518,655 |
|
| $ | 1,812,294 |
|
| $ | 11,990 |
|
| $ | 52,483,448 |
| |
June 30, 2026 |
|
|
|
|
|
|
|
|
| |||||||||||
Unpaid principal | $ | 26,101,759 |
|
| $ | 16,134,415 |
|
| $ | 2,067,122 |
|
| $ | — |
|
| $ | 44,303,296 |
| |
Accumulated interest |
| 180,704 |
|
|
| 81,501 |
|
|
| 9,450 |
|
|
| — |
|
|
| 271,655 |
| |
Cumulative fair value adjustments(1) |
| 1,222,827 |
|
|
| 704,648 |
|
|
| 99,586 |
|
|
| — |
|
|
| 2,027,061 |
| |
Total fair value of loans(2)(3) | $ | 27,505,290 |
|
| $ | 16,920,564 |
|
| $ | 2,176,158 |
|
| $ | — |
|
| $ | 46,602,012 |
| |
| ____________________ | ||
(1) | During the three months ended September 30, 2026, the cumulative fair value adjustments for personal loans were impacted by a higher unpaid principal balance, offset by a higher weighted average conditional prepayment rate, a higher weighted average discount rate, lower weighted average coupon, and a higher weighted average annual default rate. The higher discount rate was primarily driven by a 76 basis point increase in benchmark rates. The cumulative fair value adjustments for student loans were impacted by a higher unpaid principal balance, a lower weighted average conditional prepayment rate, a higher weighted average coupon, offset by a higher weighted average discount rate, and higher weighted average default rate. The higher discount rate was primarily driven by a 90 basis point increase in benchmark rates. | |
(2) | Each component of the fair value of loans is impacted by charge-offs during the period. Our fair value assumption for annual default rate incorporates fair value markdowns on loans beginning when they are 10 days or more delinquent, with additional markdowns at 30, 60 and 90 days past due. | |
(3) | Student loans are classified as loans held for investment, and personal loans and home loans are classified as loans held for sale. | |
The following table summarizes the significant inputs to the fair value model for personal and student loans:
| Personal Loans |
| Student Loans | |||||||||
|
September 30,
|
|
June 30,
|
|
September 30,
|
|
June 30,
| |||||
Weighted average coupon rate(1) | 12.78 | % |
| 12.89 | % |
| 6.01 | % |
| 5.89 | % | |
Weighted average annual default rate | 5.10 | % |
| 4.77 | % |
| 0.89 | % |
| 0.73 | % | |
Weighted average conditional prepayment rate | 25.87 | % |
| 25.77 | % |
| 10.17 | % |
| 10.99 | % | |
Weighted average discount rate | 5.56 | % |
| 4.97 | % |
| 5.11 | % |
| 4.29 | % | |
Benchmark rate(2) | 4.75 | % |
| 3.99 | % |
| 4.80 | % |
| 3.90 | % | |
| ____________________ | ||
(1) | Represents the average coupon rate on loans held on balance sheet, weighted by unpaid principal balance outstanding at the balance sheet date. | |
(2) | Corresponds with two-year SOFR for personal loans and four-year SOFR for student loans. | |
For the third quarter of 2026, record origination volume of $16.9 billion increased 71% year-over-year. This was a result of continued strong member demand for personal loans, student loans and home loans as well as strong demand from capital markets partners.
Record personal loan originations of $12.6 billion in the third quarter of 2026 were up 69% year-over-year, inclusive of $3.6 billion originated on behalf of third parties through our Loan Platform Business. SoFi's multichannel strategy continues to allow us to serve more members and provide revenue diversification.
Third quarter student loan volume of $2.9 billion was up 96% year-over-year. This marked the highest quarter of student loan originations in SoFi's history.
Home loan volume was $1.4 billion, an increase of 44% year-over-year. Home equity loan originations were strong during the third quarter, accounting for approximately 40% of total home loan volume.
Contacts
Investors:
SoFi Investor Relations
IR@sofi.com
Media:
SoFi Media Relations
PR@sofi.com
Read full story here
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 |
