SoFi Matches The Whisper But Accelerates Revenue And Raises Every Guidance Line, While The Stock Trades Near Its Lows
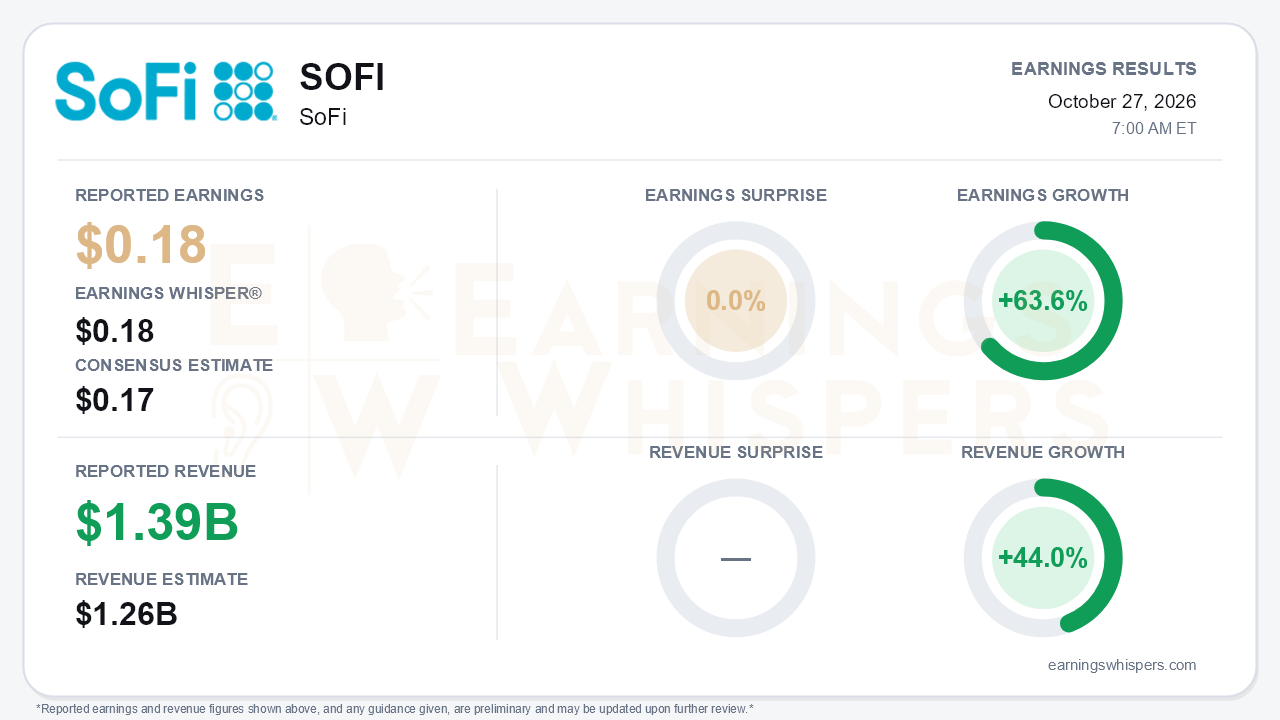
SoFi's third-quarter earnings landed where the most informed expectations sat. Earnings of $0.18 per share matched the Earnings Whisper number and edged past the $0.17 consensus, which leaves the 0.0% surprise looking in line. Revenue was the real story. It came in at $1.385 billion, 9.9% above the $1.26 billion consensus and up 44.0% year over year, while earnings grew 63.6%. Adjusted net revenue growth has now accelerated for three straight quarters, from 37% in the fourth quarter of 2025 to 41%, 40% and now 44%. SoFi also raised full-year 2026 guidance on revenue, adjusted EBITDA, net income and EPS, and introduced 2027 targets a quarter early. That is the central tension: the business is accelerating, but the stock entered the report near a 52-week low.
The quality of the quarter is better than a matched EPS figure suggests. Pretax income more than doubled to $317.8 million from $148.6 million. GAAP net growth was held back because income tax expense jumped to $76.8 million from $9.2 million. Adjusted EBITDA rose 70% to $469.8 million, and the margin widened to 34% from 30% in the second quarter. Net interest margin expanded to 6.14%, the fourth consecutive sequential gain, as deposits funded 90% of liabilities. Still, the growth is lending-heavy:
- Lending adjusted revenue rose 68% on record originations of $16.9 billion.
- Loan origination fees climbed to $270.9 million from $105 million.
- Financial Services revenue grew a more modest 25%.
- Financial Services contribution margin slipped to 50% from 54%.
- Financial Services revenue per product fell to $90 from $104 a year ago, though it improved from $88 sequentially.
The 42% fee-based revenue mix is real, but much of it reflects origination fees rather than the diversified platform model management emphasizes.
The call reinforced an improving operating picture:
- The personal loan risk-adjusted margin rose to about 7.6% from 6.1% in the second quarter, as more than half of new personal loans now carry origination fees.
- All-in personal loan net charge-offs improved to 3.4%, from 3.7% in the second quarter and 4.4% in the first.
- The Loan Platform Business recovered to $3.8 billion of originations, added two partners and transferred its first small-business and home equity loans, with fourth-quarter volume pacing higher.
- Members grew 35% to 17.1 million on a record 1.2 million additions.
- Products per member rose to 1.56.
Management's tone was its most confident of the year. Management said it has 'as much confidence in a high rate environment as low.'
The forward setup gives both camps material. The 2027 outlook calls for about $6.4 billion of adjusted net revenue, $1.28 billion of adjusted net income and $0.90 of EPS. Management said the plan is fully funded organically, with roughly $29 billion of excess risk-weighted asset capacity. That outlook is ambitious, but 27% growth is a clear deceleration from roughly 40% in 2026 and sits below the prior medium-term trajectory of at least 30%.
Bears have legitimate ammunition:
- Rates moved against the plan, from two expected cuts to one hike with two more anticipated.
- Fair value marks fell 140 to 330 basis points across loan types, an impact of more than $800 million that hedges only partly offset.
- The model's personal loan default assumption rose to 5.10% from 4.77%.
- Credit card charge-offs rose to 7.77% from 6.55%.
- The total capital ratio has fallen from 21% to 17% in two quarters.
- The Technology Platform segment is tracking below its full-year guide, and fraud slowed SoFi Plus additions.
- Management expects personal loan growth to moderate and revenue per product to drift lower over time.
- A higher tax rate is absorbing operating gains, which is why the 2026 EPS guide rose only a penny despite a much larger revenue raise.
The market had been treating the stock harshly before the report. Shares closed at $14.46 ahead of the release, down 6.7% from the opening price after the July report. They traded 19.8% below the 200-day moving average and 25.8% below the late-August inter-earnings high of $19.50. That left the stock just 4.3% above the 52-week low of $13.86 set on October 15. Investor sentiment improved only slightly, to -0.499 from -0.514, and remains firmly negative. The Earnings Whispers trend signals are split: sequential growth and momentum are positive, while price and AVWAP trends remain negative.
The bottom line is that SoFi delivered accelerating revenue, record profitability, improving credit and a raised outlook. Investors had priced in skepticism, not this level of execution. The skepticism is not baseless. The growth engine leans heavily on lending fees, rate-driven valuation marks and a shrinking capital cushion, and 2027 implies a clear slowdown. The report shifts the burden of proof toward the bears, but rate and credit risk will determine whether a deeply discounted stock rerates.
Read our earnings preview for SoFi: https://www.earningswhispers.com/article/SOFI/20727
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 32 min | |
| 2 hours | |
| 2 hours | |
| 3 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 5 hours | |
| 5 hours | |
| 5 hours | |
| 5 hours | |
| 6 hours | |
| 7 hours |
SoFi Earnings Top Views. Fintech Hikes 2026 Revenue Guidance.
SOFI +13.97%
Investor's Business Daily
|
| 8 hours | |
| 8 hours |
