PayPal Beats And Raises Again On Cost Cuts, But A Revenue Miss Shows The Top Line Is Still Stuck
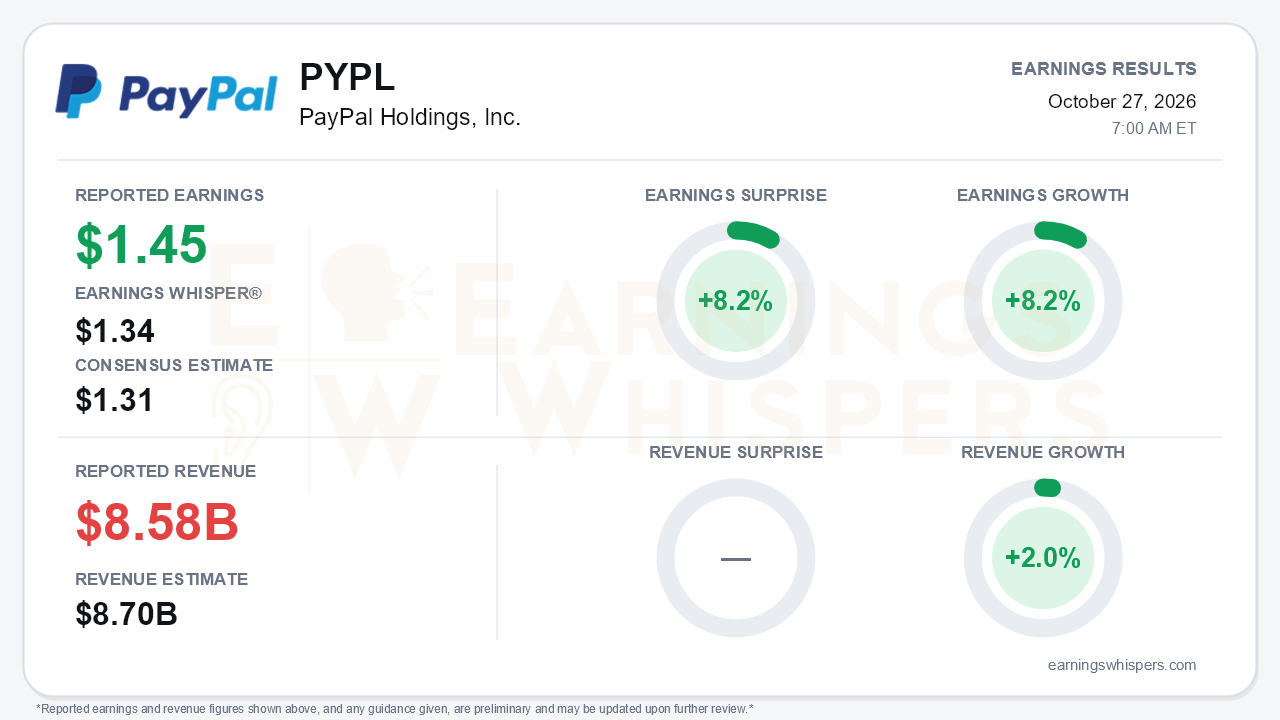
PayPal delivered another quarter in which cost discipline did the heavy lifting. Third-quarter earnings came in at $1.45 per share, beating the $1.31 consensus by 8.2% and clearing the $1.34 Earnings Whisper number. Earnings grew 8.2% year over year. Revenue told a different story. Sales of $8.584 billion rose just 2.0% and missed the $8.70 billion consensus by 1.3%. Management raised full-year guidance for the second straight quarter, and the company says that outlook sits above estimates. That is the central tension: PayPal is becoming a more profitable, more cash-generative company without yet proving it can grow faster.
The quality of the beat deserves scrutiny because it came almost entirely from the expense line. Transaction margin dollars grew only 2%, matching revenue growth. Non-transaction operating expenses rose just 1%, compared with 8% in the first quarter. Management now expects full-year non-transaction OpEx growth in the mid-single digits, down from the 7-8% it guided in the second quarter. The gross cost-savings run rate exiting 2026 was raised to more than $700 million, up from roughly $400 million identified last quarter. That effort includes cutting more than 2,000 jobs and removing three organizational layers. The cash picture is strong:
- Adjusted free cash flow reached $2.0 billion, up from $1.8 billion in the second quarter.
- Buybacks totaled $1.5 billion.
- Full-year non-GAAP EPS guidance rose to about $5.60 from $5.38. Earlier in the year, management had guided to a decline in the low single digits or a slight gain.
- Full-year transaction margin dollar guidance moved up only modestly, to about $15.7 billion from $15.6 billion.
- The adjusted free cash flow floor rose to at least $6.5 billion from at least $6 billion.
The operating trends beneath the headline are mixed. Branded checkout, the franchise that matters most to the long-term multiple, has grown just 1-2% for four consecutive quarters. Management guided the fourth quarter to the same range despite easier comparisons. The removal of the EU de minimis exemption is costing roughly 70 basis points of global branded checkout growth, and that drag persists through the fourth quarter. International revenue fell about 4% on an FX-neutral basis, and the UK remains difficult. Growth also cooled in segments that had been offsetting the core. PSP volume growth slowed to 8% from 13% in the second quarter. Venmo TPV growth was described only as double-digit, after 14% last quarter. The bright spots are real but still small relative to the whole:
- Financial services now exceed 20% of transaction margin dollars and are growing double digits.
- Buy now, pay later grew 25%.
- Pay with Venmo grew 43%.
- Venmo debit monthly active accounts reached 6.7 million, up 55%.
- The PSP value-added services attach rate rose to 6% from 5%.
The forward catalysts are more substantive than in recent quarters. PayPal launched buy now, pay later with Amazon in Germany and Austria and added American Eagle, Aerie and Dick's Sporting Goods. It relaunched the Venmo credit card, citing four- to five-fold upside in Venmo revenue per account. It is also collaborating with Meta and other AI companies on agentic commerce. Management introduced a medium-term algorithm of sustainable mid-single-digit transaction margin dollar growth and solid double-digit EPS growth. The board explicitly rejected strategic alternatives and offers in favor of the standalone plan, and selective M&A is now framed as a value-creation lever. Bears have legitimate ammunition, however:
- Fourth-quarter transaction margin dollar growth is guided only slightly positive.
- 2027 is framed as an investment year, with EPS growth targeted merely similar to 2026.
- Management cautioned against run-rating second-half OpEx, so the current margin tailwind should not be extrapolated.
- Rejecting offers leaves execution risk squarely on the transformation and does not fully remove the M&A overhang.
Investor expectations were subdued heading into the report. Earnings Whispers sentiment remained negative, improving only slightly from -0.389 to -0.357. As of the day before the release, shares were $54.99, down 3.1% from the $56.76 open after the July report. The stock sat about 9.9% above its 200-day moving average of $50.03 but 12.3% below its August 20 inter-earnings high of $62.73. It was 8.2% above the September 10 low of $50.80, leaving it in the middle of the quarter's range after giving back a summer rally. The Earnings Whispers trend signals are uniformly positive, including sequential growth and momentum. That backdrop suggests the market had begun to give credit for the earnings trajectory even as sentiment stayed skeptical.
The bottom line is that PayPal executed well on what it controls. It delivered a clean EPS beat, a second guidance raise, larger cost savings, stronger free cash flow and a clearer standalone strategy. The revenue miss, flat branded checkout and slowing PSP and Venmo growth show that the top-line reacceleration investors ultimately need has not arrived. With 2027 framed as a reinvestment year, the story increasingly depends on whether buy now, pay later, Venmo monetization and agentic commerce can lift growth before the cost levers run out.
Read our earnings preview for PayPal Holdings, Inc.: https://www.earningswhispers.com/article/PYPL/20720
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 5 hours | |
| 5 hours | |
| 7 hours | |
| 7 hours | |
| 7 hours | |
| 8 hours | |
| 8 hours | |
| 8 hours | |
| 8 hours | |
| 8 hours | |
| 9 hours | |
| 9 hours |
