Corning Accelerates To 19% Core Growth And Guides Above Estimates As Optical Offsets Solar And Glass Drag
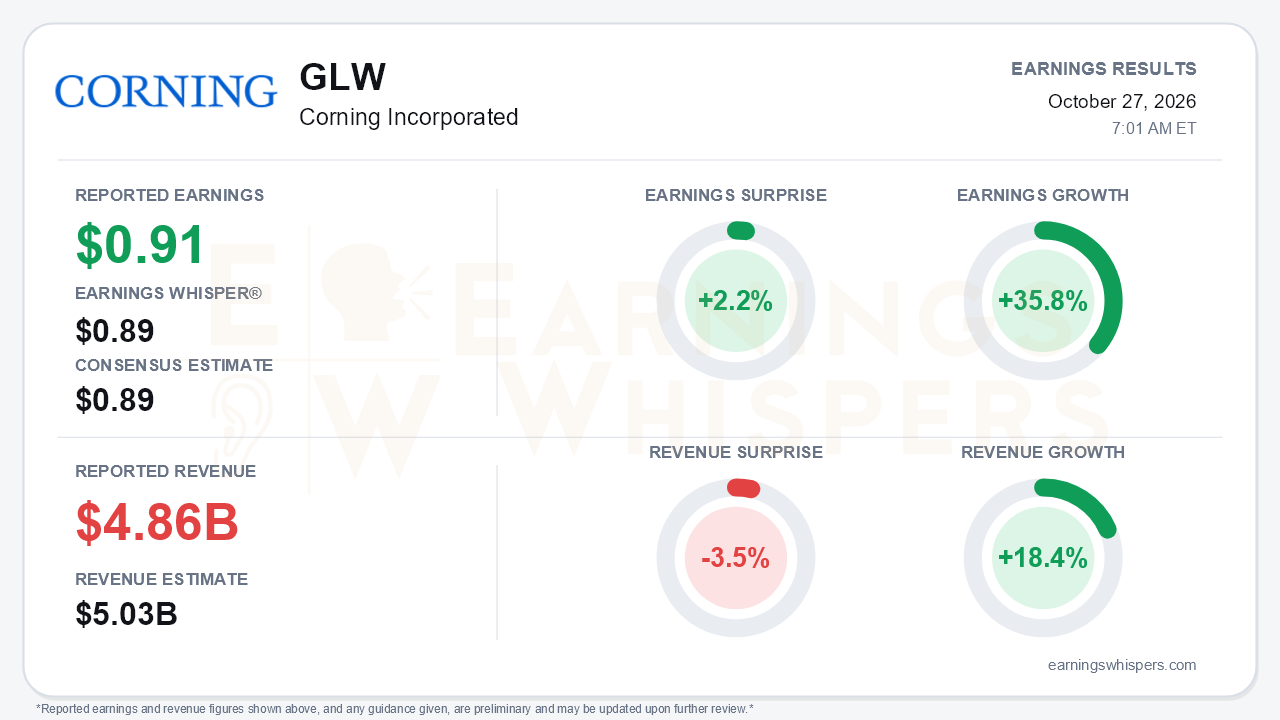
Corning delivered an acceleration quarter that shares have not yet reflected. Third-quarter core EPS of $0.91 beat the $0.89 consensus and Earnings Whisper number by 2.2%, and earnings grew 35.8% year over year. Core sales rose 19% to $5.08 billion, the fastest growth since the Springboard plan launched, up from 18% in the first quarter and 17% in the second. Fourth-quarter guidance calls for core sales of $5.2 billion to $5.3 billion and core EPS of $0.96 to $1.00, both up roughly 19% and 36%, and above estimates. The central tension is that Optical Communications is now carrying the entire growth story. Solar and Glass Innovations, the two businesses meant to broaden it, both lost ground against expectations this quarter.
The headline revenue figures conflict and need explaining. On the normalized basis, revenue of $4.855 billion, which is GAAP sales, missed the $5.03 billion consensus by 3.5% while still growing 18.4%. Core sales of $5.08 billion, the figure Corning manages to and guides on, cleared the company's own $4.9 billion to $5.0 billion outlook. The gap reflects Corning's core adjustments, chiefly hedged currency exposures, so the miss appears to stem more from that GAAP/core difference than from weak demand. The quality of the earnings beat deserves some scrutiny, though. Part of the core outperformance came from lower corporate expense, and elevated variable compensation is affecting corporate costs. Even so, the margin progression is hard to dismiss:
- Core gross margin rose to 40.5%, from 39.6% in the second quarter and 39.1% in the first.
- Core operating margin climbed to 22.7%, from 20.9% and 20.2%.
- ROIC reached 16.7%.
- GAAP EPS of $0.78 rose 56%.
Optical is where the business is changing fastest. Segment sales jumped 44% to $2.38 billion, accelerating from 32% growth in the second quarter, and segment net income surged 80% to a record $532 million. Within that:
- Enterprise Networks grew 84%, up from 65%, and its run rate is now about $6 billion.
- Gen AI product sales more than doubled, which management said outpaced GPU unit growth.
- Carrier growth was modest but improved to 4% from 1%.
- New long-term agreements with Zayo, Verizon and AT&T pushed the data center interconnect opportunity above the prior $1 billion target.
Management signaled that optical margins can climb further. With Q3 annualized sales of $20.3 billion, Corning reached its $20 billion run-rate goal a quarter early, and the fourth-quarter guide implies roughly $21 billion.
The weaker parts of the portfolio are real, and they give bears legitimate ammunition.
- **Solar:** Sales grew 37% to $436 million, but the wafer and module ramp is slower than anticipated. The segment lost $7 million again, and the profit improvement expected after the second-quarter call is now framed as gradual through 2027. The Section 232 trade action should help pricing and demand for U.S.-made product, but the timeline has slipped.
- **Glass Innovations:** Sales fell 3% and net income fell 10%, a reversal from 9% profit growth in the second quarter. Memory-driven weakness in notebooks and handhelds and a weaker yen were the main pressures. A display glass price increase beginning in the fourth quarter is intended to offset part of that pressure.
- **Other items:** Life Sciences losses widened, yen hedge coverage slipped to 94% from 98%, and a $2 billion at-the-market equity shelf was filed, which management framed as housekeeping. The promised new operating margin target has not yet appeared.
Cash generation adds credibility to the capacity build. Adjusted free cash flow was $661 million for the quarter and $2.27 billion year to date, even with heavy capital spending. That figure was aided by $639 million in net customer deposits as the prepayment model extends into optical. Customers are effectively co-funding expansion, which reduces the risk that new capacity outruns demand. That risk is central to the investor debate over how durable AI spending is and how it will be financed.
The market setup is more complicated than the surprise implies. Shares spiked to an inter-earnings high of $176.94 in mid-August, then gave back most of the move, closing at $127.74 ahead of the report. That is just 4.9% above the open following the July release, 27.8% below the quarter high, and 17.3% below the $154.53 200-day moving average. Investor sentiment improved from modestly negative to essentially neutral, a meaningful but not dramatic shift. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP trends remain negative.
The bottom line is that Corning's fundamentals improved this quarter while its stock deteriorated. Accelerating optical growth, expanding margins, deposit-backed capacity and guidance above estimates give the Springboard story more substance than it had three months ago. The near-term debate now hinges on whether optical's momentum can outrun a delayed solar ramp, soft consumer glass, and market skepticism about how long AI demand lasts.
Read our earnings preview for Corning Incorporated: https://www.earningswhispers.com/article/GLW/20696
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 3 hours | |
| 4 hours | |
| 4 hours | |
| 5 hours | |
| 5 hours | |
| 6 hours | |
| 7 hours | |
| 7 hours | |
| 8 hours | |
| 8 hours | |
| 8 hours | |
| 10 hours | |
| 10 hours | |
| Oct-22 |
