Centene Clears A Low Bar And Raises Guidance A Third Time, But Margin Recovery Is Running Ahead Of A Shrinking Membership Base
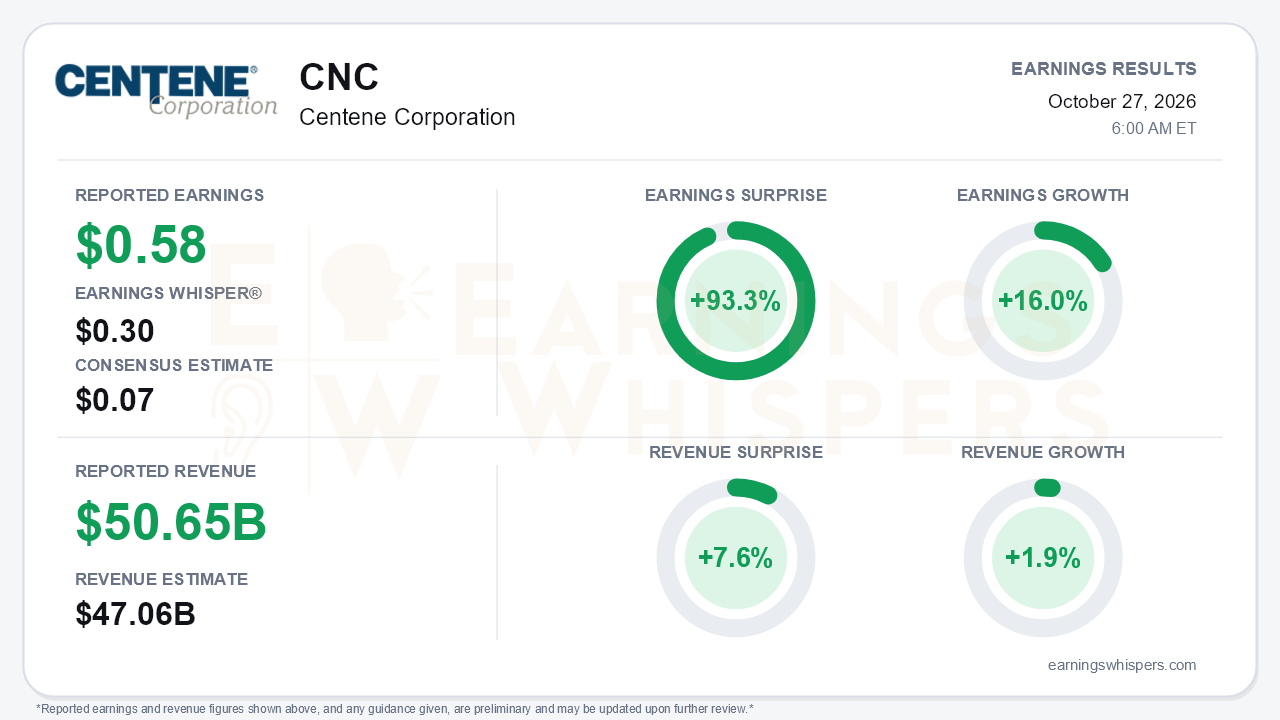
Centene delivered another margin-driven beat and its third straight guidance raise. Adjusted EPS of $0.58 cleared the $0.07 consensus by 93.3% and comfortably topped the $0.30 Earnings Whisper. Earnings grew 16.0% from a year ago. Revenue of $50.647 billion beat the $47.06 billion consensus by 7.6% and grew 1.9%. Management lifted the 2026 adjusted EPS floor to more than $5.20, up from more than $4.80 in July and more than $3.00 at the start of the year. The central tension is that Centene is earning more on a smaller book. Total at-risk membership fell to 25.7 million from 28.0 million, and the profit recovery is outrunning the contraction for now.
The quality of the beat deserves some scrutiny. Premium and service revenues rose only 0.5%, to $45.1 billion. Much of the headline revenue growth came from premium tax revenue, which rose to $5.5 billion from $4.8 billion and is largely pass-through. On a GAAP basis, Centene lost $0.14 per share. That is a vast improvement from the $13.50 loss a year ago, when a $6.7 billion goodwill impairment hit results. This quarter carried $276 million of severance and $35 million of vendor costs tied to enterprise optimization. Headcount fell to 53,900 from 59,800 in a single quarter, which shows how aggressively costs are being cut. The consolidated health benefits ratio of 92.7% was flat year over year. However, the prior-year figure benefited from a premium deficiency reserve release, so the underlying improvement is better than the flat number suggests. The adjusted SG&A ratio fell to 6.5% from 7.0%, helped by fewer high-cost Marketplace members and more low-cost PDP members.
The call showed improvement across nearly every segment's margin. Medicare Advantage is now expected to break even in 2026, a year ahead of the 2027 target held through the second quarter. PDP pre-tax margin guidance rose to the mid-to-high 3s, from 2% at the start of the year. Marketplace margin moved to roughly 5%, the top of its range, up from about 3% in the first quarter and a loss in 2025. That came even after reserve bolstering for No Surprises Act dispute-resolution abuse and program-integrity adjustments. Medicaid's benefits ratio improved 30 basis points sequentially to 93.6%. Management said rates versus acuity show "more positive signals than negative, probably for the first time in a long while." States are building work-requirement acuity adjustments into January 2027 draft rates. Management also offered an early 2027 framework. It calls for EPS growth from both the $5.20 guide and a roughly $4.70 jump-off that excludes $0.50 of non-recurring items.
Bears still have legitimate ammunition, and most of it concerns volume and durability:
- Medicaid membership is 11.9 million, down 5% year to date. The full-year decline is still expected to reach 8% to 9%, so a larger fourth-quarter step-down and the related acuity shift are still ahead.
- Work requirements and the removal of California's UIS population weigh on 2027.
- Marketplace enrollment is drifting toward about 3.2 million by year end, and management expects the exchange market to shrink again next year.
- PDP margin is expected to reset to 2% to 3% in initial 2027 guidance.
- Medicare Advantage membership will decline as the footprint narrows.
- Only about 42% of members sit in plans rated 3.5 stars or higher for 2028.
- Operating cash flow was negative $3.7 billion on pass-through timing, and corporate cash fell to $175 million from $715 million.
- Year-to-date adjusted EPS of $6.45 against a full-year floor above $5.20 implies a seasonally weak fourth quarter.
The balance sheet is improving. Debt was $15.5 billion at quarter end, and the call cited $15.0 billion after October's full redemption of the 2027 notes, down from $18.5 billion at the end of 2024. Debt-to-capitalization fell to 41.1%. Other developments include a CFO transition and a planned 18-to-24-month exit from roughly $4 billion of Health Net commercial group business.
The market had already priced in much of the recovery. Shares closed at $68.03 the day before the report, up 14.3% from the open after the July release and 24% above the 200-day moving average. They sat 6.2% below a 52-week high of $72.50 set October 22, so the stock entered earnings near the top of its range rather than washed out. Investor sentiment remained positive but edged lower, from 0.194 to 0.176, a modest cooling rather than a shift in tone. Most Earnings Whispers trend signals are positive, with sequential growth, momentum and AVWAP readings favorable, while price trend is neutral.
The bottom line is that Centene's repricing and cost work is producing earnings faster than management itself expected. The 2026 guide has risen at every turn, and 2027 is now framed as a growth year. However, the earnings recovery rests on a membership base that is still shrinking, with acuity, exchange contraction, Star ratings and a PDP margin reset as the open questions. With the stock already well off its lows, the next leg depends on whether margin gains can keep outpacing membership losses into 2027.
Read our earnings preview for Centene Corporation: https://www.earningswhispers.com/article/CNC/20687
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 4 hours | |
| 8 hours | |
| 8 hours | |
| 9 hours | |
| 9 hours | |
| 9 hours | |
| 10 hours | |
| Oct-26 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 |
