S&P Global Beats And Raises Again, But The Capital IQ Strategic Review And A Ratings Slowdown Complicate The Story
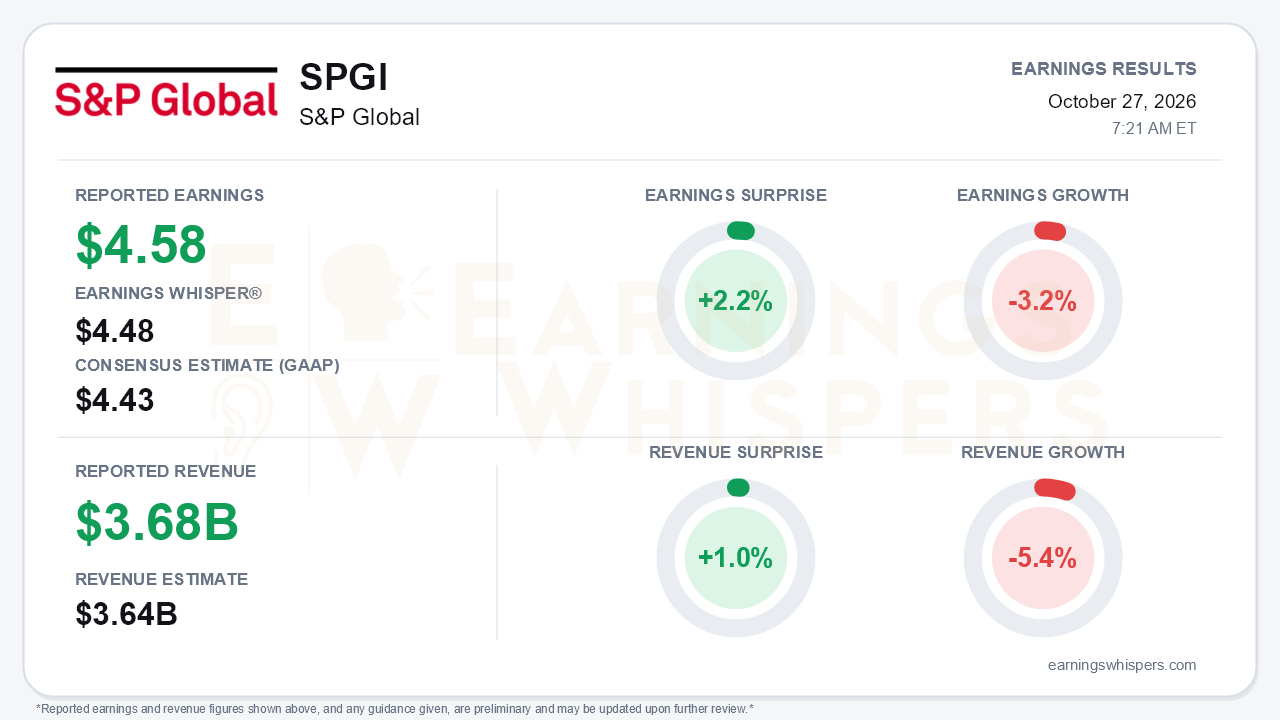
S&P Global (NYSE: SPGI) delivered a modest beat and a meaningful guidance raise for the third quarter, and paired them with a portfolio move that may matter more than either. The company reported earnings of $4.58 per share on revenue of $3.678 billion. That topped the $4.43 consensus estimate by 2.2% and edged past the $4.48 Earnings Whisper number, while revenue beat the $3.64 billion consensus by 1.0%. On the normalized year-over-year comparison, however, earnings fell 3.2% and revenue declined 5.4%. Alongside the results, S&P Global announced a strategic review of Capital IQ and associated data businesses that could lead to a separation. That review, not the size of the beat, is the central development.
The quality of the quarter needs some interpretation because the headline growth figures and management's operating metrics point in opposite directions. On the call, management described 7% organic revenue growth, adjusted margin expansion of 60 basis points to 53.5% (120 basis points excluding Astra), and a 9% rise in adjusted EPS. The normalized figures show reported declines. The source material does not fully reconcile the two, but the guidance history offers a clue: the prior-quarter outlook was framed excluding the mobility business, which suggests portfolio changes are distorting the reported comparisons. Investors should also note the basis difference. The supplied consensus is on a GAAP basis, while management's 9% growth figure refers to adjusted EPS.
Beneath the headline, the operating picture improved across most of the business. Indices grew 20% for a 14th straight record quarter, with margin up 150 basis points to 71.9%. Market Intelligence accelerated to 7% from 6% in the second quarter. Its annual contract value growth rose to about 6.5%, and management said the sales-cycle elongation flagged last quarter has normalized. Energy rebounded to 6% growth from 3%, with renewals back to pre-Iran-war levels.
The guidance changes are the clearest sign of momentum. This was the second straight quarter of consolidated raises:
- Full-year organic constant-currency growth moved to 7.5-8.5% from 6-8%.
- Margin expansion guidance excluding Astra rose to 125-150 basis points, up from 50-75 basis points earlier in the year.
- Adjusted EPS guidance increased to $17.70-17.95 from $17.50-17.75.
- Indices guidance jumped to 17-18.5%.
- Ratings guidance moved to 6.5-8%.
No metrics were cut.
Ratings is where bears have legitimate ammunition. Segment growth slowed to 2% from 17% in the second quarter. Transaction revenue rose only 1%, and margin contracted roughly 130 basis points. Excluding hyperscalers, billed issuance grew only low single digits. Management expects fourth-quarter transaction revenue to decline slightly against tough comparisons, and its own research team forecasts slower issuance in 2027. Energy's acceleration also carries a caveat. The quarter benefited from one-time sales that may not recur, and full-year Energy guidance stays at 4.5-6% after an earlier cut. Meanwhile, roughly $2 billion of additional debt keeps leverage above the 2.0-2.5x target, even as buybacks track above $7 billion.
The forward catalyst list is unusually dense:
- The Capital IQ review covers Kensho Data & Platforms, including SNL and Visible Alpha. NDAs have been signed with multiple interested parties, and an update is targeted for the February call.
- The CBOE S&P 500 options license was extended through 2051 and is expected to add a couple of points to 2027 index growth.
- New opportunities include the Kalshi prediction-markets partnership, the OpenZeppelin and DataCenter Hawk acquisitions, and an AI data portal built on MCP tools. Management cited a 1.8x contract-value premium for AI customers in Market Intelligence.
The separation also carries real dis-synergy risk. Ratings analysts rely on Capital IQ, and Kensho's AI capabilities could leave with the divested perimeter.
The market setup heading into the report was firmer than investor sentiment. Earnings Whispers sentiment remained negative but improved modestly, rising from -0.359 to -0.311. The stock was more cautious in early October, falling to an inter-earnings low of $382.21 on October 2. It then rallied nearly 18% to $450.65, just 1.3% below the $456.78 quarterly high set on October 22. That leaves shares 7.6% above the open following the July report and about 4% above their 200-day moving average. Momentum and AVWAP trend readings are positive, while price trend is neutral. Because the stock rallied so sharply into the print, part of the good news may already be reflected in the price.
The bottom line is that S&P Global offered a credible beat-and-raise quarter. Indices, Market Intelligence and AI-driven products are carrying growth, and the margin trajectory keeps improving. But Ratings is decelerating sharply into a softer issuance outlook, and the reported year-over-year declines require reconciliation with management's organic figures. The Capital IQ review adds a new layer of execution risk to a stock trading near its recent highs, and its outcome now looms as the defining event before the February call.
Read our earnings preview for S&P Global: https://www.earningswhispers.com/article/SPGI/20728
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 2 hours | |
| 3 hours | |
| 4 hours | |
| 6 hours | |
| 6 hours | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 |
