Coca-Cola Beats And Raises For A Third Straight Quarter, But Shipment Timing, Mix Drag And A Tougher 2027 Complicate The Story
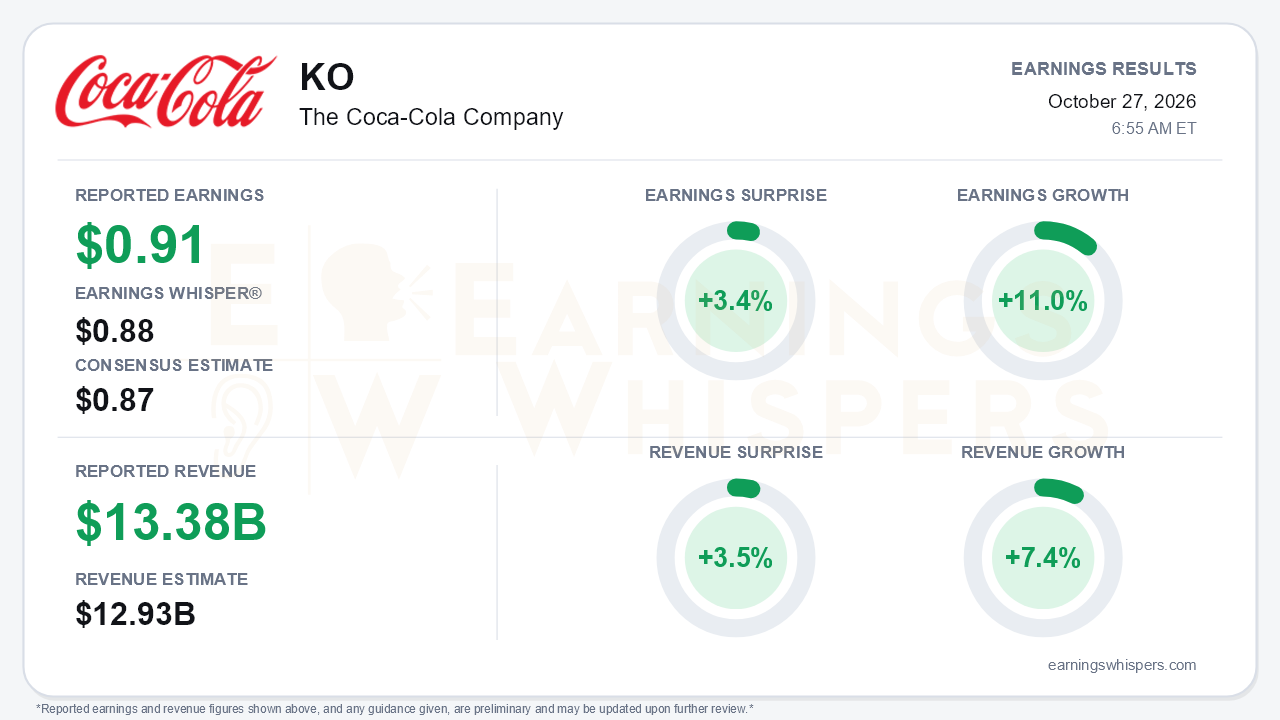
Coca-Cola delivered another beat-and-raise quarter. Comparable EPS of $0.91 topped the $0.87 consensus and the $0.88 Earnings Whisper number by 3.4%. Revenue of $13.38 billion beat the $12.93 billion estimate by 3.5%. Earnings grew 11.0% year over year and revenue rose 7.4%, the kind of growth a mature staples franchise rarely posts. Management raised full-year guidance for the third consecutive quarter. Comparable EPS growth is now expected to be at least 11%, up from 9% to 10% last quarter and 7% to 8% at the start of the year. The central tension is that the headline strength leans partly on factors that will not repeat or that reverse in the fourth quarter, while the 2027 setup is visibly harder.
The quality of the beat deserves scrutiny. Organic revenue grew 7%, but concentrate sales ran 2 points ahead of unit case volume because of shipment timing. Management now expects slight fourth-quarter destocking, with concentrate shipments trailing unit cases for the full year. Pricing also contributed less. Price/mix rose just 1%, as roughly 4 points of pricing were offset by about 3 points of unfavorable mix, versus 2% in each of the first two quarters. Full-year price/mix is tracking around 2%, one of the lowest levels in a decade. On the earnings line, a 2-point currency tailwind lifted EPS. Comparable currency-neutral operating income grew 8%, and comparable currency-neutral EPS grew 9%, both solid but less impressive than the 11% headline. GAAP EPS rose 8% to $0.93.
The real strength is volume and margin. Unit case volume grew 5%, matching the second quarter and well ahead of 3% in the first quarter and 1% in the fourth quarter of 2025. India, China, Mexico and Brazil led the gains, and Coca-Cola Zero Sugar grew 16%. Comparable gross margin expanded about 170 basis points, building on gains of roughly 120 basis points in Q2 after a 30-basis-point decline in Q1. Comparable operating margin rose to 32.9% from 31.9%, and the company extended its run of value share gains to 22 straight quarters. Latin America was the standout, with 16% organic growth and a 14% rise in comparable currency-neutral operating income. North America was the soft spot. Volume was flat after gains of 3% and 4% in the prior two quarters, which management attributed to July 4 timing, tough comparisons for finished goods such as Topo Chico and BodyArmor, and weak restaurant traffic. EMEA also lost value share, with losses in France and the United Kingdom outweighing gains in Nigeria and Morocco.
Beyond the guidance raise, management introduced several forward-looking developments. The free cash flow target rose to at least $13 billion from roughly $12.4 billion in the prior guidance; the call framed the increase against the original ~$12.2 billion target set in February. The company has already generated $11.4 billion year to date. Net leverage fell to 1.3x. Other catalysts include:
- the pending sale of the bottling operations in Africa, now expected to close in Q4 subject to regulatory approvals, which management described as margin- and return-accretive;
- a potential IPO of the India bottling operations;
- the ramp of fairlife capacity at the Webster plant.
Against those positives, the 2027 considerations are a clear headwind. The company expects an approximately 8% revenue headwind and 2% EPS headwind from divestitures, plus a slight currency headwind. Management also flagged difficult volume comparisons after a year helped by the World Cup and favorable weather. The lower 2026 tax rate of 19.7% includes benefits management does not expect to repeat, and the IRS litigation remains unresolved. Double-digit growth in above-the-line marketing is meant to set up a strong start to 2027, but it will also weigh on near-term operating leverage. The fourth quarter carries six fewer selling days as well.
The market setup is more complicated than the surprise implies. Investor sentiment slipped from mildly positive (0.09) to roughly neutral (-0.02), a modest cooling rather than a sharp reversal. Price action, however, was strong heading into the report. Shares rose from an October 5 low of $85.13 to a 52-week high of $95.37 on October 22 and closed the pre-report snapshot at $92.70. That price is 5.0% above the open following the July report and 13.5% above the 200-day moving average, putting the stock near the top of its inter-earnings range. Most Earnings Whispers trend readings are positive, though sequential growth is the exception. With much optimism apparently priced in, the cooler sentiment points to more skepticism about upside from here.
The bottom line is that Coca-Cola's volume, share and margin execution is genuinely strong, and three consecutive guidance raises give the growth story credibility. Bears still have legitimate ammunition. Part of the raise comes from currency and a lower tax rate, revenue benefited from shipment timing that will reverse, mix is eroding price realization, and 2027 brings divestiture, currency and comparison headwinds. With shares entering the report near their highs, the bar for continued outperformance is high.
Read our earnings preview for The Coca-Cola Company: https://www.earningswhispers.com/article/KO/20711
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 |
