UPS Beats And Raises Again, But A Narrowing Price-Cost Spread Tempers The Turnaround Story
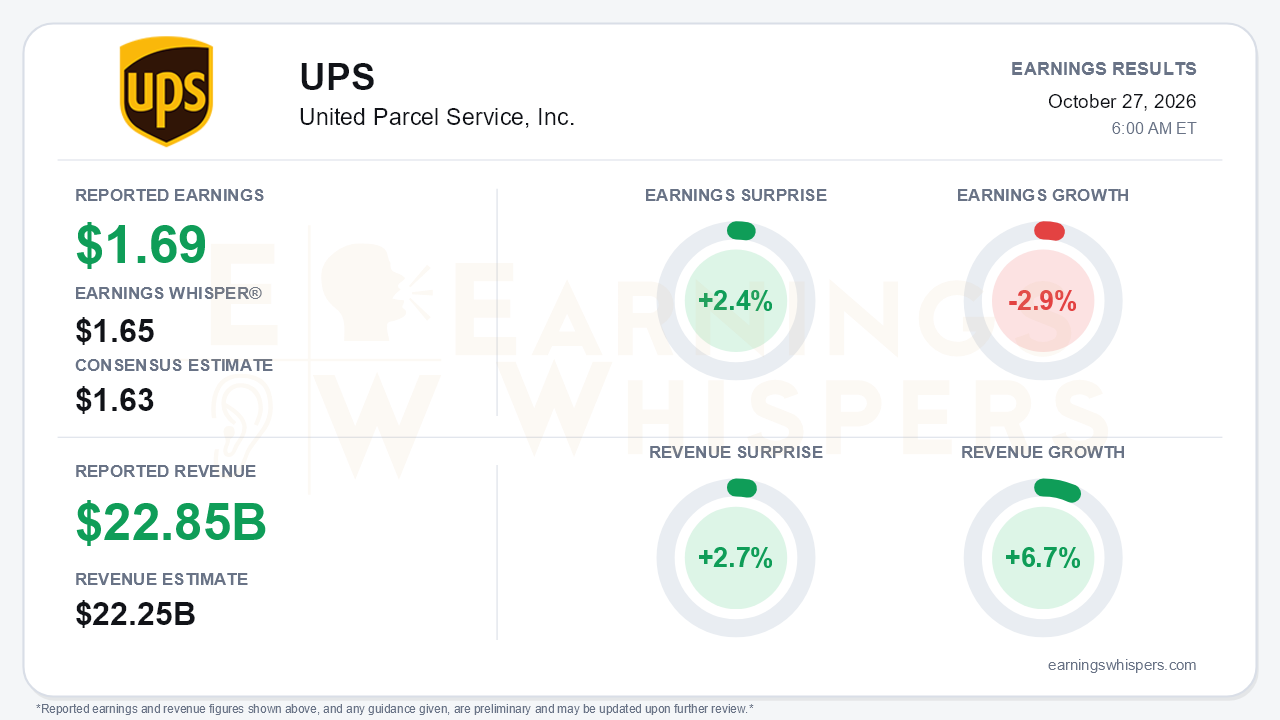
UPS delivered a clean beat on the numbers that matter most to the turnaround thesis. Adjusted earnings of $1.69 per share topped the $1.63 consensus by 2.4% and cleared the $1.65 Earnings Whisper number. Revenue of $22.853 billion rose 6.7% and beat expectations by 2.7%, with growth in all three segments. UPS also raised full-year guidance for the second straight quarter. Revenue is now expected at about $92.6 billion, up from $91.2 billion, with adjusted operating profit of about $8.75 billion and adjusted EPS of about $7.28. The central tension is that the profit inflection after the Amazon glide-down is now visible, while the pricing tailwind that powered it is clearly fading.
The 2.9% year-over-year decline in adjusted EPS looks worse than the operating picture. Last year's third quarter included a $330 million sale-leaseback gain in Supply Chain Solutions, worth $0.30 per share. That gain more than accounts for the shortfall. The GAAP picture is noisier. Diluted EPS fell to $1.37 from $1.55 after a $0.32 net charge, which included $130 million of after-tax transformation costs and a $182 million goodwill impairment in Supply Chain Solutions. That impairment matters because SCS was also the quarter's operational soft spot. Revenue jumped 18.2% on forwarding, logistics and healthcare, but the 9.2% adjusted margin fell short of management's 10-11% guide. Cash generation was the stronger story. Nine-month free cash flow reached $4.22 billion versus $2.74 billion a year ago, and the full-year target rose to about $6.1 billion from $5.5 billion. Investors should note that part of that lift came from a $450 million pension contribution made in UPS bonds rather than cash.
U.S. Domestic is where the turnaround shows up, and also where the scrutiny belongs. Adjusted operating profit rose 14.3% to $1.03 billion, and margin expanded 60 basis points to 7.0%, in line with guidance. Average daily volume fell 3.3%, yet revenue still grew 4.5% on a 6.1% gain in revenue per piece. SMB penetration hit a record 35.1%. However, revenue-per-piece growth slowed sharply from 9.3% in the second quarter. Adjusted cost per piece rose 5.5%, so the spread between price and cost narrowed to roughly 60 basis points from 130. Management still frames U.S. margins as improving every year on a 50-100 basis-point spread. Even so, the quarter landed near the bottom of that range, and SMB volume growth eased to 3.7% from 4.3%.
International was the most encouraging surprise. Operating profit of $746 million marked the first year-over-year gain in six quarters. The 14.9% margin beat the 13-14% guide, and management is calling for roughly 20% in the fourth quarter. That came despite international volume falling 8.7%, a steeper decline than the 5.8% drop in the second quarter, after the EU eliminated de minimis treatment in July. Revenue per piece up 15% did the heavy lifting. Other catalysts include U.S. inbound volume returning to growth in September and Asia-to-Asia exports up 8.4%. Management also framed data-center logistics as a $15 billion opportunity, with high-tech small package up 30%.
The forward cost story also improved. Program savings reached $1.8 billion through September against a target of nearly $3 billion. The Driver Choice program is complete, and its roughly $1.4 billion one-time cash cost rolls off in 2027. Bears still have legitimate ammunition:
- Fourth-quarter U.S. volume is guided down about 1.3%.
- The Amazon wrap persists into the second half of 2027.
- B2B volume is still declining.
- The Teamster contract expires in August 2028.
The guidance raise also deserves a closer look. The $0.06 EPS increase roughly matches the third-quarter beat, while the revenue outlook rose about $1.4 billion. That implies limited incremental profit on the extra sales.
The market had not been rewarding the story heading into the print. Shares closed at $100.32 the day before the report. That was 7.6% below the open after the July report and 4.1% under the 200-day moving average of $104.61. The stock had rebounded 9.6% off its October 5 low of $91.56 but remained 8.3% below its early-August high. Investor sentiment slipped further into negative territory, from -0.06 to -0.15. That is a meaningful but not dramatic deterioration, and it suggests skepticism rather than lofty expectations going into the report. The Earnings Whispers trend signals are mixed, with price trend negative while momentum and AVWAP readings are positive, consistent with a stock attempting to recover from its autumn low.
The bottom line is that UPS delivered what turnaround skeptics were not positioned for: a beat, a second guidance raise, a return to international profit growth and sharply better cash flow. The quality of the quarter is uneven, however. Domestic pricing momentum is decelerating, the price-cost spread has compressed, and Supply Chain Solutions missed its margin guide alongside an impairment. The setup now hinges on whether the promised fourth-quarter margin step-up, to about 10.5% in the U.S. and 20% internationally, materializes as pricing tailwinds moderate.
Read our earnings preview for United Parcel Service, Inc.: https://www.earningswhispers.com/article/UPS/20732
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 4 hours | |
| 5 hours | |
| 5 hours | |
| 7 hours | |
| 7 hours | |
| 7 hours | |
| 7 hours | |
| 8 hours | |
| 8 hours | |
| 9 hours |
