Here's What to Expect From the Busiest Week of Q4
Stocks opened higher to kick off the final trading week of October as the AI trade rebounded ahead of the heaviest part of the earnings calendar.
The Nasdaq (+0.82%) and S&P 500 (+0.70%) posted solid gains on Monday, while the Dow (+0.28%) lagged a bit, reversing the recent trend of outperformance. Technology led the sector table alongside consumer discretionary and industrials, while communication services were the worst performers.
Staples and health care pulled back from recent 52-week highs as capital rotated out of the defensive positioning that has worked all month.
Anthropic Files for Long-Awaited IPO
Monday’s catalyst was Anthropic's public filing for a U.S. initial public offering. Anthropic is the developer of Claude, one of the leading AI chatbots. The company filed its S-1 prospectus with the SEC on Monday and intends to trade under the ticker 'ANT.'
The filing reported revenue of $16.3 billion for the six months ended June, against $4.6 billion for the whole of 2025, and AI infrastructure spending of $9 billion in the first half of 2026 versus $7.3 billion across all of 2025.
Approximately one-fifth of revenue came from two customers. The company reported a net loss of $80.7 billion through June, which it attributes largely to accounting charges, and disclosed an agreement to spend up to $120.5 billion with SpaceX's AI unit through 2029. Risk factors cited include increasingly restrictive AI regulation. Press reports indicate some investors value the company near $1.5 trillion, down from roughly $2 trillion a week earlier.
AI Financing Debate Remains Front and Center
Despite the seemingly positive session to start the week, the AI financing question did not go away — it got louder. Facebook-parent Meta META announced plans to raise approximately $95 billion in equity to fund AI infrastructure, which follows directly from the non-voting share class the company disclosed last Wednesday and from a quarter in which capital spending exceeded operating cash flow.
Separately, Tesla TSLA CEO Elon Musk warned that debt markets have effectively cut off funding for AI data center operators that lack independent revenue, which sent the neocloud and data center names — Nebius, CoreWeave, IREN and peers — into volatile trading before CoreWeave recovered into positive territory.
Put those items side by side and the picture is consistent regardless of how the tape behaved. One of the most profitable companies in the world is issuing roughly $95 billion of equity to fund AI capacity. One of the largest private AI developers is going public while committing $120.5 billion to a compute supplier through 2029. And a prominent industry figure is publicly stating that the debt window has closed for operators without their own revenue.
Capital is still flowing into this buildout, but the terms on which it flows have tightened considerably, and the market is now sorting companies by whether they can fund themselves.
Fed Meeting Begins Tuesday
This is the most consequential week of the quarter. The Federal Open Market Committee begins its two-day meeting Tuesday with a decision Wednesday afternoon, and while a hold is widely expected, the market is positioned for what may be a hawkish pause under Chairman Warsh. Traders are pricing in a roughly 90% chance that the Fed stays put on Wednesday.
Third-quarter GDP and the core PCE inflation reading arrive late in the week, and both the ECB and Bank of Japan hold policy meetings. The core PCE is of particular significance. It is the Federal Reserve's preferred inflation gauge, it arrives after the committee has already acted, and it will either validate or undercut the hot CPI and PPI prints that drove the first half of this month.
A soft reading would go a long way toward explaining why the 10-year has fallen from its October high despite those prints.
Tech Earnings to Set the Tone
In terms of the earnings slate, the week will be dominated by Big Tech.
The week’s marquee reports arrive in rapid succession, with Microsoft MSFT and Alphabet GOOGL both posting results Wednesday after the close. For Microsoft’s fiscal first quarter, the Zacks Consensus Estimate calls for revenue of $90.58 billion, up 16.6% year over year and squarely within management’s $89.85 billion to $90.95 billion guidance range, alongside earnings of $4.71 per share, up roughly 14%.
Estimates have moved a penny higher over the past 30 days. Microsoft carries a Zacks Rank #3 (Hold) into the print. The company made headlines earlier in the week after extending voluntary buyout offers to roughly 60,000 employees.
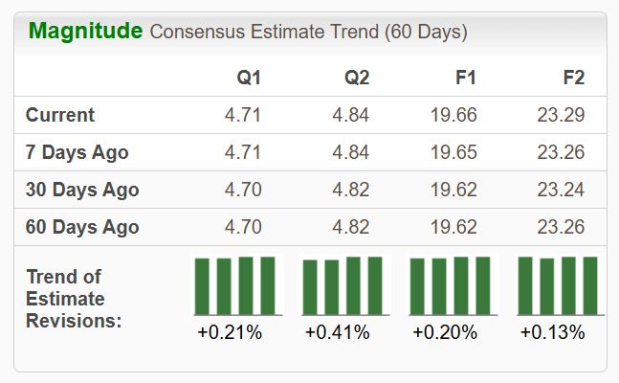
Image Source: Zacks Investment Research
Azure is the number that matters — the Street is looking for acceleration toward 45% growth in constant currency, with demand still outstripping available capacity, while More Personal Computing remains the soft spot.
Alphabet carries a Zacks Rank #2 (Buy) into its report, with the Zacks Consensus Estimate at $2.94 per share, implying 2.44% growth, on revenue of $111.8 billion that would mark a 27.8% increase. Alphabet has exceeded the Zacks Consensus Estimate in each of the past four quarters, with an average surprise of nearly 87%. Despite the positive momentum, shares have struggled in 2026 with a gain of just 1.4%.
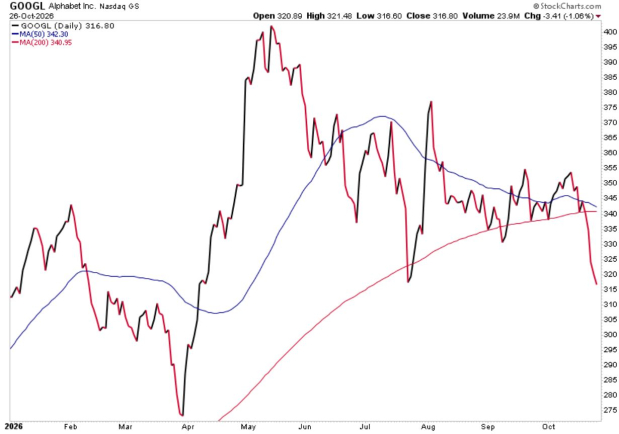
Image Source: StockCharts
Bottom Line
Monday was a good session that unfortunately did not resolve anything. The AI complex rebounded, the semiconductor index gained, and the VIX fell — all encouraging.
But the three largest pieces of news on the day were all about financing: roughly $95 billion of equity issuance from Meta, an IPO filing from Anthropic alongside a $120.5 billion compute commitment, and a public warning that the debt market has closed to data center operators without their own revenue.
The Federal Reserve decides Wednesday. Alphabet and Microsoft report Wednesday evening, and core PCE arrives Friday. We should have a considerably clearer picture by this time next week.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Microsoft Corporation (MSFT): Free Stock Analysis Report
Tesla, Inc. (TSLA): Free Stock Analysis Report
Alphabet Inc. (GOOGL): Free Stock Analysis Report
Meta Platforms, Inc. (META): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Mentioned In This Article
Latest News
| 15 min | |
| 16 min | |
| 31 min | |
| 36 min | |
| 44 min | |
| 45 min | |
| 52 min | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 2 hours | |
| 2 hours | |
| 2 hours |
