Royal Caribbean Beats And Raises Again, But Cost Timing, Fuel And A Softer Q4 Setup Temper The Upside
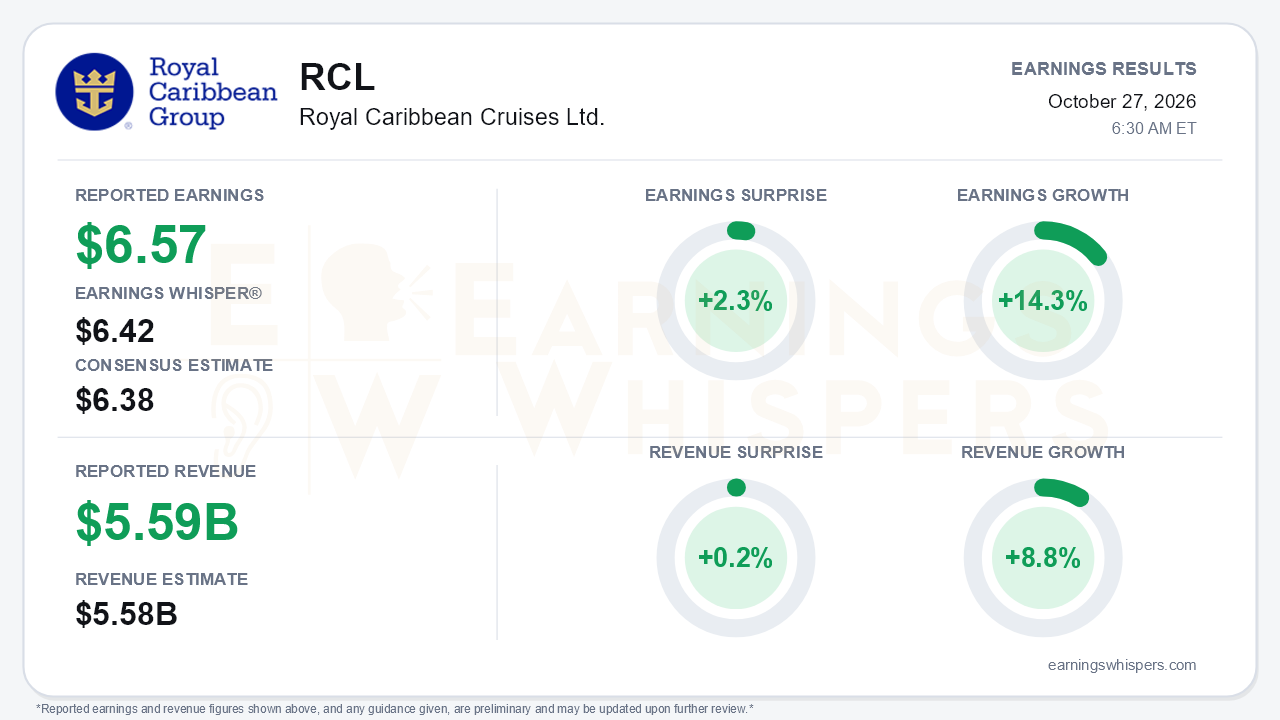
Royal Caribbean delivered its third consecutive beat-and-raise quarter. Adjusted EPS of $6.57 topped the $6.38 consensus by 2.3% and the $6.42 Earnings Whisper number. Revenue of $5.591 billion edged past the $5.58 billion estimate. Adjusted earnings grew 14.3% year over year on 8.8% revenue growth, faster than the low-double-digit pace implied for the first half. Management lifted full-year adjusted EPS guidance to $17.85-$17.95, put a $3 billion bet on all-inclusive resorts, and said 2027 bookings are running ahead of historical levels at higher rates. The central tension is that the quality of the beat deserves scrutiny, and the forward guidance is less generous than the headline raise suggests.
Start with how the company beat. Against its own guidance, Q3 adjusted EPS cleared the $6.26-$6.36 range by about $0.26 at the midpoint. Some of that came from pricing. Net yields rose 0.6% in constant currency against guidance of roughly flat, helped by close-in demand in Europe and the Caribbean. A meaningful portion, however, came from cost timing. Net cruise costs excluding fuel per APCD fell 1.9%, and the company explicitly attributed the better-than-expected cost performance to expenses that shifted into the fourth quarter. The full-year EPS midpoint rose only about $0.10, well short of the Q3 outperformance. That implies Q4 now absorbs those deferred costs plus higher fuel and unfavorable currency. Full-year fuel expense is now about $1.35 billion, up from $1.3 billion at the Q2 call and $1.17 billion in January. This helps explain why Earnings Whispers flagged guidance as below estimates even though the company framed it as a raise. Investors should also note the revenue mix. With capacity up 8%, the 9% revenue gain was overwhelmingly volume-driven. Gross margin yields actually declined 0.8%, and share count reduction (diluted shares fell to 268 million from 274 million) amplified per-share growth.
The call was where the bullish case got stronger. Demand language shifted from a book position 'in line with prior years' in Q2 to 'ahead of prior year at record rates.' Booking volumes have risen in the mid-teens since the last call, and 2027 sailings are up in the high teens. Adjusted EBITDA margin reached 45.4%, versus 44.6% a year ago, and pre-cruise and onboard spending rates remain ahead of last year. Q4 net yield guidance of 4.2%-4.7% in constant currency was maintained. Management also said Perfecta is tracking roughly $1 above its 2027 EPS target at original fuel prices and reiterated a '$20 handle' on the forward fuel curve. The ROIC target has already been achieved.
The Sandals and Beaches deal is the strategic headline. Royal Caribbean is paying about $3 billion for a 50% stake, roughly 10x forward EBITDA, with management keeping leverage below 3x and citing several hundred million dollars in synergies over time. The roughly 30% guest overlap in each direction gives the cross-selling thesis substance. Near term, though, the contribution is immaterial for 2027, the investment will be reported under equity-method accounting on a one-quarter lag, and integration risk is new territory for a cruise operator. Bears also have legitimate ammunition on 2027:
- Capacity growth slows to 4.5% from 6.6%.
- Q1 2027 faces about 200 basis points of structural yield headwind, including dry-dock timing.
- Full-year 2026 yield growth of about 2.1% still sits below January's 1.5%-3.5% midpoint.
- Competitor commentary on Caribbean capacity and first-quarter deceleration adds noise.
- The Mahahual development remains unresolved.
Investor sentiment improved meaningfully into the print. It moved from essentially neutral (0.008) after the July report to moderately positive (0.26). The stock has had a far rougher ride. Shares peaked at $334 on August 4, then collapsed to a 52-week low of $222.22 on September 23. They have since rebounded 26% to $280.60. That still leaves them 7.3% below the open following the July report and about 2% under the 200-day moving average of $286.44. Earnings Whispers trend readings are mixed: price trend remains negative while AVWAP has turned positive, consistent with a stock recovering from a washout but not yet reclaiming its prior footing.
The bottom line is that Royal Caribbean's demand story is getting better, not worse. Accelerating bookings, sturdy onboard spending and a credible path to Perfecta outweigh a modest headline beat. The market setup is more complicated than the surprise implies. Part of the Q3 upside was borrowed from Q4 through cost timing, fuel and currency are eroding the raise, and 2027 opens with slower capacity growth and a yield headwind. With shares sitting just below the 200-day average after a violent round trip, the next leg depends on whether 2027 pricing strength can outrun those near-term frictions.
Read our earnings preview for Royal Caribbean Cruises Ltd.: https://www.earningswhispers.com/article/RCL/20721
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 4 hours | |
| 6 hours |
Royal Caribbean Tops Buy Point On Bullish Outlook. There's One Chart Element To Watch.
RCL +5.46%
Investor's Business Daily
|
| 6 hours | |
| 8 hours | |
| 8 hours | |
| 10 hours |
Royal Caribbean Lifts Full-Year Forecast After Posting Higher Quarterly Profit
RCL +5.46%
The Wall Street Journal
|
| 10 hours | |
| 11 hours | |
| 11 hours | |
| 12 hours | |
| 12 hours | |
| Oct-23 | |
| Oct-23 | |
| Oct-16 |
