Cushman & Wakefield Must Prove Its Capital Markets Slump Was Only An Air Pocket
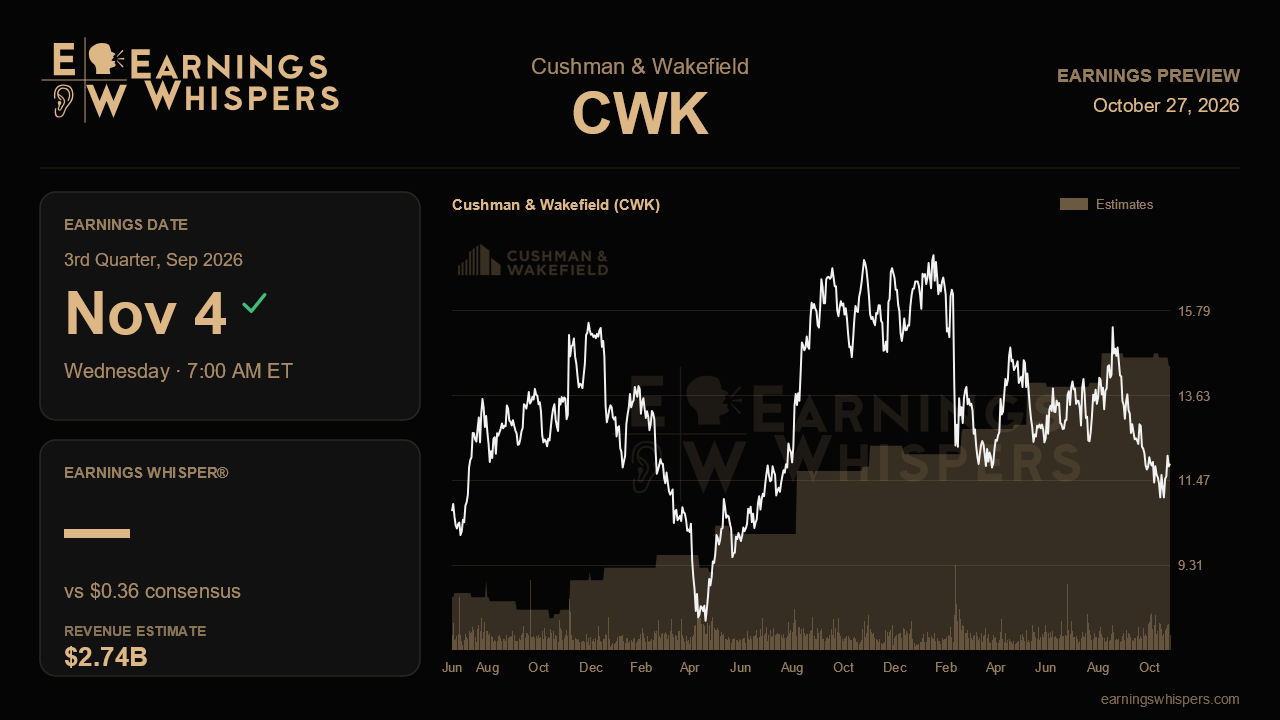
Cushman & Wakefield heads into its third-quarter report with an odd disconnect. Last quarter the company posted record second-quarter results, raised its full-year earnings growth target and sounded more confident than it had in years. Since then the stock has fallen 16%, trailing the S&P 500 by nearly 15 percentage points. The market appears to be focused on the one blemish in an otherwise strong quarter: a sudden stall in capital markets revenue. This report should show whether that stall was a one-off, as management argued, or the start of something more lasting.
Wall Street expects adjusted earnings of $0.36 per share, up about 24% from $0.29 a year ago, on revenue of roughly $2.74 billion, up a more modest 5.2%. That gap between earnings and revenue growth reflects the operating leverage and lower interest costs the company has been building. The revenue figure is worth a closer look, though. Management said full-year revenue growth should land at the middle to high end of its 6% to 8% range, so a quarter growing near 5% would mark a noticeable cooling from the 11% pace of the second quarter. The full-year earnings guide of $1.44 to $1.50 per share sits against a consensus of $1.45, near the bottom of the range. In other words, analysts have not bought into the upper half of management's outlook. That leaves room for an upside surprise, but it also signals some skepticism about the back half.
Capital markets is the central swing factor. After six straight quarters of double-digit growth, the business slipped 1% globally and 6% in the Americas last quarter. Management blamed the drop on a concentration of large institutional office and multifamily portfolio deals, a segment where the firm is still building its presence, and said early third-quarter activity looked better. A return to positive growth, especially in the Americas, would support that explanation. Another flat or negative quarter would make the anomaly argument much harder to sustain, even though management stressed that its raised guidance does not depend on a capital markets rebound.
Leasing carries the opposite burden. Global leasing jumped 27% and the Americas rose 35%, both accelerating sharply from earlier quarters. Nobody should expect that pace to hold indefinitely, but solid double-digit growth in the Americas would show the momentum is real rather than a pull-forward. EMEA leasing, down 6% on weakness in the UK and Ireland, is unlikely to recover quickly by management's own account, so any stabilization there would be a bonus. In services, project management growth of 20% and data-center revenue up 83% year to date are the newer growth stories. Continued strength in facilities management tied to data centers would help make the case that the company's earnings base is becoming more recurring and less cyclical.
The balance sheet offers a quieter but important test. Net leverage reached 3.0 times last quarter, trailing free cash flow conversion improved to 79%, and management talked about reaching the mid-2s, which would open the door to acquisitions or returning capital to shareholders. Progress toward that target, or any detail on how management plans to use the extra capacity, could matter to a stock trading below its 200-day moving average and closer to its post-earnings low of $10.88 than its $15.66 high.
Sentiment has drifted from mildly bullish before the last report to slightly bearish now, which fits the stock's slide. That lowers the bar somewhat, but it does not erase the core question. To keep its narrative intact, Cushman & Wakefield needs to show that strong leasing and services can carry the quarter while capital markets returns to growth. If both happen, the selloff will look overdone. If capital markets stalls again, investors may conclude that last quarter's guidance raise rested on less stable footing than it first appeared.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-23 | |
| Oct-22 | |
| Oct-21 | |
| Oct-19 | |
| Oct-19 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-08 | |
| Oct-06 | |
| Oct-06 | |
| Oct-05 |
