CVS Faces Aetna Margin Test As Whisper Number Runs Well Ahead Of Consensus
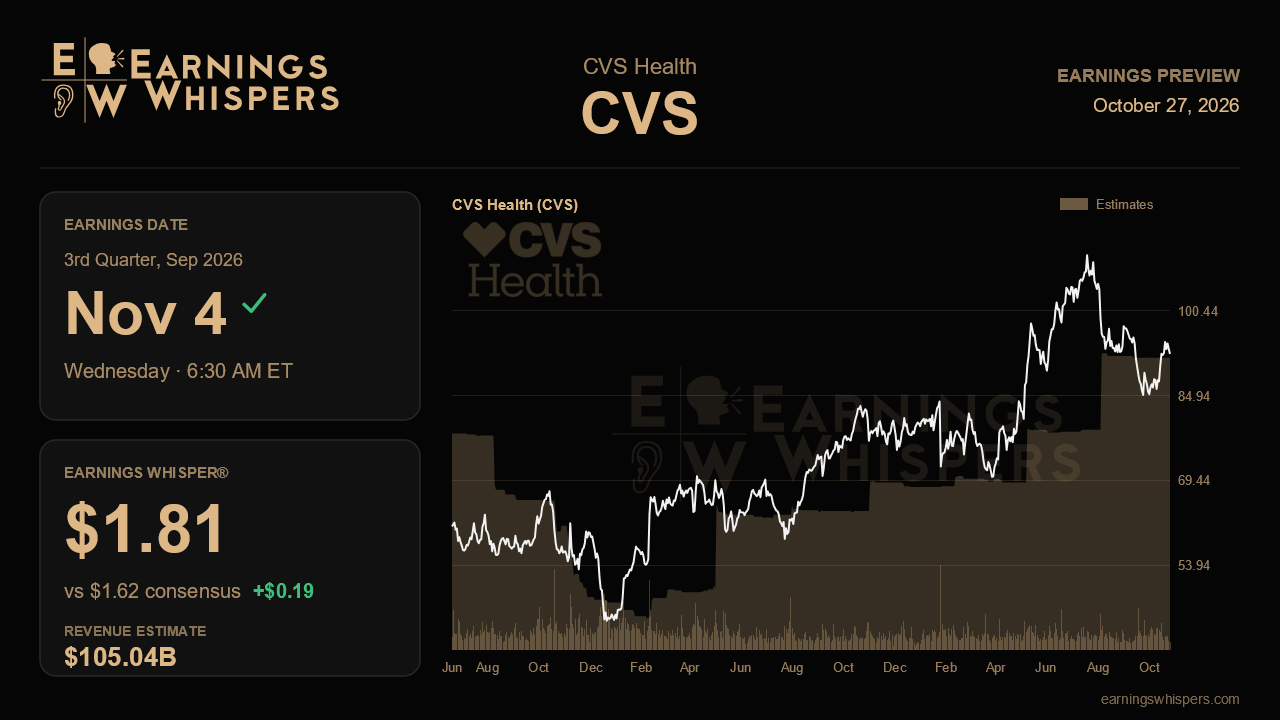
CVS Health has spent 2026 raising its outlook, and that streak has quietly set up a mismatch heading into its third-quarter report on November 4. Management has lifted full-year guidance twice. The quarterly consensus still implies earnings barely above last year's level. The real question is whether Aetna's margin recovery held through a seasonally tougher quarter, and whether softness at Caremark stayed contained.
Analysts expect adjusted earnings of $1.62 a share on revenue of about $105.04 billion. That works out to EPS growth of just 1.3% and revenue growth of 2.1% from a year ago, which reads as essentially flat performance. The whisper number of $1.81 sits roughly 12% above consensus, a meaningful gap that suggests the bar many traders actually care about is higher than the published estimate. It also fits the guidance picture. CVS now expects full-year EPS of $7.90 to $8.10 on revenue of at least $414 billion, up from $7.30 to $7.50 and $405 billion. The full-year consensus of $7.46 sits below the bottom of that range, a sign that some estimates have not fully caught up with management's latest view.
The heart of the story is Healthcare Benefits. Aetna posted a second-quarter medical benefit ratio of 87.4%, a sharp improvement from a year earlier, and has already delivered more than $2 billion of year-over-year operating income improvement this year. Management raised the segment's full-year operating income target by about $1 billion, to $5.03 billion to $5.37 billion. A third-quarter benefit ratio that keeps pace with that improvement would validate the raise. Any drift higher would challenge it, particularly if management points to commercial cost trend or abuse of the No Surprises Act dispute process, which it flagged last quarter. Medical membership of roughly 26 million, down about 700,000 after the exit from the individual exchanges, matters less than whether that smaller book is profitable.
Health Services is the weaker link. Its full-year outlook was only reiterated last quarter, not raised. Strength at Caremark was offset by renewed 340B pressure and by value that shifted from the back half of the year into the first half. That pull-forward means a softer second-half Caremark result could be largely expected. The more important evidence will be any update on the 2027 selling season. Management said retention was running slightly below historical norms and that health plan clients exiting markets would weigh on legacy PBM contracts. Clearer quantification of those headwinds would help investors judge the roughly $8.44 preliminary 2027 EPS floor management pulled forward. Progress on the Eli Lilly cash-pay GLP-1 partnership, the Medicare Bridge program and retail pharmacy, where same-store scripts rose 7% last quarter, would support the case that the enterprise can offset PBM pressure.
The market has been unmoved. Shares slipped 1.3% since the last report, in line with the S&P 500, despite a $0.60 guidance raise and a $2 billion lift to the operating cash flow outlook. Bullish sentiment has cooled to 35.1% from 40.8% a quarter ago. At $92.53, the stock trades above its 200-day moving average of $88.54. It sits in the middle of its post-earnings range of $84.23 to $101, a narrower and lower band than the prior quarter's $85.12 to $110.68.
That combination of rising guidance, a flat stock and cooler sentiment means the report may be judged less on the headline beat and more on durability. If Aetna's margins hold and management reaffirms or nudges up its full-year range while keeping the 2027 floor intact, the improving narrative stays credible. If the benefit ratio slips or 2027 PBM headwinds grow larger, investors will likely conclude that this year's raises reflect a peak rather than a new baseline.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 8 hours | |
| Oct-26 | |
| Oct-26 | |
| Oct-23 | |
| Oct-23 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 |
