McDonald's Must Show Its US Value Reset Is Working After A Self-Inflicted Summer Stumble
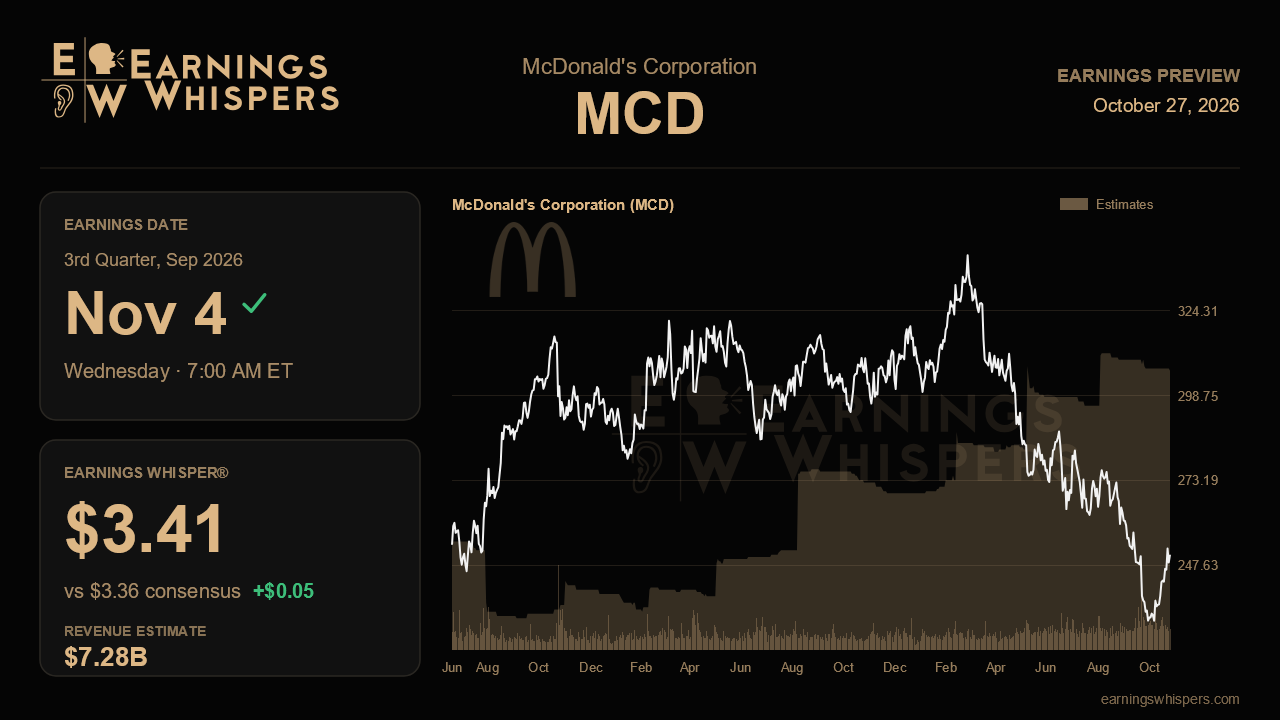
McDonald's heads into its third-quarter report with an unusual burden for a company built on consistency: proving that last quarter's slowdown was a fixable execution error rather than the start of something worse. Three months ago, management openly admitted it had fumbled the US business. Domestic comparable sales slowed from 3.9% in the first quarter to just 0.8% in the second and turned slightly negative in July. This report is the first real check on whether the repair work is taking hold.
The Street is not asking for much. Consensus calls for earnings of $3.36 per share on revenue of $7.28 billion, implying growth of about 4.4% and 2.9%, respectively, from a year ago. That is modest growth, and on the bottom line it is actually a touch below the $3.38 McDonald's earned last quarter. The Earnings Whisper sits at $3.41, slightly above consensus. That suggests some belief that steady margins and cost discipline can carry earnings even if traffic stays soft, but the gap is too small to signal real optimism. Management did not give fresh formal guidance. It did, however, trim its expected full-year currency benefit to about 15 cents from a prior range of 20 to 30 cents, which leaves less room for currency to cover operating shortfalls.
The most important number will be US comparable sales, along with the explanation behind it. Management blamed roughly two-thirds of the US traffic miss on a bad trade. To fund its under-$3 value menu, it pulled national digital offers and a popular buy-one-add-one-for-$1 deal, which alienated its most loyal, high-frequency customers. About a third of franchisees also failed to execute the value menu consistently. The rest of the miss came from an underwhelming FIFA campaign. Since then, the company has said it is restoring digital offers, shifting marketing toward proven value promotions and cutting back on the flood of simultaneous launches that slowed service times. Validation would mean US comps climbing back into positive territory after the negative July start, with signs that loyalty users are returning. Another flat or negative US print would suggest the problem runs deeper than execution. That case would get stronger if management again points to restaurants overwhelmed by too many initiatives.
Outside the US, management set clearer expectations. It guided the International Operated and International Developmental Licensed segments to accelerate sequentially in the third quarter, including on a two-year basis, from second-quarter comps of 1.5% and 1.9%. Missing that guidance would be harder to explain away than a US wobble. Lingering weakness in France and a tough backdrop in China are the obvious risks. The new McCafe beverage platform, which beat plans in the US, Canada and Germany with checks well above the daily average and mostly afternoon traffic, should show up as a growing contributor. The Red Bull energizer rollout adds a fresh test of that momentum.
The market has already passed judgment on the summer. Shares fell 7.2% since the last report while the S&P 500 edged higher, and at about $251 the stock trades well below its 200-day moving average near $284. It sits in the lower half of a post-earnings range of roughly $229 to $278 that is both wider and lower than the prior quarter's band. Sentiment remains firmly bearish, only marginally less so than before the last report. Expectations are subdued, but not quite washed out.
In the end, the report hinges on whether the US traffic slide has bottomed. Margins have held near 47% year to date, so the earnings target looks reachable. Investors need evidence, however, that restoring loyalty deals and simplifying restaurant operations is bringing customers back before the October crew retraining push and new US leadership take over the story.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| 13 hours | |
| Oct-26 | |
| Oct-25 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 |
