Boeing Beats The Whisper But Slides The Commercial Clock: Defense Wins And A New Cash Roadmap Offset A One-Year Delay To The $10 Billion FCF Goal
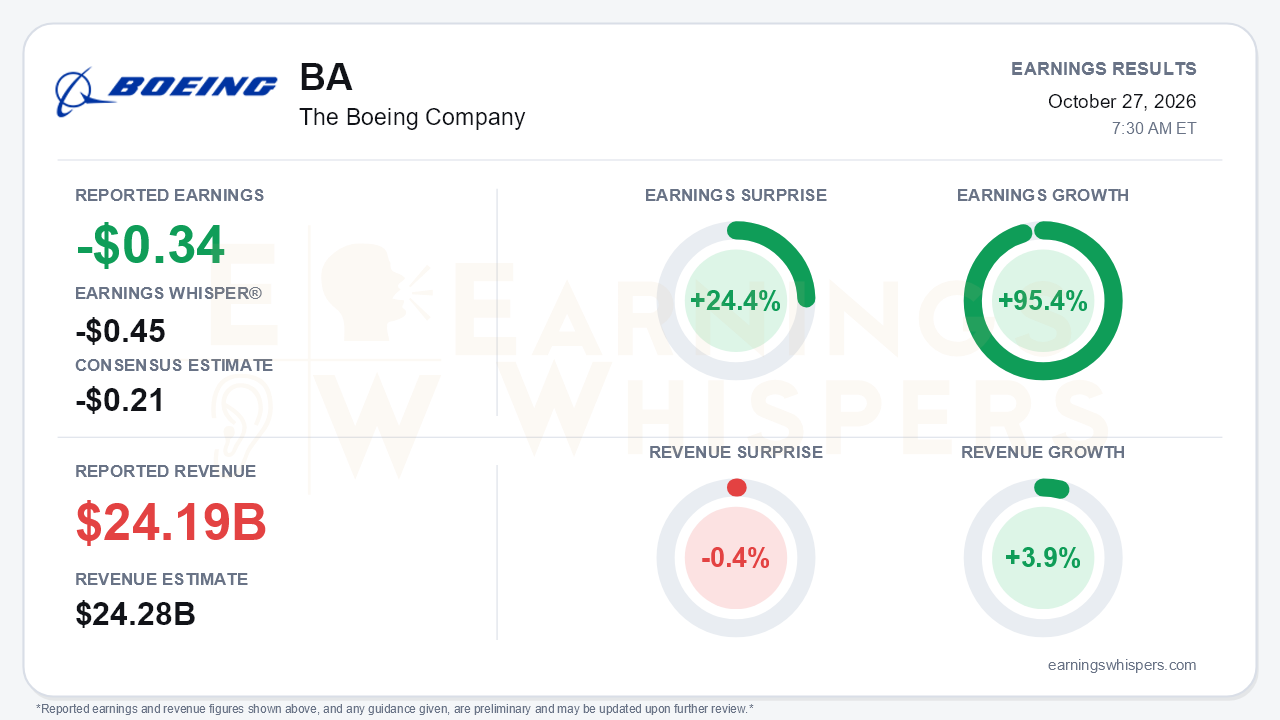
Boeing's third quarter was a split decision. The core loss of $0.34 per share beat the Earnings Whisper number of -$0.45 by 24.4%, but it was wider than the -$0.21 consensus. Revenue of $24.188 billion rose 3.9% year over year and missed the $24.28 billion consensus by 0.4%. Earnings improved 95.4% from a year ago, when the 777X charge produced a $7.47 core loss, and GAAP operating results swung to a $354 million profit from a $4.78 billion loss. The more important trend runs the other way. Revenue growth has slowed from 14% in the first quarter to 8% in the second and roughly 4% now. Management also used the call to push nearly every commercial milestone further out. That is the central tension: the defense franchise and the backlog have never looked stronger, while the commercial recovery that drives the equity story just moved a year to the right.
The quality of the quarter deserves scrutiny. Consolidated operating margin improved to 1.5% from 0.6% in the second quarter, and the core loss narrowed from -$0.76. Much of that improvement came from outside Commercial Airplanes. Defense, Space & Security posted a 6.2% margin, but $252 million of its $492 million operating profit came from the HRL Laboratories sale. Global Services was the clean performer, with an 18.3% margin and 11% organic growth. Commercial Airplanes went the wrong way. Its margin deteriorated to -6.5% from -2.7% in the second quarter on a less favorable delivery mix, higher projected costs from production-rate adjustments and higher supply-chain costs. Revenue in the segment fell 3% on essentially flat deliveries of 161 airplanes. Cash was better than feared. Free cash flow of $464 million beat the second-quarter guide for the 'low hundreds of millions' despite roughly $700 million of Department of Justice settlement payments. Debt held at $45.9 billion against $20.7 billion of cash and investments.
The call documented a broad reset of commercial expectations:
- **737 rates:** Wing flow-enabler shortfalls pushed rate-47 stability into 2027, and rate 52 is now targeted for the second half of 2027.
- **737 deliveries:** Shipments will fall short of the 500-unit target that management had reaffirmed for three straight quarters.
- **787:** Deliveries are guided to the low end of 90-100 as the move to rate 10 slips.
- **777F and 767:** A wing-component supplier disruption will carry abnormal costs into the first half of 2027.
- **Margins:** Commercial breakeven moved to early 2028, from the first quarter's goal of positive margins by mid-2027. Management also conceded that 737 margins will not return to 2018 levels, a retreat from second-quarter language.
The offset is real. The 737-7 and 737-10 both won FAA certification, which removes a key 2026 risk and frees about 30 pre-built aircraft for delivery in 2027. Defense momentum accelerated:
- The F/A-XX selection adds to the F-47 award, though F/A-XX is not yet in backlog.
- A seven-year PAC-3 seeker contract should eventually triple production.
- Boeing added 22 more F-15EX aircraft to its contracts.
- Starliner now has a path forward with $359 million of additional NASA funding.
Defense backlog jumped to $101 billion from $85 billion on $23 billion of quarterly orders, and the CEO lifted the defense growth outlook to mid-single digits or higher. Total backlog reached a record $745 billion. A new SPEEA engineering contract also eliminated the strike risk flagged last quarter.
The new multi-year free-cash-flow framework is the most consequential forward-looking disclosure. Management now targets about $2 billion in 2026, narrowed from $1-3 billion, followed by about $3 billion in 2027, about $6 billion in 2028 and $10 billion in 2029. The concreteness is welcome, but the CEO himself called the profile a one-year shift to the right. The 2027 figure is weighed down by a few billion dollars of lower commercial deposits and roughly $5 billion of capex. Normalized capex is now expected at 3-4% of revenue, versus about 2% historically. The 777X remains a swing factor: planning assumes certification by mid-2027, with ETOPS and flight-test authorization still pending.
The market had largely anticipated disappointment. Shares entered the report at $188.31, down 12% since the open after the July report. That price sits 13.8% below the 200-day moving average, about 22% below the August 5 inter-earnings high of $241.09 and only 3.2% above the October 23 low. Investor sentiment slipped from a slightly positive 0.06 to a mildly negative -0.08. That is a modest shift, but it means expectations were no longer leaning bullish. The Earnings Whispers trend readings are mixed: price and AVWAP trends are negative, while momentum is positive.
The bottom line is that Boeing delivered a quarter that turnaround bulls and skeptics can both use. Certifications, a record backlog, accelerating defense wins and a hard cash roadmap strengthen the long-term case. Bears have legitimate ammunition, though, in a deteriorating commercial margin, slipping production rates, structurally higher capex and a $10 billion cash target that is now a 2029 event. With the stock already pinned near its quarterly low, the next test is execution against these reset timelines rather than another round of promises.
Read our earnings preview for The Boeing Company: https://www.earningswhispers.com/article/BA/20681
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 46 min | |
| 1 hour | |
| 1 hour | |
| 2 hours | |
| 3 hours | |
| 3 hours | |
| 4 hours | |
| 4 hours | |
| 5 hours | |
| 5 hours | |
| 5 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 7 hours |
Stock Market Today: Dow Rises Ahead Of Fed Meet; Boeing Rallies On Earnings (Live Coverage)
BA -10.78%
Investor's Business Daily
|
