Uber Must Show 20% Bookings Growth Can Coexist With A Soft Profit Outlook
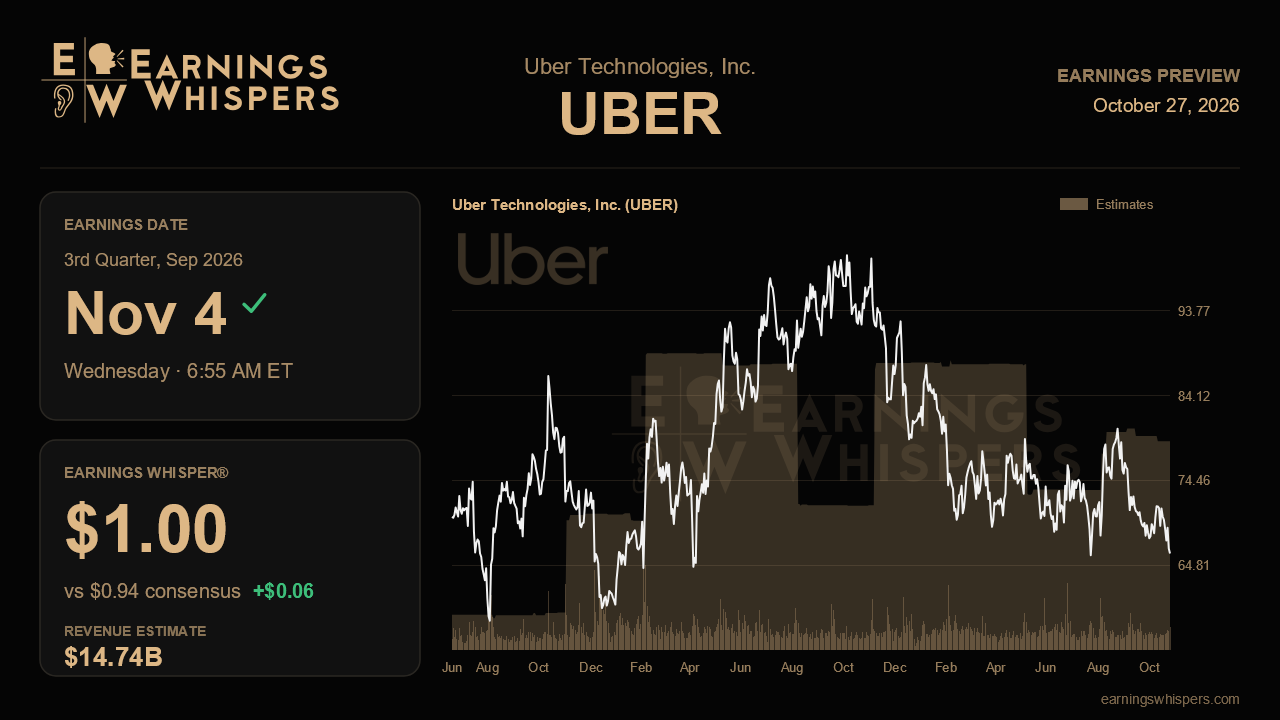
Uber heads into its third-quarter report with an awkward split screen. Operationally, the company just delivered its fourth straight quarter of gross bookings growth above 20%, record trailing free cash flow above $10 billion and an unusually aggressive expansion agenda built around autonomous vehicles and a planned Delivery Hero acquisition. Yet management followed that with a profit outlook below what the Street had penciled in, and the stock now trades near the bottom of its post-earnings range. The November 4 release, due before the opening bell, needs to show whether the soft guide was simple conservatism or an early sign that Uber's expansion is starting to cost more than it earns.
The numbers frame the tension. Management guided to third-quarter earnings of $0.84 to $0.88 a share when consensus sat at $0.90. Since then the consensus has moved up, not down, to $0.94, and the whisper number is higher still at $1.00. That leaves the Street above the top of the company's own range, with the whisper signaling that some investors expect a meaningful beat. Revenue is expected at about $14.74 billion, up 9.5% from a year ago and a modest step up from the $14.19 billion posted last quarter. The projected 70% drop in year-over-year EPS looks alarming, but it mostly reflects a comparison with a year-ago figure of $3.11 that was far above Uber's recent quarterly run rate. The more relevant comparison is the sequential slide from $1.17 last quarter, which is what the guidance implies and what the market needs explained.
The gap between bookings growth of more than 20% and revenue growth below 10% is the first thing to examine. Management attributed most of last quarter's roughly 500 basis point decline in mobility take rate to a UK business-model change that is largely optical, with the remainder a deliberate push into lower-cost products. If net take rate holds broadly stable again and bookings stay above 20%, that explanation survives. If take rate erosion widens beyond the UK effect, it would suggest the low-cost investment is getting more expensive. Delivery also faces a known headwind as it laps the larger Trendyol acquisition, so the cleaner test is whether organic delivery growth keeps accelerating, as management claimed.
The second test is whether last quarter's US mobility inflection was durable. Some of the acceleration came from the World Cup, but management credited broader drivers: insurance savings being reinvested into pricing, especially in California, rapid growth in Uber for Business and deeper penetration of sparse markets. Continued trip acceleration without the event tailwind would validate that story. Brazil is the contained risk to monitor; competition from Didi Food and Meituan has been bidding up courier supply, and any sign that pressure is spreading to margins or other markets would challenge the view that it is an isolated problem.
The autonomous push matters as much for spending as for growth. Uber has committed to a $10 billion multi-year AV plan, targets 15 AV cities by year-end from seven, and is diverting capital toward Delivery Hero shares, which slowed buybacks. Progress on city launches and clarity on how much of the softer earnings outlook reflects AV and integration costs will shape how the market values this pivot.
Sentiment is mildly bearish and only slightly worse than a quarter ago, while the stock has fallen 4.2% since the last report, lagging the S&P 500 by nearly three points. At $66.13 it sits below its 200-day average of $73.80 and just above its post-earnings low of $65.68. That positioning means the bar on sentiment is low even as the bar on earnings, with consensus above guidance, is high. Ultimately, the report will turn on one question: can Uber keep bookings growing above 20% while showing that its AV and acquisition ambitions are investments with a visible return rather than a drain on the earnings power that built the bull case?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 5 hours | |
| 7 hours | |
| 8 hours | |
| 9 hours | |
| 10 hours | |
| 11 hours | |
| 13 hours | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 |
