AMC Must Prove Its Record Summer Was A Turning Point, Not A Blockbuster Fluke
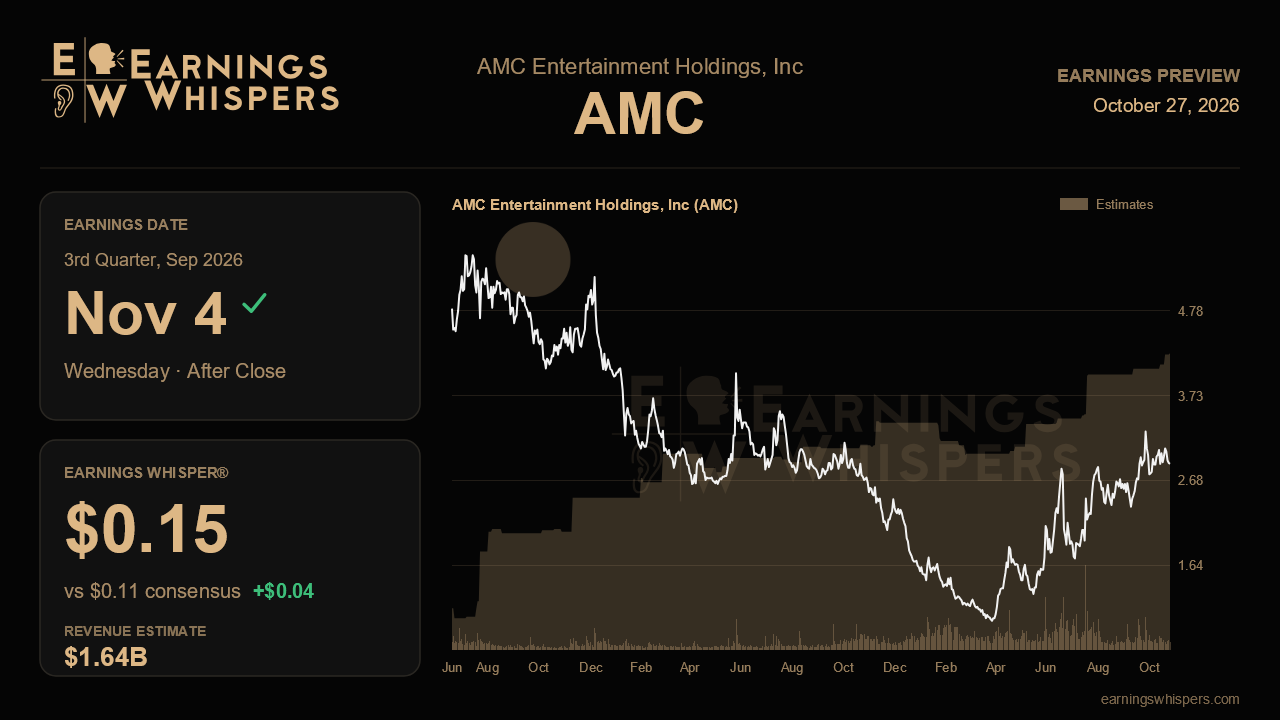
AMC Entertainment just delivered the best quarter in its 106-year history, and the stock has rallied hard on the belief that the box office recovery has finally found its footing. The third-quarter report, due after the close on November 4, is the first real test of whether that breakout can repeat. Wall Street is not simply asking AMC to stay profitable. It is asking the company to top its own record revenue while lapping one of the weakest stretches of its recent past.
Consensus calls for earnings of $0.11 per share on revenue of $1.64 billion. That would swing from a loss of $0.21 a year ago, and the 26.1% revenue gain would be faster than the 14.2% growth AMC posted last quarter. The comparison is friendly: the year-ago quarter brought $1.3 billion in revenue, an 11% drop in North American box office and only $122 million of adjusted EBITDA. The Earnings Whisper of $0.15 is meaningfully above consensus and slightly above last quarter's $0.14. That suggests the informal bar assumes the second-quarter performance was a base, not a peak. Management did not give a formal earnings outlook. Its decision to raise capital spending plans to $200 million to $235 million, up from $175 million to $225 million, signaled confidence that demand justifies more investment.
The most important evidence will come from flow-through. Last quarter roughly two-thirds of incremental revenue reached adjusted EBITDA, which pushed margin up 650 basis points to 20.1%. If revenue lands near $1.64 billion with similar operating leverage, EBITDA should come in far above last year's $122 million and confirm that AMC's cost base has been reset. Investors should also strip out last quarter's help from a roughly $5.5 million insurance credit and a modest currency tailwind. A margin that holds up without those aids would validate the narrative. A sharp slide would suggest the record owed more to luck than structure.
The film slate matters too. The Odyssey opened to $124 million domestically with 4.3 million guests over its first weekend, and management pointed to strong advance bookings for Spider-Man: Brand New Day. Attendance, per-patron food and beverage spending and the share of guests choosing premium large-format screens will show whether AMC is capturing more than its share of those hits. Last quarter, U.S. admissions revenue ran 70 basis points ahead of the industry. Europe, where EBITDA more than quadrupled, is another place to check whether gains are broad or concentrated.
The balance sheet story should start showing up in the income statement. AMC refinanced $400 million, converted $155.8 million of debt to equity and paid $125.5 million in cash on July 24 to redeem 2027 notes. Management estimated roughly $67 million in combined annual interest savings. Lower interest expense should help EPS, but the redemption drains cash, so quarterly free cash flow deserves close reading. Management has been clear that full-year free cash flow breakeven still depends on a strong 2027 slate. Any update on that path, and on progress from leverage below 6.5 times toward the roughly 3 times target, will carry weight.
The expectations bar is clearly higher. Shares have climbed 31.4% since the last report, beating the S&P 500 by nearly 29 points. At $2.89, the stock trades well above its 200-day moving average of $1.95 and in the upper half of its post-earnings range of $2.10 to $3.40, though below that high. Sentiment has cooled slightly from the prior quarter, which hints at some caution after the run. The central question is whether AMC can turn a record summer into durable earnings power. That means growth beyond easy comparisons, margins that hold up without one-time help, and visible progress toward self-funding cash flow.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-25 | |
| Oct-25 | |
| Oct-22 | |
| Oct-09 | |
| Oct-08 | |
| Oct-05 | |
| Oct-01 | |
| Sep-23 | |
| Sep-23 | |
| Sep-21 | |
| Sep-21 | |
| Sep-21 | |
| Sep-21 | |
| Sep-18 |
