AppLovin Must Prove Its Model Upgrade Can Reignite Growth After First Miss
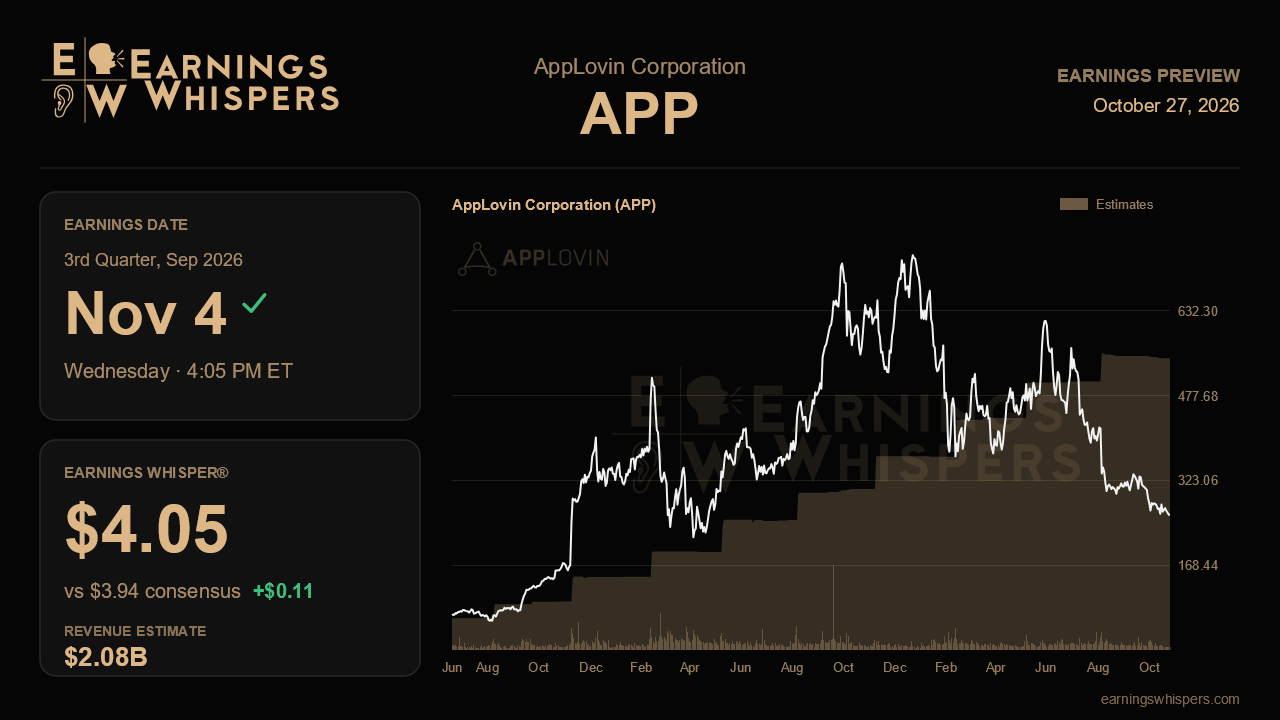
AppLovin enters its third-quarter report with something unfamiliar to explain: a stumble. After a long run of beats, the ad-tech company fell short of its own revenue and adjusted EBITDA targets last quarter, blamed the shortfall on a model upgrade that arrived just after quarter-end, and promised that the improvement was already live and lifting results. The November 4 release, due after the close, is the first real test of whether that was a timing hiccup or the start of a slower chapter.
The Street is taking management at its word, at least on the top line. Consensus calls for revenue of $2.08 billion, near the upper end of the company's $2.055 billion to $2.085 billion guidance range, and earnings of $3.94 a share. That would mean roughly 48% revenue growth and about 61% EPS growth from a year ago, still exceptional by any normal standard. The Earnings Whisper of $4.05 sits modestly above consensus, suggesting the more engaged crowd expects a clean beat on profits. With analysts already near the top of the revenue range, though, a result merely at the midpoint could feel like a second disappointment rather than a recovery.
The arithmetic of the guide tells the story. Management is calling for 7% to 8% sequential growth, a clear rebound from the 4% posted in the second quarter, though well below the 11% achieved in the first. On a year-over-year basis, the 46% to 48% guide continues a stepdown from 59% in the first quarter and a 52% to 55% target for the second. The numbers that would validate the bounce-back narrative are straightforward: revenue at or above the high end, evidence that the newer, more compute-hungry model architecture is driving better advertiser returns, and commentary suggesting that momentum carried into the fourth quarter. A print that lands inside the range without an upbeat outlook would reinforce the idea that growth is settling lower.
Margins are the second swing factor. Adjusted EBITDA margin slipped to about 84% last quarter from a record 85%, and management guided to roughly 83% this time, explicitly warning that higher training and inference costs could make profitability lumpier. That is the trade-off underpinning the model story: more compute should yield better ads, but it costs money. If revenue upside arrives with margins holding near guidance, the spending looks productive. If margins slip further without a matching revenue surprise, investors may start questioning the payback.
The consumer and e-commerce push deserves close scrutiny. Advertiser spend in that vertical hit a record last quarter, running 28% above the seasonal peak of late 2025, and the company opened its Ads Manager platform to all advertisers in late June while adding partnership channels such as Triple Whale to bring in larger mid-market merchants. This report offers the first full quarter of that broader launch. Management also flagged that the consumer business is not yet big enough to cushion a soft quarter in gaming, and that video creative generation remains a bottleneck for onboarding smaller advertisers. Any update on new-customer value, which management said should rise above the prior roughly $70,000 annual benchmark, would help gauge whether this second engine is maturing. Free cash flow and buybacks, both of which slowed last quarter, are also worth tracking.
The market has delivered its verdict on the miss already. Shares have fallen 23% since the last report while the S&P 500 was roughly flat, and at about $261 the stock sits near the bottom of its post-earnings range of $255 to $352, far beneath its 200-day moving average near $425. Sentiment has edged from slightly bullish to slightly bearish. That reset lowers the emotional bar, but not the numerical one. The central question is whether the model upgrade delivers the promised reacceleration at healthy margins; if it does, last quarter looks like a pothole, and if it does not, the deceleration story gains real traction.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 6 hours | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 |
