Expedia Must Prove Its Raised Outlook Survives A Guided Third-Quarter Slowdown In Bookings
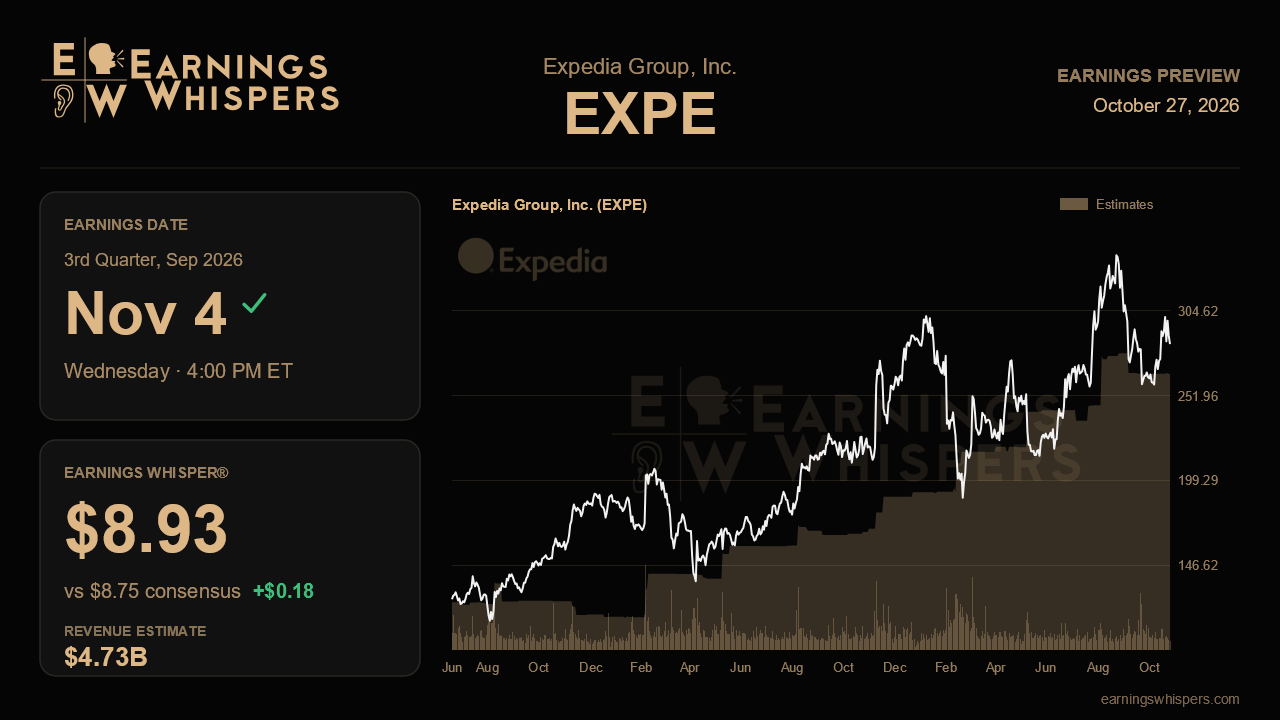
Expedia heads into its third-quarter report with an unusual mismatch between its business and its stock. Three months ago management delivered a fifth straight beat, raised full-year targets for bookings, revenue and margins, and pointed to a string of new growth projects. Since then the shares have fallen about 12.6% while the S&P 500 was roughly flat. That gap suggests the market has focused on the part of the story management itself flagged: growth is supposed to cool noticeably in the second half. This report, due after the close on November 4, will show whether that slowdown is the mild, comparison-driven dip the company described or something more worrying.
Wall Street expects adjusted earnings of $8.75 a share on revenue of $4.73 billion. That revenue figure would mean growth of about 7.2% from $4.41 billion a year ago, a solid but clearly slower pace than the 14% jump posted last quarter. Against a year-ago profit of $7.03 a share, the consensus implies earnings growth of roughly 24%, which leans heavily on continued margin gains. Management guided third-quarter revenue to $4.65 billion to $4.75 billion, so analysts sit in the upper half of that range, above the $4.70 billion midpoint. The Earnings Whisper of $8.93 is modestly above consensus, a sign that the bar for a convincing beat is a little higher than the published estimate implies.
The most important test is unit growth. Total room nights rose 6% last quarter, matching the prior quarter but well below the 11% pace of a year earlier, and management guided third-quarter gross bookings up just 5% to 7% after a 12% gain in the second quarter. If bookings land at the top of that range and room nights hold near 6%, the deceleration looks like what management said it was: a function of tougher comparisons. A reading below 5%, or room nights slipping further, would challenge the idea that the raised full-year bookings target of 8% to 9% is safe, since a weak third quarter would leave more to prove in the fourth.
Margins are the second swing factor. Expedia lifted its full-year adjusted EBITDA margin expansion target to 150 to 175 basis points, up from the 100 to 125 basis points it had held for two quarters. But it also warned that third-quarter gains would moderate as it laps prior-year cost cuts, spends on its business-to-business unit and absorbs currency headwinds. Holding a meaningful year-over-year margin improvement despite those pressures would validate the raise. Investors should also look for confirmation that the consumer momentum in the U.S., which last quarter posted its fastest growth in 15 quarters, carried into the summer, and that Europe and outbound travel, still hampered by macro weakness and reduced air capacity, did not deteriorate.
The newer catalysts deserve attention, though they are unlikely to move the numbers yet. The B2B segment is chasing a 21st straight quarter of double-digit growth, and updates on the CarTrawler deal, the Layla AI planning app and full U.S. airline coverage will indicate whether management's longer-term pitch is gaining traction. Any sign that B2B margins are suffering more than expected from partner mix and integration costs would be unwelcome.
Sentiment has edged more bearish, at 6.5% bearish versus 2.4% before the last report, consistent with the stock's slide. Shares trade around $284, above the 200-day moving average near $260 but well below the post-earnings high of $342, leaving room for a rebound if the numbers reassure. The central question is simple: does the third quarter look like a speed bump on a raised trajectory, or the first evidence that the raised trajectory was too ambitious?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-21 | |
| Oct-20 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-11 | |
| Oct-10 | |
| Oct-08 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 |
