HubSpot's 37% Rebound Meets Its First Test: Can Retention And Net Adds Stabilize?
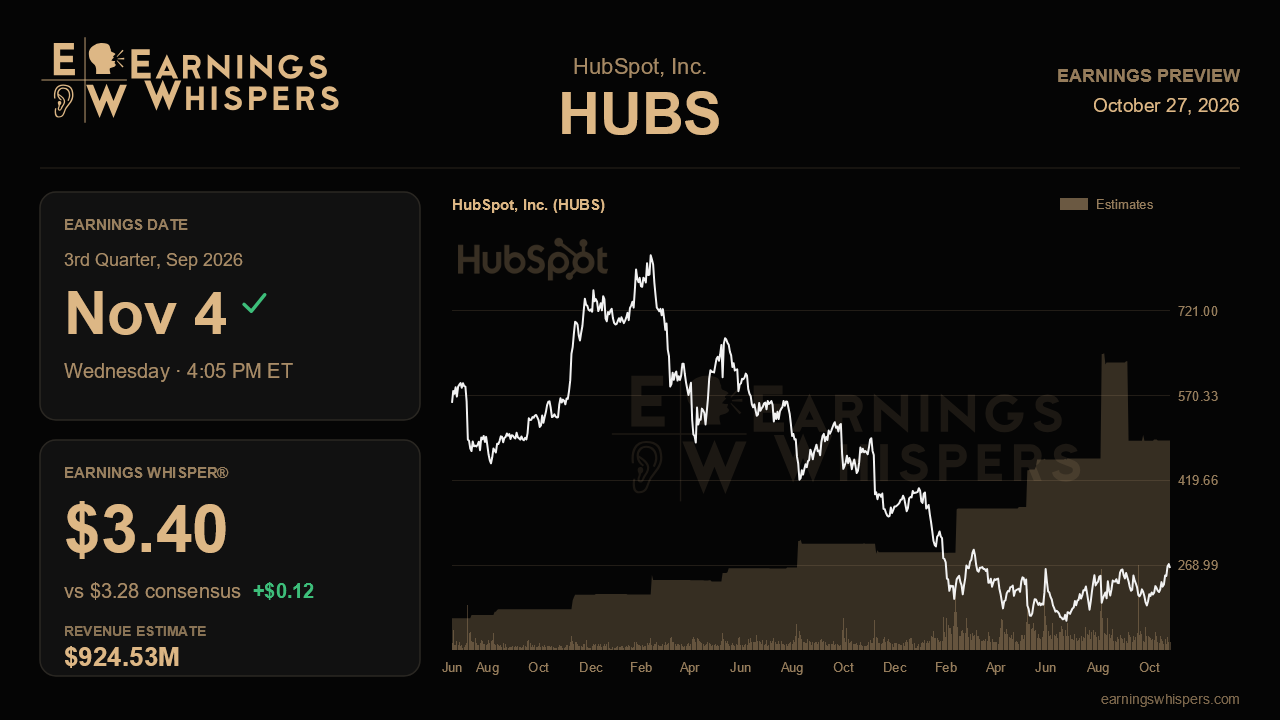
HubSpot enters its third-quarter report in an unusual position. Three months ago, management delivered its most sobering update in years, trimming full-year revenue growth, slashing its net customer additions outlook and conceding that a tougher demand environment had arrived. The stock has since climbed nearly 37%, while the S&P 500 slipped slightly. The market, in other words, has already decided the damage was contained. The November 4 report, due after the close, will show whether that verdict was premature.
The numbers themselves are set up to be cleared. Analysts expect non-GAAP earnings of $3.28 a share on revenue of about $924.5 million, roughly 14% growth from a year ago. That revenue figure sits right at the midpoint of management's $924 million to $925 million range, and the EPS estimate is a penny above the top of guidance of $3.25 to $3.27. Both are well below the $3.48 and roughly $936 million the Street was modeling before the last call, so expectations have been reset rather than stretched. The whisper number of $3.40 is a more meaningful signal, implying that buyers anticipate another margin-driven beat. That fits the pattern: last quarter HubSpot cut its full-year revenue outlook to $3.678 billion to $3.686 billion while raising its earnings forecast, because operating margin keeps expanding even as the top line cools.
That split is the heart of the story. Profitability is not the worry. Operating margin reached 20.3% in the second quarter, up three points from a year earlier, management reaffirmed two points of leverage for 2026 and introduced a target of another two to three points in 2027, and a second $1 billion buyback was authorized. A beat on EPS would confirm that discipline but would not settle the debate. The harder questions concern the customer engine. Net adds came in at only 7,000 last quarter, and management now guides to roughly 5,000 to 6,000 per quarter. Net revenue retention slid to 102% from 105% at the end of last year, and the full-year retention outlook was cut to roughly flat. Most significantly, management said net new ARR would grow slower than revenue this year, reversing a long-running talking point that underpinned the case for a return to 20% growth.
Validation this quarter would look like stabilization rather than recovery. Net adds landing at or above the new range, retention holding near 102% instead of drifting lower, and evidence that longer sales cycles and renewal downgrades have not worsened would suggest the guidance cut was a reset, not the start of a slide. Continued upmarket momentum, where deals above $120,000 in ARR grew 38%, would help. On the AI front, the April price cuts and free agent trials were deliberately designed to sacrifice near-term revenue for adoption. Growth in Data Agent, Customer Agent and the newly launched Agent Builder, along with early traction for Revenue Hub and the standalone AEO product, needs to begin showing up in credit consumption and expansion revenue, not just activation counts. A fourth-quarter outlook that implies further deceleration below the 15% constant-currency pace guided for the third quarter would challenge the thesis directly.
Positioning raises the stakes. Bearish sentiment has eased to about 35% from nearly 49% heading into the last report, and the shares, at roughly $264, sit well above their 200-day moving average and within 3% of the post-earnings high of $271.60. A stock testing a breakout after a 37% run has little cushion for disappointment.
Ultimately, this report hinges less on the headline beat than on whether HubSpot can show its demand problem has stopped getting worse. If net adds, retention and ARR trends hold the line while margins keep expanding, the rebound has a foundation. If they slip again, the rally will look like it priced in a recovery the business has yet to deliver.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-21 | |
| Oct-16 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 | |
| Oct-06 | |
| Oct-06 |
