LPL Financial Beats On Record Adjusted EPS And Faster Organic Growth, But A Commonwealth Downgrade And Slower October Flows Temper The Quarter
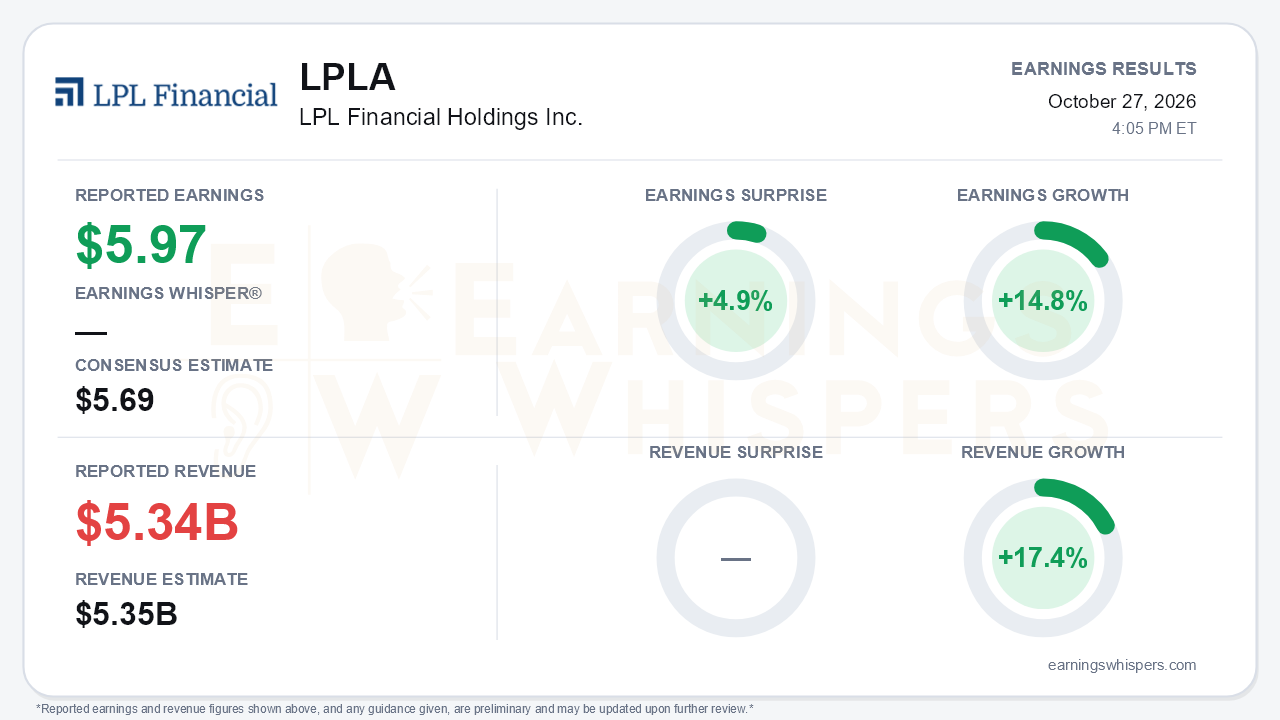
LPL Financial delivered the earnings beat investors expected from a scaled wealth platform, but the quarter is defined by a split narrative. Adjusted EPS reached a record $5.97, topping the $5.69 consensus by 4.9% and growing 14.8% year over year. Revenue of $5.344 billion rose 17.4% but came in 0.1% below the $5.35 billion estimate. Core organic growth improved meaningfully. At the same time, management again lowered the economics of its largest acquisition and signaled softer flows into the fourth quarter. That is the central tension: the existing franchise is executing, while the Commonwealth deal is worth less than the company projected only a quarter ago.
The quality of the beat is reasonable, but it deserves some scrutiny. GAAP EPS was $4.52, a sharp swing from a $0.37 loss a year earlier, when $538 million of Commonwealth closing costs depressed results. Sequentially, however, GAAP EPS fell from $4.74 as acquisition costs rose to $83 million from $49 million. Adjusted EPS climbed for a third straight quarter, from $5.60 to $5.84 to $5.97, helped by a 1% lower diluted share count after another $301 million of buybacks. The modest revenue miss looks largely optical. Other revenue fell to $12 million from $148 million because of deferred compensation marks, and those marks are largely offset in expenses. Year-over-year revenue growth of 17.4% is slower than the 28% nine-month pace as Commonwealth laps its acquisition date. Beneath that, operating leverage was thin. Gross profit rose 12% while core G&A rose 11%, the payout rate increased to 87.98%, and the adjusted pre-tax margin slipped to 38.6% from 39.3% in the second quarter.
The organic story was the bright spot. Organic net new assets rose to $29 billion, roughly 5% annualized, compared with about 4% in each of the prior two quarters. Corporate RIA advisory inflows of $34.5 billion did the heavy lifting. Advisory assets now account for 60.9% of client assets, and quarterly annualized AUM retention improved to 97.4% from 96.4% a year ago. Client cash economics also turned more favorable. The ICA yield rose 16 basis points to 352, and management guided to roughly another 20 basis points in the fourth quarter, citing a sweep methodology change and a September Fed hike. Management also narrowed 2026 core G&A guidance to $2.140-$2.160 billion after third-quarter spending came in below the low end of its range.
Bears have legitimate ammunition, however. Commonwealth asset retention is now expected at about 83%, down from the roughly 90% target held earlier in the year and the mid-80s cited in the second quarter. Run-rate EBITDA guidance fell to about $415 million from $435 million. Momentum also faded within the quarter and beyond it. Organic growth in September ran below 4%, and October is tracking near 3% because of a large attrition item. Recruited assets of $24 billion were down 26% year over year, net new advisors slowed to 122, and transition assistance loan amortization jumped 43%. Management noted that elevated transition assistance rates and competitor retention bonuses persist. Large institutional onboardings have slipped largely to 2028. Fourth-quarter promotional spending, depreciation and amortization of about $130 million, and higher interest expense will add cost pressure.
The forward catalysts are concrete. Commonwealth onboarding is set for mid-November with the technology builds complete. The Cyan AI agent is scheduled to reach all advisors by year end. A pricing and platform-fee review should produce an update in the first half of 2027, and management plans another $300 million of buybacks in the fourth quarter. Leverage of 1.93x leaves room for that capital return.
The market setup was already cautious heading into the report. Shares closed at $317.23 the day before the release, down 9.1% from the open after the July report and 16.3% below the $379 inter-earnings high set in mid-August. The stock had recovered 7.3% from its late-September low but remained about 2.2% below its 200-day moving average. Investor sentiment was negative and drifted slightly lower, from -0.17 to -0.20, a modest change. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while AVWAP remains negative.
The bottom line is that LPL's core engine improved this quarter, with better organic growth, rising cash yields, and disciplined expenses producing a credible beat. The Commonwealth retention and EBITDA cuts, slowing October flows, and a delayed institutional pipeline keep the stock's discount justified until the November conversion shows how much of the acquired base actually stays.
Read our earnings preview for LPL Financial Holdings Inc.: https://www.earningswhispers.com/article/LPLA/20770
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-23 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-14 |
