Cheesecake Factory's Core Brand Breaks Out With A 15% Comp, But North Italia And Thinner Flow-Through Temper The Beat
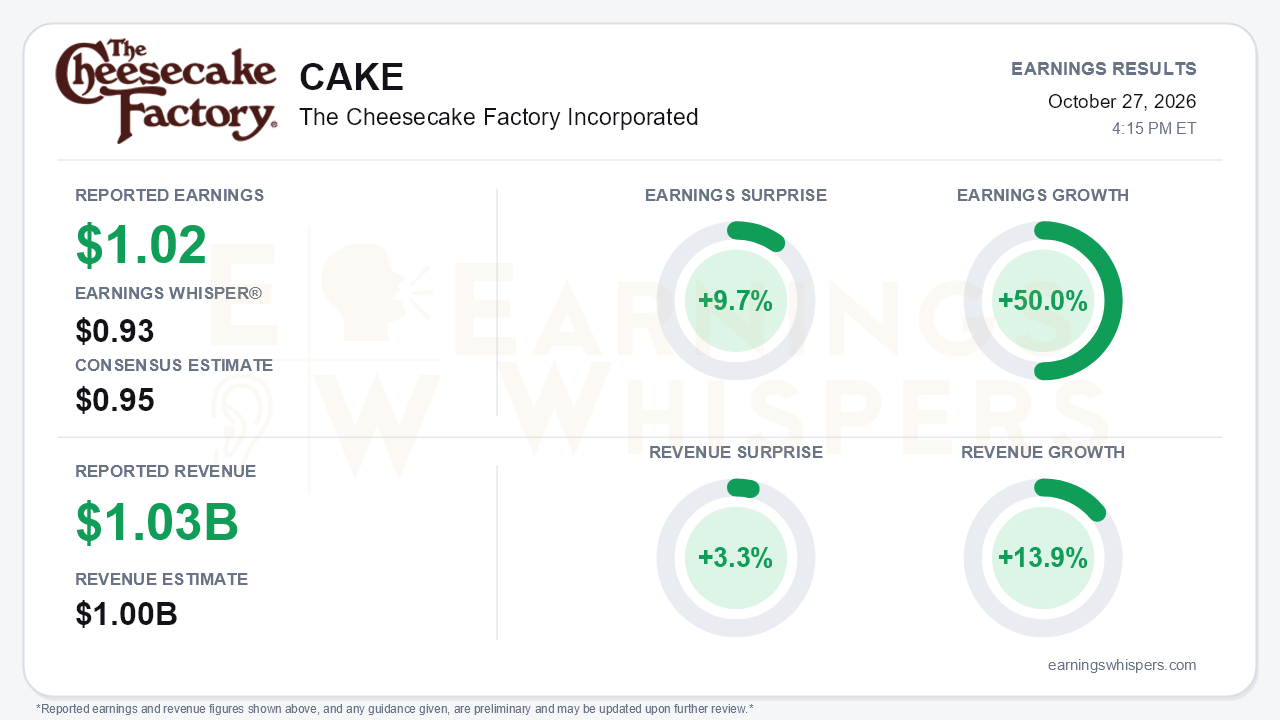
The Cheesecake Factory (NASDAQ: CAKE) delivered the kind of quarter casual-dining investors rarely see. Adjusted earnings of $1.02 per share beat the $0.95 consensus by 9.7% and cleared the $0.93 Earnings Whisper number by a wider margin. Earnings grew 50.0% year over year. Revenue of $1.033 billion rose 13.9% and topped the $1.00 billion consensus by 3.3%. It also far exceeded management's own $980-990 million guide from the July call. The engine was the namesake brand. Comparable sales at Cheesecake Factory restaurants jumped 15.2%, driven by 9.5% traffic growth. That is an extraordinary acceleration from +5.8% in Q2, +1.6% in Q1 and -2.2% in the fourth quarter of fiscal 2025. The central tension is that this breakout is so sharp, and so concentrated in one brand, that management itself is declining to extrapolate it, while the secondary concepts and incremental margins moved the other way.
The quality of the headline beat holds up better than the GAAP figure suggests. Reported diluted EPS of $1.19 was inflated by a $12.9 million pre-tax gain from the final true-up of FRC contingent consideration. Investors should anchor on the $1.02 adjusted figure, which excludes that item. On that basis, the adjusted net income margin reached 5.1% against roughly 4.3% guided, and adjusted EBITDA rose 38%. Cost leverage was broad. Food and beverage fell to 21.2% of revenue from 21.8%, and labor fell to 34.8% from 35.6%. Cheesecake Factory segment operating income climbed to $119.6 million from $87.9 million. Brand AUV now exceeds $13.9 million, up from $12.2 million at the end of fiscal 2025.
Beneath that strength, several metrics went the wrong direction. Restaurant-level flow-through fell to roughly 20-25% from 35% in Q2. Management added labor to absorb the volume surge and booked a $4 million one-time bonus, and it expects further one-time reinvestment costs in Q4. North Italia is the clearest weak spot. Comps fell 3%, AUV slipped to $7.2 million from $7.9 million, and mature restaurant margin dropped to 13.2%. That compares with 15.6% in Q2 and 17.5% in Q4 FY25, leaving the brand well below its 16-18% target. Segment operating income fell to $4.1 million from $5.9 million. The turnaround plan (a new menu, happy hour, media tests and a kitchen management system) is still unproven. Other FRC concepts also posted a slightly wider operating loss.
The forward picture still improved materially. Fourth-quarter revenue guidance of $1.04-1.05 billion implies about $4.06 billion for fiscal 2026, up from a $3.9 billion framework at the start of the year. Management cites roughly 30% net income growth for the year. The initial fiscal 2027 outlook calls for:
- about $4.425 billion in revenue;
- a 6.0-6.1% net income margin;
- up to 27 openings, including 11-13 Flower Child units.
Flower Child earns that expansion with an 11% comp and a 20.2% mature margin. Even so, the guide is deliberately conservative. Management anchored fiscal 2027 to its historical 25-35 basis-point annual margin-expansion algorithm and modeled flat traffic for the capacity-constrained holiday weeks. The durability of social-media-driven traffic, including viral items like the Cajun salmon, and repeat behavior among new younger guests remain open questions. Fiscal 2027 will also face difficult comparisons. Cheesecake Factory openings for 2026 were trimmed to as many as five.
Dilution is a less obvious cost of the stock's success. With shares trading above the conversion price on the 2030 convertible notes, diluted share count rose to 51.5 million from 48.6 million a year ago. Management expects it to reach about 52-52.5 million, which will mute per-share leverage going forward.
The market had largely anticipated better news. Shares closed at $110.13 ahead of the release, up 18.5% from the open after the July report and about 40% above the 200-day moving average. They had pulled back about 7% from a 52-week high of $118.63 set on October 16. Investor sentiment improved from 0.08 to 0.18, a meaningful shift but still only moderately positive. The Whisper number sitting below consensus suggests the crowd was not braced for a beat of this size. Momentum and AVWAP trend readings are positive, though the price trend is neutral, consistent with a stock that ran hard and then consolidated into the print.
The bottom line is that Cheesecake Factory produced a genuine, traffic-led inflection in its core brand and converted it into a clean beat and a higher multi-year earnings framework. Bears still have legitimate ammunition. North Italia's margins are eroding, incremental flow-through has thinned, convertible dilution is rising, and a social-media-fueled surge has yet to prove its staying power. With the stock already well extended above long-term trend, the next leg likely depends on whether traffic holds against tougher comparisons rather than on another headline surprise.
Read our earnings preview for The Cheesecake Factory Incorporated: https://www.earningswhispers.com/article/CAKE/20746
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 22 min | |
| 3 hours | |
| 4 hours | |
| 4 hours | |
| Oct-27 | |
| Oct-27 |
Cheesecake Factory Logs Higher Revenue After Double-Digit Growth at Namesake Restaurants
CAKE
The Wall Street Journal
|
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-21 | |
| Oct-12 | |
| Oct-10 | |
| Oct-06 | |
| Oct-01 |
