Enphase Misses On Stalled Sell-Through And Guides Q4 Sharply Lower As The AI Data Center Pivot Carries The Story
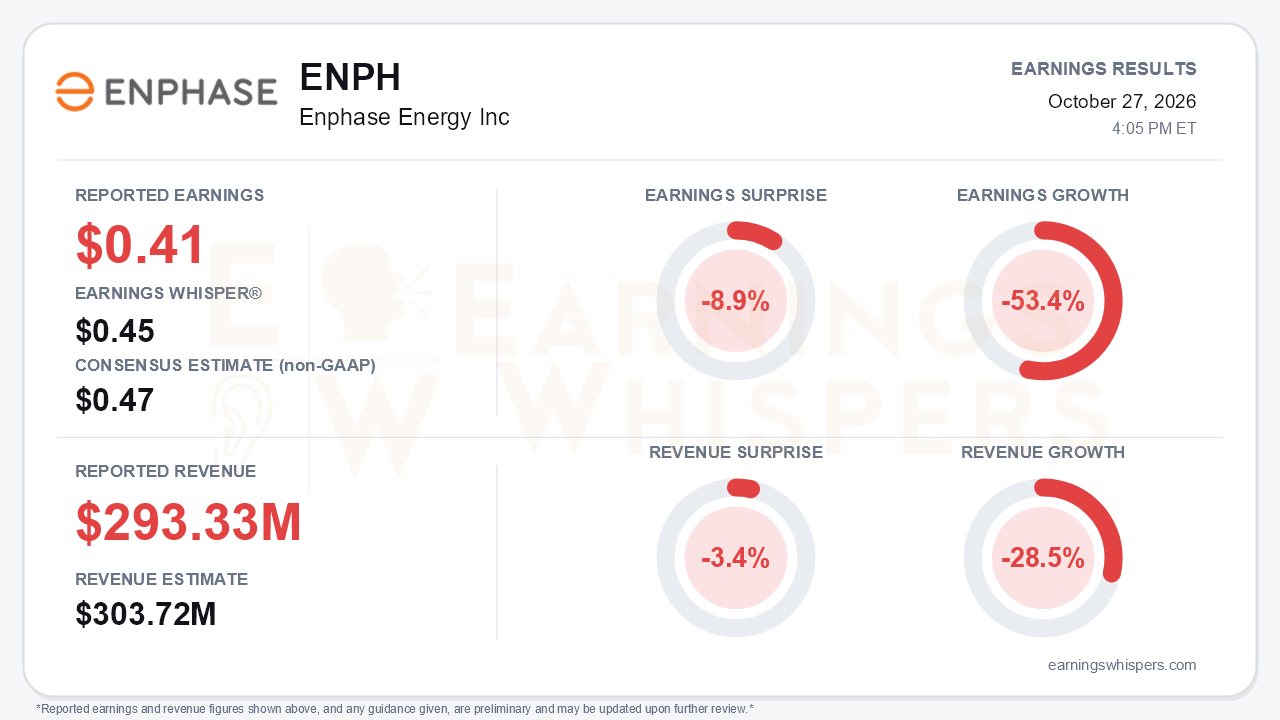
Enphase Energy (NASDAQ: ENPH) reported third-quarter non-GAAP earnings of $0.41 per share, missing the $0.47 consensus by 8.9% and falling short of the $0.45 Earnings Whisper number. Revenue of $293.3 million missed the $303.7 million consensus by 3.4%. Earnings fell 53.4% year over year and revenue dropped 28.5%. The miss itself matters less than what came with it: a fourth-quarter revenue outlook of $225 million to $255 million, well below expectations. That guide implies the core residential business is still contracting. Management increasingly pointed investors toward 2027 and beyond, where a solid-state transformer for AI data centers is becoming the centerpiece of the bull narrative. That is the central tension. The near-term business is deteriorating while the long-dated optionality is getting more interesting.
The quality of the quarter deserves scrutiny from both directions. On one hand, non-GAAP EPS absorbed a $0.14 hit from investment impairments, which management did not strip out. That makes the bottom-line miss look worse than core operations alone would suggest. On the other hand, the operating picture offers little comfort. Revenue was essentially flat sequentially and landed at the low end of the $290 million to $320 million guide. Even that result leaned on $85.0 million of safe harbor revenue, nearly 30% of the total. Non-GAAP operating income was $53.6 million, down from $123.4 million a year ago. Non-GAAP gross margin slipped to 45.0% from 46.8% in the second quarter on mix, even as the tariff drag eased to 1.3 points from 2.0 points. The GAAP comparison is noisy: second-quarter GAAP margin of 60.0% was inflated by tariff refunds. Cash generation was the clearest warning sign. Operating cash flow was roughly $0.1 million and free cash flow was negative $11.4 million. That compares with $25.9 million in the second quarter and $83 million in the first. The balance sheet remains a cushion, with $931.8 million in cash and securities after retiring the 2026 convertible notes.
The call explained why the numbers stalled. Global sell-through rose just 1% sequentially against management's expectation of roughly 10%. U.S. sell-through was down 35% year over year amid high rates and the expiration of the Section 25D credit. Europe reversed sharply after a strong second quarter. Revenue there fell 11% and sell-through dropped 12%, with France particularly weak as its feed-in tariff ends. Management's tone shifted from describing stabilization last quarter to acknowledging no meaningful recovery. It also flagged that U.S. residential could decline again in 2027.
The forward metrics were cut nearly across the board:
- **Revenue:** The fourth-quarter guide assumes roughly a 10% sell-through decline plus about $20 million of undershipment.
- **Safe harbor:** Expected safe harbor revenue was trimmed to $51.2 million from $61.2 million previously indicated.
- **Batteries:** Battery shipments of 129.9 MWh missed the 130-150 MWh guide, and the fourth-quarter guide drops to 100-120 MWh.
- **Margin:** Non-GAAP gross margin is guided to 40%-43%, pressured by an 8%-9% U.S. battery price cut and freight costs.
The call did preserve a credible diversification story. The IQ SST transformer achieved a 13.8 kV-to-800 VDC demonstration. The pipeline more than doubled to over 50, including a leading hyperscaler and a global AI computing leader. Management cited roughly $1 billion of revenue potential by 2030, but customer pilots are not slated until 2027 and commercial shipments until 2028. Nearer-term growth drivers are scaling:
- **Propel lease program:** Now in 13 states with about 350 installers and more than 300 originations per week, up from roughly 200.
- **U.S. commercial:** Sell-through rose 50% sequentially, with commercial revenue targeted to grow from about $30 million this year to more than $100 million in 2027.
- **New launches:** The C80 commercial battery and a bidirectional EV charger with three U.S. automakers are both due to ramp in 2027.
Management sketched an informal 2027 framework of roughly $800 million in core revenue plus about $200 million from growth drivers. That framework implies the new businesses must offset a core that is no longer growing. Propel's expansion also depends on its partner SolSource continuing to raise capital.
Investor sentiment entering the report remained negative but improved modestly, moving from -0.13 to -0.06. That suggests expectations were low rather than hopeful. Price action reinforces that read. Shares closed at $30.36 ahead of the report, down 21.9% since the open after the July release and 26.1% below the 200-day moving average of $41.09. The stock sat just 6.2% above its October 15 inter-earnings low of $28.59, having surrendered the August spike to $43.28. Price and AVWAP trend readings remain negative. In effect, the market had already been pricing core weakness, but not necessarily a guide this far below the third-quarter range.
The bottom line is that Enphase delivered a soft quarter and a weaker outlook. Sell-through, margins, battery volumes and cash flow are all moving the wrong way, and the impairment only partly explains the earnings miss. Bears have legitimate ammunition in a residential business that management itself no longer describes as stabilizing. The AI data center transformer, commercial products and Propel give bulls a real narrative. Still, those opportunities sit mostly in 2027 and 2028, while the deterioration is happening now.
Read our earnings preview for Enphase Energy Inc: https://www.earningswhispers.com/article/ENPH/20752
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-21 | |
| Oct-14 | |
| Oct-12 | |
| Oct-12 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 |
