Snap's Profit Turn Faces Its First Test As World Cup Ad Boost Fades
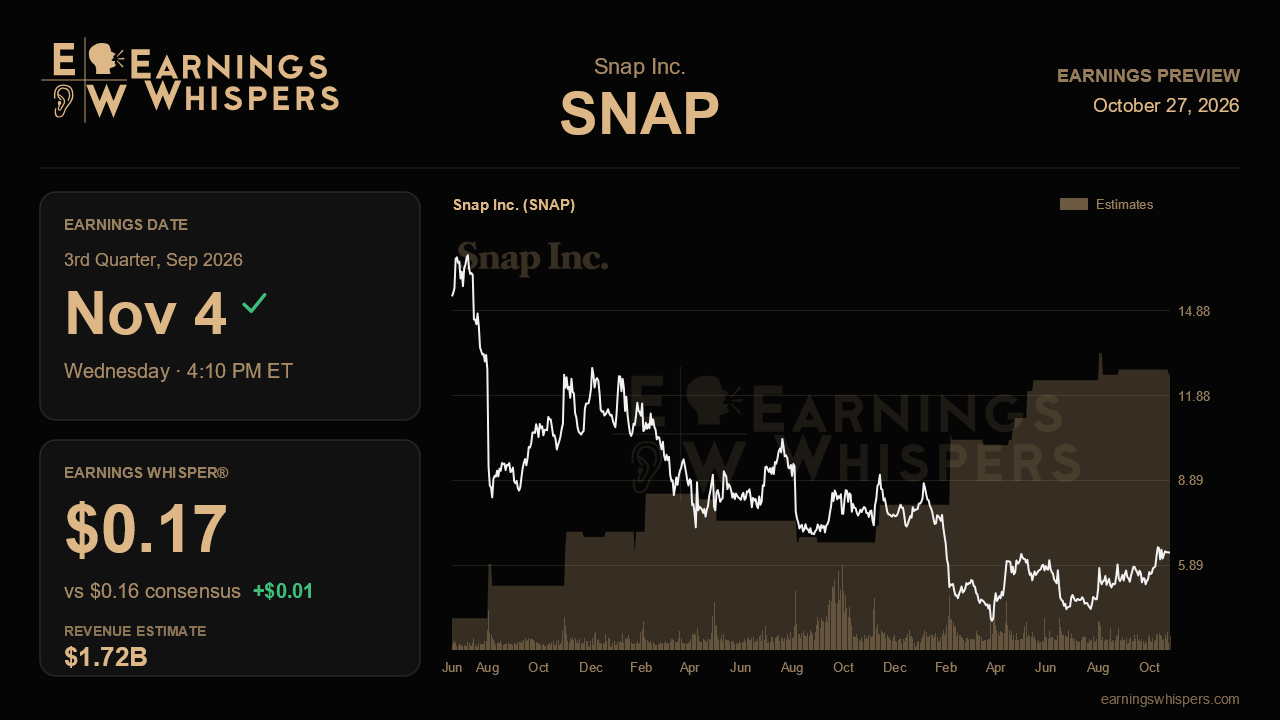
Last quarter Snap finally sounded like a company whose turnaround had arrived. Revenue growth jumped to 19%, gross margin widened by seven points from a year earlier, and management roughly doubled its adjusted EBITDA outlook while naming free cash flow per share as its main financial goal. The third-quarter report, due after the close on November 4, is the first real check on whether that inflection can last once a one-time lift from the World Cup drops out of the advertising comparison.
Wall Street expects earnings of $0.16 per share on revenue of $1.72 billion, which would be about 14.2% growth from the $1.51 billion reported a year ago. That is a clear slowdown from the second quarter's pace, but still solid, and better than the roughly 10% growth Snap posted through much of last year. The revenue estimate sits at the midpoint of management's $1.70 billion to $1.74 billion range. When the guidance came out, consensus sat at the low end, so analysts have since moved up toward the middle. That shift raises the bar a little: matching the guide is no longer enough to impress. The Earnings Whisper of $0.17 is only a penny above consensus, so it signals modest optimism rather than a big hidden expectation. On profit, the key comparison is the swing from a $0.10 loss last quarter and a $0.06 loss a year ago. A positive result would support management's push toward sustained net income in 2027.
The most important line item is EBITDA. Snap guided to $300 million to $350 million, up sharply from its $175 million to $200 million outlook a quarter earlier. If it lands in or above that range, it would confirm that the April restructuring, worth more than $500 million in annual savings, is doing real work. In the second quarter, total adjusted costs grew just 4% while revenue grew 19%. The counterweight is infrastructure spending, which management raised to $1.65 billion to $1.70 billion for the year to fund AI and machine learning. Investors should look for signs that this spending is paying off through better ad results. Last quarter brought conversions up 56%, cost per purchase down 18%, and direct-response product revenue up 43%. Continued gains there would suggest the higher compute bill is buying growth rather than simply eating into margins.
The mix of revenue matters almost as much as the total. Advertising grew only 9% in the second quarter even with World Cup help, so most of the reacceleration came from Other revenue. That bucket, driven largely by subscriptions such as Snapchat+ and the higher-priced Lens Plus tier, reached $316 million, up 85%. Fewer than 3% of monthly users pay today, and management sees room to reach the 7% to 12% common in the industry. Further sequential gains would show that this second engine can cover for softer ad growth. Two other items are worth tracking. North American daily users steadied at 92 million but did not grow, which matters as youth-safety trials and age-verification rules approach. Early signals on Specs, the hardware unveiled in September after strong pre-order demand, could also add to the longer-term story, though they are unlikely to move this quarter's numbers.
Expectations have clearly risen. The stock has gained 19% since the last report while the S&P 500 was roughly flat, and it now trades at $6.34, well above its 200-day moving average of $5.50. Its trading range since the last report is higher than the prior quarter's, though shares remain about 7% below the post-earnings high of $6.85, so this is not a breakout setup. Sentiment has improved to 27.8% bullish from 15.7% before the last report.
The central question is whether Snap's improvement is durable rather than a one-quarter event. If EBITDA comes in at the upper end of guidance, subscriptions keep compounding, and the fourth-quarter outlook implies advertising holding up without World Cup help, the free cash flow story gains credibility. A result that only meets the midpoint, paired with soft ad growth or rising infrastructure costs, would test a rally that has already priced in a good deal of the good news.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-23 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-14 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-08 | |
| Oct-08 | |
| Oct-06 | |
| Oct-02 | |
| Oct-02 |
