Robinhood Beats Consensus But Misses The Whisper As Revenue Growth Slows To 12% And Prediction Markets Offset A Crypto Collapse
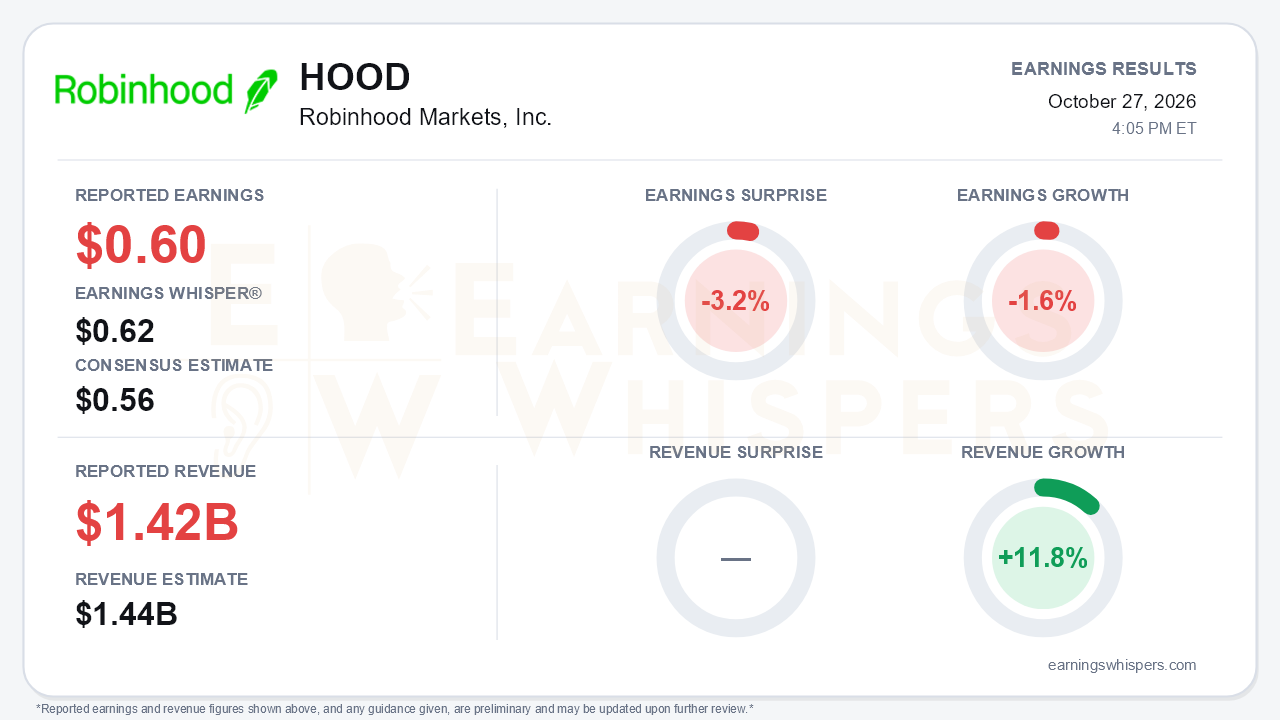
Robinhood (NASDAQ: HOOD) reported third-quarter adjusted earnings of $0.60 per share, above the $0.56 consensus but short of the $0.62 Earnings Whisper number, a 3.2% miss against the whisper. Revenue reached a record $1.424 billion, up 11.8% year over year, but trailed the $1.44 billion consensus by 1.1%. Earnings fell 1.6% from a year ago. The central tension is the pace of growth. Revenue growth fell to 12% from 32% in the second quarter, and adjusted EBITDA growth fell to 9% from 35%. Robinhood is still setting records, but the growth rate that supported the stock earlier in the year has slowed sharply, and the beat against consensus does not change that.
The quality of the quarter needs some unpacking. GAAP diluted EPS fell 16% to $0.51, including $0.07 of mark-to-market losses tied mainly to Robinhood Ventures Fund I. The bigger hidden drag was taxes. Pre-tax income slipped only 1% to $625 million, but the tax provision nearly doubled to $149 million from $78 million, cutting net margin to 33% from 44%. The newly introduced adjusted EPS measure strips out the investment losses, and it shows a better sequential picture: $0.60 versus $0.50 in Q2. Investors should note, though, that management debuted this metric in a quarter when it flatters the comparison. Operating expenses rose 16%, faster than revenue. Credit-loss provisions jumped to $71 million from $26 million as the Gold Card book grows, and operations expense more than doubled on Trump Accounts and Rothera costs. Adjusted EBITDA margin held at 57%, in line with Q2 but slightly below the year-ago 58%.
The revenue mix is changing quickly. Event contracts revenue rose more than sixfold to $173 million, now larger than both crypto ($120 million, down 55%) and equities ($121 million, up 41%). Options revenue grew 31% to $399 million. Equity notional volume, options contracts and the margin book all rose roughly 50% or more to records. Net interest revenue fell 9% on lower securities lending and short-term rates. Other revenue jumped 61% on Trump Account service fees and Gold subscriptions. Rothera, the prediction-market joint venture with Susquehanna, became the 14th business above $100 million in annualized revenue in its first full quarter, and non-sports volume rose to 30% of its mix from 15%. On the call, analysts focused on softer areas:
- Take rates came in lighter than expected.
- Monthly active users and actives as a share of funded accounts weakened.
- Net funded account adds fell back toward first-quarter levels after roughly 1 million in Q2.
- Q3 net deposits of about $16 billion trailed Q2's $22 billion.
The forward picture is mixed. October net deposits had already topped $13 billion, but $6 billion came from the Dell family's Trump Accounts contribution, so the underlying run rate is less dramatic than the headline. Year-to-date deposits above $68 billion already exceed the 20% annual growth target. October trading is softer: equity, options and crypto daily volumes are running about 5% below Q3 with tighter spreads, while event contract volumes are up about 10%. Management trimmed the top of its 2026 adjusted operating expense and SBC outlook by $25 million to $2.675 to $2.75 billion. However, it also flagged rising investment in Robinhood Chain, Trump Accounts and the credit card heading into 2027.
The catalyst list is long:
- Robinhood Chain mainnet, which generated about $50 million in gross fees in its first quarter. The release cites over $80 billion of DEX volume while the call cited over $100 billion. Management acknowledged fees were helped by temporary congestion and said it is not prioritizing chain monetization.
- An equity stake in a Crypto.com prediction-market partnership.
- Regulatory approvals in Dubai and Singapore.
- U.S. perpetual futures and 24/7 equity trading.
Rate exposure remains a real risk, with each 25-basis-point move worth about 1.5% of revenue.
The market setup is more complicated than the consensus beat implies. Shares were $92.84 heading into the report, just 2.1% above the opening price after the July report and 0.4% below the 200-day moving average of $93.25. That flat result hides a full round trip: the stock rallied to an inter-earnings high of $126.74 on September 23, then gave back nearly all of it and now sits 26.7% below that peak and 10.9% above the July 31 low. Investor sentiment improved only slightly, from essentially zero to 0.0246, leaving expectations roughly neutral rather than euphoric. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while AVWAP remains negative.
The bottom line is that Robinhood delivered a record quarter with real evidence of diversification. Prediction markets, Gold, banking and Trump Accounts are filling the hole left by crypto and lower interest income. But the miss against the whisper, the revenue shortfall and a sharp slowdown in year-over-year growth give bears legitimate ammunition. Softer October trading, rising investment spending and a new adjusted metric that flatters the comparison add to that case. The growth story remains credible, but it now depends more on newer businesses scaling than on the trading activity that drove the first half.
Read our earnings preview for Robinhood Markets, Inc.: https://www.earningswhispers.com/article/HOOD/20764
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 2 hours | |
| 3 hours | |
| 4 hours | |
| 5 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours |
Robinhood Q3 Highlights: Trump Accounts, Prediction Markets Help Offset Crypto Weakness
HOOD HOOD -7.63% AH
Benzinga Prediction Markets
|
| 7 hours | |
| 7 hours | |
| 7 hours | |
| 10 hours |
