GE Vernova Beats And Raises Again, But Slowing Order Intake Explains A Wary Market
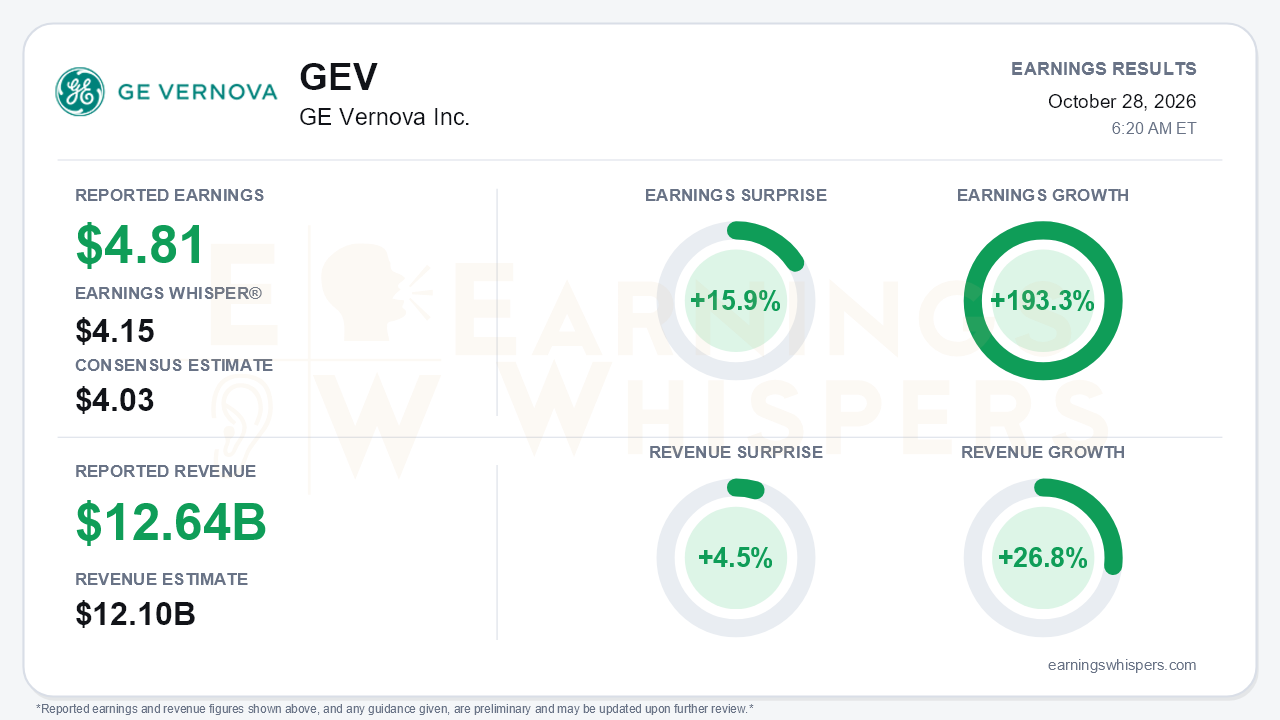
GE Vernova delivered the kind of quarter that is hard to argue with on the surface. Earnings of $4.81 per share topped the $4.03 consensus by 15.9% and cleared the $4.15 Earnings Whisper number by a comfortable margin. Revenue of $12.642 billion beat the $12.10 billion estimate by 4.5%. Earnings grew 193.3% year over year and revenue rose 26.8%. Management also raised full-year revenue, margin and free cash flow guidance for the third consecutive quarter. The central tension is that the stock entered the report down 12.3% since the prior earnings open, and investor sentiment had soured. That suggests the market is less focused on what GE Vernova is shipping today than on whether the pace of new commitments can be sustained.
The quality of the beat holds up well. Organic revenue growth accelerated to 18% from 12% in the second quarter and 7% in the first, so the top line is gathering speed rather than plateauing. Adjusted EBITDA more than doubled to $1.9 billion, with margin expanding 690 basis points organically to 15.4%. GAAP net income was $1.3 billion, a 10.2% margin. The margin story is concentrated in Power, where EBITDA margin reached 21.4% in what is typically the seasonally weakest quarter. That compares with 18.8% in the second quarter and well above the 17-18% management had guided for the period. This is the inflection the bulls have been waiting for, as higher-priced turbine orders booked over the past two years begin flowing through revenue. Electrification margin also improved, to 19.1% from 18.4%. Free cash flow of $5.4 billion pushed cash to $16.8 billion, up about $4 billion sequentially.
Forward indicators remain enormous in absolute terms. Orders of $29 billion rose 96% organically, and backlog climbed $20 billion sequentially to $197 billion. Management now expects to cross $200 billion in the fourth quarter, a year earlier than it guided as recently as last quarter. Gas equipment under contract grew to 122 GW, with at least 130 GW targeted by year-end. Slots are now sold into 2032, and 2026 gas order pricing is running roughly 50% above 2025. Full-year guidance now calls for:
- revenue of $46.5-47.5 billion;
- adjusted EBITDA margin of 13.5-14.5%;
- free cash flow of $16-17 billion, up from $11.5-12.5 billion just one quarter ago.
That free cash flow figure far exceeds the implied full-year EBITDA. This points to heavy working-capital inflows, likely customer deposits, rather than earnings power alone. That is an inference, but it matters when judging how repeatable the cash stream is.
The second derivative is where bears have legitimate ammunition. Gas GW signings slowed to 11 GW from 20 GW in the second quarter and 21 GW in the first. Management also flagged lower gas pricing per kW in the fourth quarter on mix, with fewer aeroderivatives and more 50Hz units. Electrification orders fell 9% year over year to $5.4 billion, down sequentially from $6.3 billion and $7.1 billion, which management attributed to a tough Saudi comparison. More notably, data center electrification orders dropped to $1.4 billion from $2.7 billion. Services revenue growth cooled to 6% from 10%, as fulfillment capacity is diverted toward equipment shipments. Wind turned profitable in the quarter with $72 million of EBITDA and settled the Vineyard Wind dispute. Even so, the full-year wind loss guidance widened to $400-500 million.
Capital allocation added both catalysts and risks. The buyback authorization doubled to $20 billion after roughly $9.9 billion was repurchased at an average near $635. The $9 billion Trench Group acquisition extends the company into high-voltage components at an attractive roughly 36% projected 2028 EBITDA margin. However, it will be funded with about $4.5 billion of new debt and is not expected to close until late 2027, pending regulatory approvals. CFO Ken Parks and the wind leader will also transition out in January 2027. On the product side, the company landed its first MVUPS order with a hyperscaler, an SST award, an NRC construction permit for the Clinch River SMR, and an SMR technology selection in Sweden.
The market setup is more complicated than the surprise implies. Investor sentiment moved from slightly negative (-0.07) to more clearly negative (-0.23) ahead of the report. Shares sat 4.7% below the 200-day moving average and 18.6% below the August inter-earnings high of $1,099.66. The stock had rebounded 12.4% off an October 23 low of $796.42. Trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP remain negative.
The bottom line is that GE Vernova's reported results, margins and guidance are accelerating, with Power margins now validating the pricing thesis. The stock's pullback, however, reflects real deceleration in new gas signings, electrification and data center orders, and services growth, along with added leverage and management turnover. Investors will need to see fourth-quarter orders reaccelerate before the backlog story fully offsets those concerns.
Read our earnings preview for GE Vernova Inc.: https://www.earningswhispers.com/article/GEV/20850
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 22 min | |
| 1 hour | |
| 2 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 4 hours | |
| 5 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours |
GE Vernova to Buy High-Voltage Grid Equipment Manufacturer for $9 Billion
GEV
The Wall Street Journal
|
| 7 hours | |
| 7 hours | |
| 8 hours | |
| Oct-27 |
