GE HealthCare Beats And Raises As Growth And Margins Accelerate, But Cooling Orders Temper The Outlook
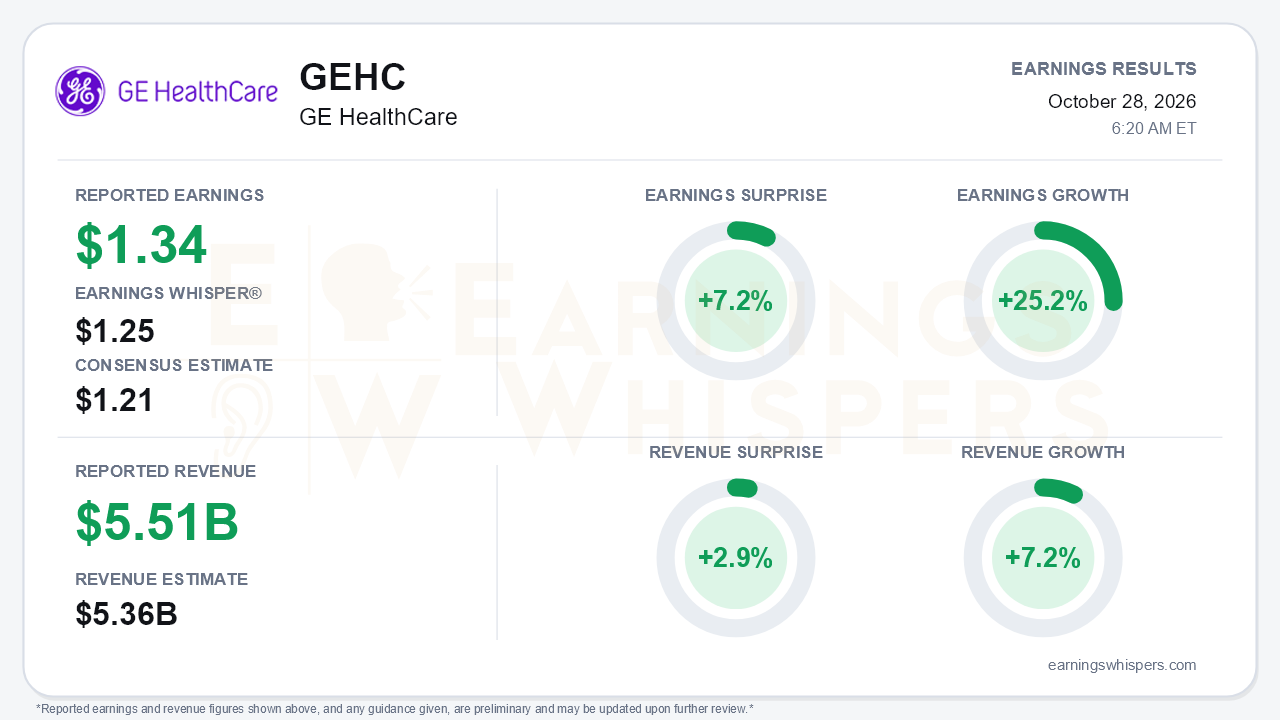
GE HealthCare (NASDAQ: GEHC) delivered its cleanest quarter of the year. Adjusted EPS of $1.34 topped the $1.21 consensus by 7.2% and cleared the $1.25 Earnings Whisper number. Earnings grew 25.2% year over year, and revenue of $5.513 billion rose 7.2%, beating the $5.36 billion consensus by 2.9%. More important than the beat was the acceleration. Organic revenue growth reached 6.2%, up from 3.5% in the second quarter and 2.9% in the first. The adjusted EBIT margin expanded 180 basis points to 16.6%, after contracting in each of the first two quarters. Management raised full-year guidance for the first time this year. The central tension is that this improvement in the income statement came alongside a clear slowdown in orders, the metric that best signals where revenue goes next.
The quality of the beat holds up better than a quick glance at the GAAP line might suggest. Diluted EPS of $1.36 benefited from a foreign tax audit settlement, which pushed the GAAP effective tax rate down to 17.1% from 27.8%. The adjusted figure strips that benefit out. The adjusted tax rate was 22.0%, essentially unchanged from 21.8%, and IEEPA tariff refunds were also excluded from adjusted results. That means the $0.27 adjusted EPS improvement rested mainly on operations. Volume, price, cost productivity and a favorable year-over-year net tariff comparison drove it, partly offset by inflation. Every segment expanded margins. Free cash flow jumped to $793 million from $483 million. That cash figure does include a $55 million tariff refund, which will become a difficult comparison in 2027.
The biggest operating swing came in Patient Care Solutions. Organic revenue there grew 8.8%, and the segment margin rose 480 basis points to 8.6%. In the second quarter, PCS had posted a 13.5% organic decline and negative EBIT. Pharmaceutical Diagnostics remained the growth and profit engine, with 13.8% organic growth and a 29.9% margin. Within that segment, Flyrcado is ramping quickly to roughly 680 weekly doses, up from 545 in the second quarter and 220 a year-end ago, and the $500 million 2028 target was reaffirmed. Advanced Imaging grew a steadier 4.5% organically, with 130 basis points of margin expansion. China returned to reported growth of 7%, although the call indicated that this was largely currency-driven.
The softer side of the report is demand. Organic orders grew 4.0%, down sharply from 11.1% in the second quarter. Book-to-bill fell to 1.03 from 1.15, the lowest level since early 2024. Backlog slipped sequentially to $23.7 billion from $23.9 billion, though it remains up 12% year over year. The guidance raise also deserves scrutiny. The new adjusted EPS range of $4.95-$5.05 sits at or below the original February guide of $4.95-$5.15, which was cut in the first quarter. The margin raise lifts only the low end of the range. In addition, the implied fourth-quarter organic growth of 3-4% looks soft against the third quarter's pace. Management attributed that partly to a roughly $45 million PCS product-hold comparison. Bears have other legitimate ammunition as well:
- PCS chief Jeannette Bankes is departing while a strategic review of the business continues.
- A generic Omnipaque entrant is targeting $50 million-plus in sales.
- Section 232 tariffs remain uncertain.
- Memory-chip and oil inflation persist.
- China volume-based procurement is expanding.
On the catalyst side, the planned $945 million cash acquisition of SOFIE Biosciences would add about 1% of revenue. It would also give GE HealthCare a U.S. PET radiopharmacy "final mile" footprint and a Phase III FAPI tracer, and management expects the deal to be accretive to margin and EPS. Closing is expected in the first half of 2027. Photonova Spectra gained a CE Mark, StarGuide GX awaits FDA clearance, and management flagged RSNA as a pivotal product showcase for 2027-28. The dividend was raised 14%. Funding SOFIE will draw on a balance sheet carrying $10.0 billion of debt against $2.9 billion in cash.
Investor sentiment improved meaningfully heading into the report. It rose from -0.27 after the July release to roughly neutral at -0.01. Expectations had moved from skeptical to balanced, not to euphoric. The stock was little changed in price terms, up 2.6% since the open after the prior report, at $71.11. That leaves shares about 1.5% above their 200-day moving average. They sit near the middle of an inter-earnings range that ran from a $63.00 low in mid-September to a $75.65 high in August. The Earnings Whispers trend signals for sequential growth, momentum and AVWAP are positive, while price trend is neutral. That mix fits a stock that has recovered from its September low without reclaiming its summer peak.
The bottom line is that GE HealthCare showed accelerating revenue, broad margin expansion and a credible PCS rebound. That is enough to keep the improving earnings story intact and justify the guidance raise. The cooling in orders, a slipping backlog and a modest fourth-quarter implied pace, however, mean the next leg depends on demand reaccelerating rather than on continued execution alone.
Read our earnings preview for GE HealthCare: https://www.earningswhispers.com/article/GEHC/20849
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 3 hours | |
| 3 hours |
GE HealthCare Stock Eyes Breakout On Best Earnings Since Spinoff
GEHC +7.14%
Investor's Business Daily
|
| 5 hours | |
| 6 hours | |
| 7 hours | |
| Oct-20 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-12 | |
| Oct-07 | |
| Oct-07 | |
| Oct-05 | |
| Oct-05 |
