Stellantis Beats Lowered Bar, But Stalling Growth And A Deepening European Loss Undercut The Cost-Savings Story
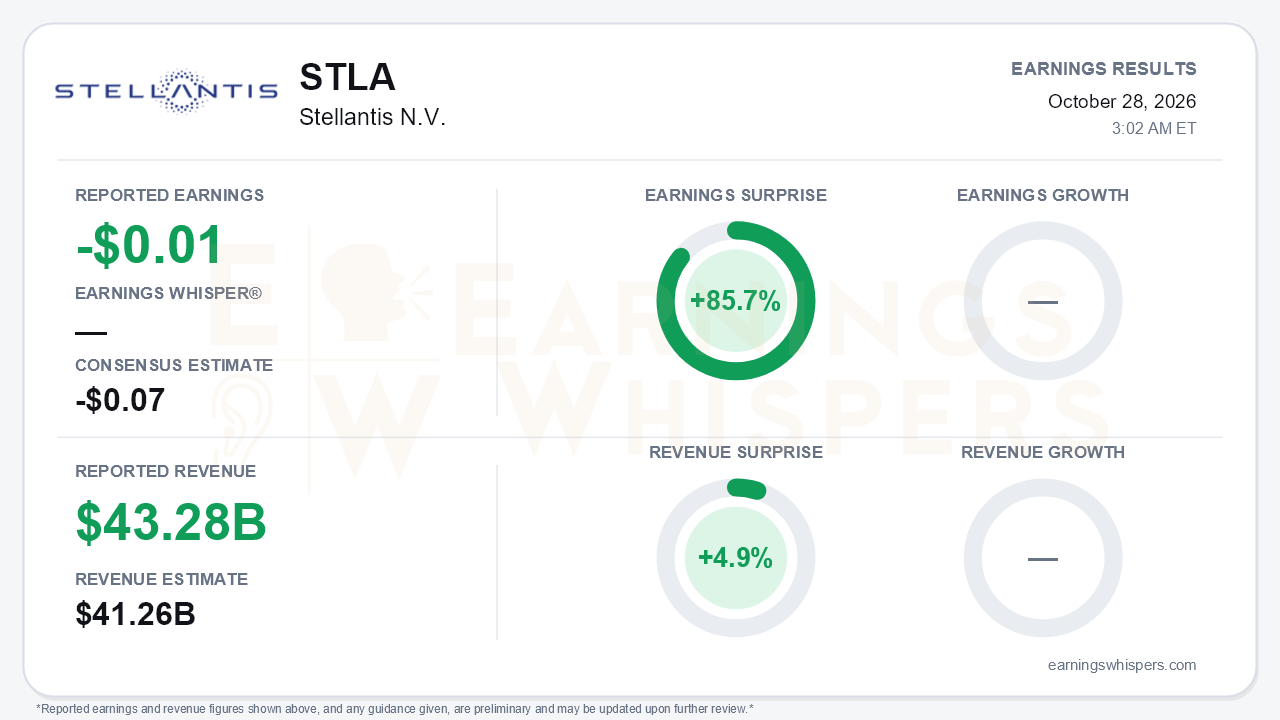
Stellantis cleared a very low bar in the third quarter. The automaker posted an adjusted loss of $0.01 per share, well ahead of the -$0.07 consensus for an 85.7% surprise. Revenue of $43.28 billion topped the $41.26 billion estimate by 4.9%. In reporting currency, the adjusted diluted loss narrowed to €0.01 from €0.04 a year ago. Net revenues edged up 1% to €37.6 billion. Headline beats on a pre-flagged soft quarter are not the story, though. The central tension is that management's cost program is gaining credibility while the top line, margins and Europe are moving the wrong way.
The quality of the quarter deserves scrutiny. The GAAP net loss improved 90% to €0.5 billion, but that comparison flatters. Q3 2025 carried a €3.25 billion warranty-estimate change and €1.7 billion in program cancellations. This quarter still absorbed €587 million of excluded items, including a €223 million Takata recall campaign, a €118 million Leasys write-down and restructuring costs. Adjusted operating income rose to €256 million, a 0.7% margin and up 50 basis points year over year. Sequentially, however, margin has slid from 2.5% in Q1 to 1.8% in Q2 to 0.7% now. Revenue growth has decelerated from 6% to 13% to just 1%, and shipments slipped 1% after double-digit gains in the first half. Industrial free cash flow was negative €4.0 billion, €0.3 billion better than a year ago but still a heavy seasonal drain. Industrial net financial position fell to €5.4 billion from €6.7 billion at year-end.
The regional split is stark. North America swung to a €64 million profit from a €475 million loss, an improvement of €539 million. Positive net pricing of €421 million and industrial savings drove the gain. Quality also kept improving, with North America three-month-in-service metrics better by 43%. Even so, the region's 0.4% margin fell from 1.6% in each of the first two quarters. Planned Jeep downtime explains part of that decline, and it breaks the sequential margin improvement management had signaled earlier in the year. Enlarged Europe is the bigger problem. AOI deteriorated to a €311 million loss from €94 million in Q2 and breakeven in Q1, as negative pricing and BEV mix overwhelmed 10% shipment growth. Growth there is coming at the expense of profitability.
The call's genuine positive was cost. Industrial cost contributed €828 million year over year. Management upgraded its Value Creation Program language from "on track" to "will exceed" both the €2.4 billion 2027 run-rate and the €6 billion 2028 target. It also guided Q4 savings to the mid-hundreds of millions of euros, roughly double Q3. Several other estimates moved favorably:
- Net tariff costs were lowered to about €1 billion, from €1.0–1.2 billion previously.
- Expected 2026 cash payments tied to H2 2025 charges were trimmed to about €1.6 billion from €2 billion.
- Capex plus R&D was narrowed to about 6.5% of revenue.
Management reaffirmed full-year guidance, which implies a much stronger Q4 to reach a low-single-digit margin from a 1.7% year-to-date pace. It also reaffirmed positive industrial free cash flow in 2027. Product catalysts include the Ram Rumble Bee selling out its initial allocation in 24 hours, Leapmotor B10 production at Zaragoza and the new Dongfeng technology JV.
Bears have legitimate ammunition, however. Memory-chip cost pressure remains unquantified and is building into 2027. Commodity inflation of about 1% of revenue is expected to rise as fixed contracts renew. Management also flagged incremental Q4 recall costs. U.S. dealer inventory is up 23% to roughly 368,000 units while floor-plan rates are higher. Management declined to bridge 2027 free cash flow until February, leaving open whether VCP savings will be absorbed by raw-material and chip inflation. The December 10 FaSTLAne 2030/Maserati Day is the next checkpoint.
The market had already priced in deep skepticism. Shares closed at $4.14 ahead of the report, down 27.4% from the $5.70 open after the July release and 38% below the 200-day moving average of $6.67. The stock sat just 5.6% above the 52-week low of $3.92 set on October 23. Investor sentiment weakened from -0.18 to -0.27, a meaningful but not dramatic move deeper into negative territory. Price and AVWAP trend readings remain negative.
The bottom line is that Stellantis delivered a beat against depressed expectations and a more confident cost narrative, but the operating trajectory has not turned. Revenue growth has stalled, margins have compressed for three straight quarters and Europe's losses are widening. The VCP upgrade and lower tariff and cash-charge estimates support the 2026 guidance. Until management shows how savings outrun commodity, chip and recall pressure in 2027, the stock's position near its lows reflects unresolved doubts rather than a mispriced recovery.
Read our earnings preview for Stellantis N.V.: https://www.earningswhispers.com/article/STLA/20880
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 28 min | |
| 34 min | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 3 hours | |
| 3 hours |
Stellantis Stock Jumps on 'Offensive' to Get Jeep Back on Track
STLA +13.04%
The Wall Street Journal
|
| 5 hours | |
| 7 hours | |
| 10 hours | |
| 10 hours | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-22 |
