Teradyne Beats On AI Breadth, But Shrinking Margins And Later Hyperscaler Ramps Complicate The Setup
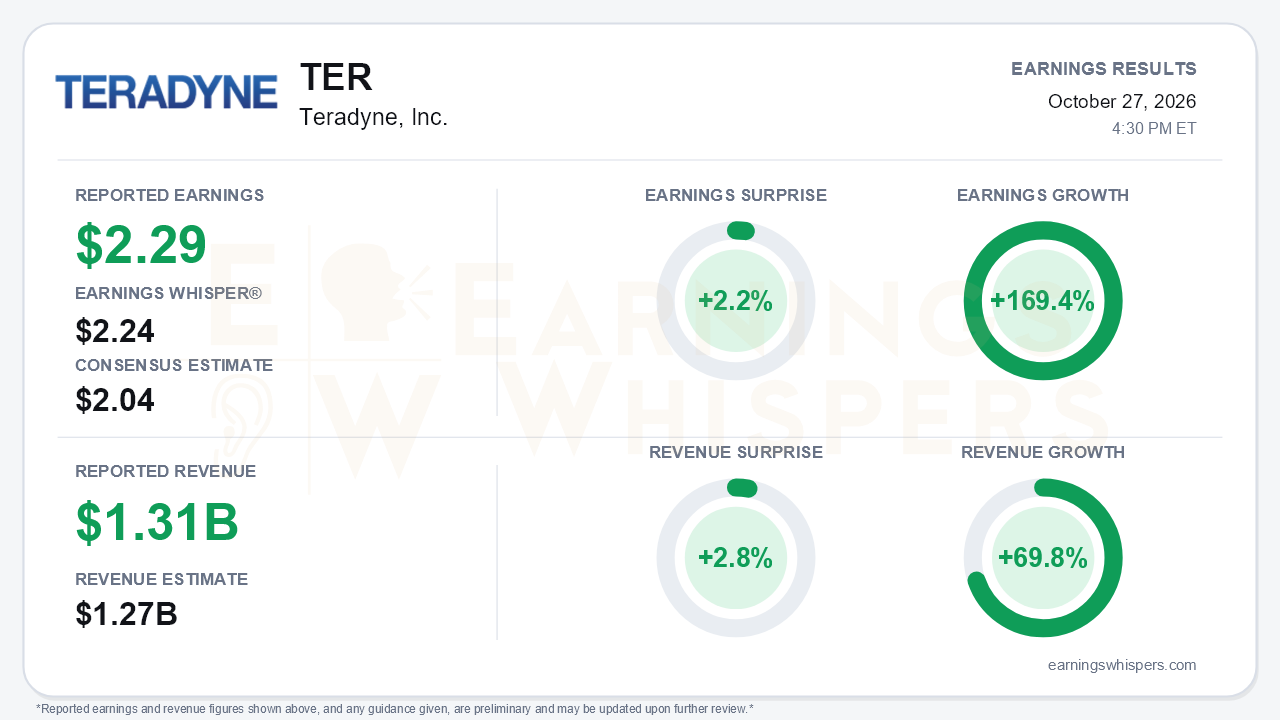
Teradyne (NASDAQ: TER) delivered another quarter that clears the bar on paper. Non-GAAP earnings of $2.29 per share topped the $2.04 consensus and the $2.24 Earnings Whisper number, a 2.2% surprise. Revenue of $1.306 billion beat the $1.27 billion consensus by 2.8%. Year over year, earnings grew 169.4% and revenue grew 69.8%, and results landed above the high end of the company's own guidance. The year-over-year comparison flatters the trajectory, however. Revenue has now sat near a $1.3 billion plateau for three straight quarters, and Q3 was slightly below Q2's $1.329 billion. Non-GAAP EPS has stepped down from $2.56 in Q1 to $2.47 in Q2 and now $2.29. That is the central tension: Teradyne is growing enormously against last year while contracting modestly quarter to quarter.
The composition of the beat matters more than its size. Semiconductor Test contributed $1,072 million. Inside that segment, SOC revenue fell to $676 million from $843 million in Q2 and $882 million in Q1, which management attributed to compute order timing and called the compute low point. The offset came from breadth:
- Memory hit a record $301 million, up from $212 million.
- Integrated Systems Test reached a record $95 million, up from $67 million.
- Product Test climbed to $138 million from $107 million, with a 1.4x book-to-bill.
- Robotics, which went through a roughly 150-person restructuring last year, generated $96 million and turned profitable. Revenue did slip from $100 million in Q2.
The diversification story is real. The mix shift, however, is coming at a cost to profitability. Gross margin eased to 59.1% from 59.8% in Q2 and 60.9% in Q1. Non-GAAP operating margin fell to 31.6% from 33.7% and 37.5%. GAAP results moved with non-GAAP, with GAAP EPS of $2.17 versus $0.75 a year ago, so the adjustments do not distort the picture.
Guidance sharpens both sides of the argument. Q4 revenue guidance of $1.25 billion to $1.35 billion carries a $1.30 billion midpoint, above the prior quarter's $1.25 billion guide midpoint, and implies fiscal 2026 revenue of about $5.2 billion, up more than 60%. Earnings Whispers characterizes the guide as in line. The profit outlook points lower:
- Non-GAAP EPS guidance of $1.95 to $2.25 implies a fourth consecutive sequential decline at the midpoint.
- Gross margin is guided to 57.5% to 58.5%.
- Operating margin is guided to 28% to 30%, below every quarter so far this year.
Management cited 2027 cost inflation and capacity-expansion expenses, and expects memory to digest after its record quarter. Mobile is running below the target model.
The call also brought a timing shift that bears will seize on. Last quarter, management pointed to a first-half 2027 surge in compute. Now the first hyperscaler's next ramp is expected around mid-2027, and the second hyperscaler's capacity buys are expected in the second half, leaving 2027 more back-half weighted. In fairness, the pipeline broadened at the same time. The second hyperscaler moved to fast-follower status and a third entered initial qualification. Management also firmed its 2027 framing, saying Q1 should exceed Q4 and that each 2027 quarter should grow. Visibility has stretched to about two quarters from 13 weeks entering the year. Other catalysts include:
- A planned FormFactor investment and optical test partnership, expected to close in Q4.
- A slate of new products: UltraFLEX Plus instruments for 2027 AI devices, the Magnum E2 DRAM tester and the UR Gen 7 cobot.
- A signal that the $6 billion target model is stale and will be reset against a larger test market on the Q4 call.
The balance sheet shows the strain of building ahead of demand. Inventories rose to $575 million from $380 million at year-end, roughly $200 million over six months by management's count. Management said about half is buffer stock against lengthening component lead times. Q3 operating cash flow of $314 million, less $86 million of capex, yielded free cash flow of about $227 million, down from $378 million in Q2. The release shows $461 million in cash and equivalents, while the call cited $625 million. The higher figure appears to include marketable securities. Buybacks rose to $99 million, and the short-term debt balance from year-end has been repaid.
Investors had already grown wary heading into the print. Earnings Whispers sentiment swung from a moderately positive 0.30 after the July report to a slightly negative -0.08, a meaningful reversal rather than a minor drift. The stock reinforces that caution. At $323.68, shares are 12.0% below the $367.89 open following the prior report and about 7% under the $347.87 200-day moving average. AVWAP readings remain negative, and the price trend is only neutral.
The bottom line is that Teradyne proved its growth no longer hinges on a single compute customer. Memory, interconnect test, product test and a newly profitable robotics unit carried a quarter in which SOC hit its trough. Yet the beat was modest relative to the Whisper number, margins and EPS are guided lower again, and the hyperscaler inflection has slid deeper into 2027. Bulls have a credible multi-engine story and a reset target model ahead. Skeptics can point to three quarters of flat revenue and compressing profitability. Until compute reaccelerates, the narrative will likely turn on whether that breadth can outrun margin pressure.
Read our earnings preview for Teradyne, Inc.: https://www.earningswhispers.com/article/TER/20802
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-27 | |
| Oct-27 | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 |
SpaceX, Anthropic and Nvidia Help Snap Tech Stocks Out of Their Recent Malaise
TER
The Wall Street Journal
|
| Oct-21 | |
| Oct-19 | |
| Oct-16 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-08 |
