Baker Hughes Beats Consensus But Misses The Whisper As Record IET Backlog Pushes Growth Further Out
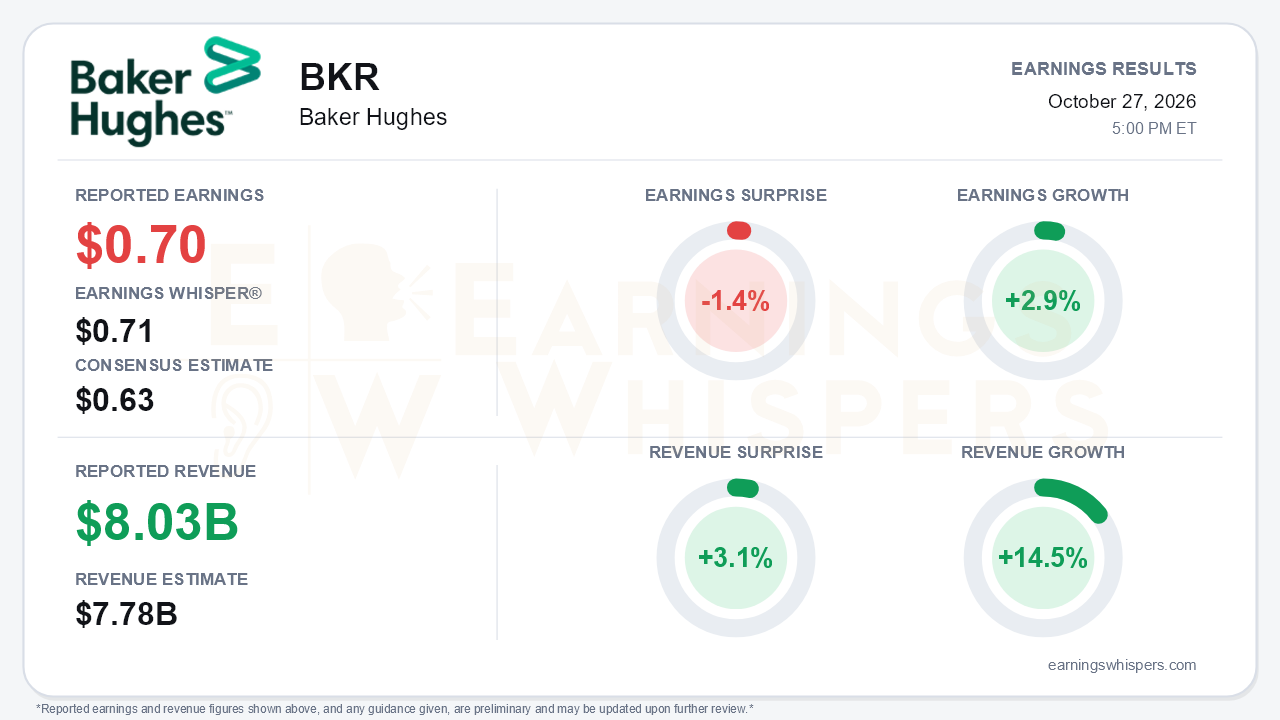
Baker Hughes (NASDAQ: BKR) delivered a quarter in which orders kept surging while earnings growth barely moved. Adjusted EPS of $0.70 cleared the $0.63 consensus but fell 1.4% short of the $0.71 Earnings Whisper number. Revenue of $8.025 billion topped the $7.78 billion consensus by 3.1% and grew 14.5% year over year. Earnings, however, grew just 2.9%. That gap is the central tension. Booking momentum in Industrial & Energy Technology has never looked stronger, yet the first quarter with Chart Industries showed how much acquisition debt and a longer-dated backlog stand between record orders and per-share earnings growth.
The quality of the beat deserves scrutiny. The release attributes most of the year-over-year revenue increase to Chart, which contributed $888 million of revenue and $156 million of EBITDA in roughly 11 weeks after the July 16 close. Excluding that contribution, the legacy business was close to flat on a year-over-year basis:
- OFSE revenue rose 1%.
- IET revenue rose 3%, partly held back by the Precision Sensors & Instrumentation disposition.
Adjusted EBITDA rose 14% to $1.415 billion, but financing costs absorbed much of that gain. Net interest expense jumped to $177 million from $56 million a year ago. GAAP results were weighed down further by $158 million of transaction costs, $143 million of Chart intangible amortization and $25 million of inventory step-up charges. As a result, GAAP EPS fell to $0.41 from $0.61. Free cash flow of $769 million was also down from $1.1 billion in the second quarter, and management cited roughly $200 million of Chart-related costs.
Beneath the headline, the order story remains exceptional. IET booked $5.9 billion, a 1.7 book-to-bill, and RPO reached a record $39.4 billion, up from $37.1 billion in the second quarter and $33.1 billion in the first. Key wins included:
- A 1.1 GW power order from a major U.S. technology company.
- A roughly 500 MW AI infrastructure award.
- Venture Global's Plaquemines expansion and pipeline compression awards.
Data center orders have reached $4.9 billion year to date, up about 500%. Management raised full-year IET order guidance for a third time, to $21.5 to $23.5 billion, and lifted the Horizon 2 target to more than $50 billion. Margins moved the wrong way, though. IET EBITDA margin slipped to 19.7% from 20.6% in the second quarter, below the guidance midpoint, on project timing, mix and inflation. The consolidated margin eased to 17.6% from a record 18.3%, partly due to Chart mix. OFSE was the cleaner surprise, with revenue up 6% sequentially, a meaningful Middle East improvement and margin up 50 basis points to 18.1%.
The forward picture is where bears have legitimate ammunition. Only 33% of combined Gas Technology Equipment and Services backlog is scheduled to convert in 2027, compared with 46% at the same point last year. Management guided 2027 IET organic growth to only low-to-mid single digits and framed overall 2027 growth as more modest. Other cautions included:
- Chart's 0.9 book-to-bill.
- An expected fourth-quarter OFSE decline in the Middle East and North America.
- Tougher Middle East logistics for IET projects.
- Analyst questions about the permitting and financing quality of data center backlog.
On the positive side, management set a new Chart margin target of 22% to 23% by the second half of 2028, and $70 million of the $325 million synergy target has already been actioned. The company also raised its full-year adjusted EBITDA midpoint to $5.265 billion including Chart. Deleveraging is expected to begin in the fourth quarter alongside the Waygate divestiture, with net leverage of 2.5x targeted below 1.5x by the second half of 2028.
The market had not been rewarding the backlog story heading into the print. Shares at $59.00 are down 2.7% since the open following the July report and sit about 1.8% below the 200-day moving average of $60.11. The Earnings Whispers price and AVWAP trend readings are both negative. Investor sentiment edged from slightly negative to slightly positive, but the move was small, and positioning looks essentially neutral rather than enthusiastic. That lukewarm setup fits a company whose orders are compounding faster than its earnings.
The bottom line is that Baker Hughes reinforced a credible multi-year growth narrative in power generation, LNG and data centers, but the quarter did little to close the gap between bookings and earnings. Missing the whisper, compressing IET margins, higher leverage and a backlog that now converts more slowly into 2027 mean the payoff from record RPO is arriving later than the order headlines suggest. Execution on Chart synergies and deleveraging will likely determine whether investors look through that delay.
Read our earnings preview for Baker Hughes: https://www.earningswhispers.com/article/BKR/20741
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 7 hours | |
| Oct-27 | |
| Oct-27 |
Baker Hughes Revenue Lifted by Growing Demand From Energy, Industrial Markets
BKR +5.34% BKR -6.28%
The Wall Street Journal
|
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-23 | |
| Oct-23 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 |
