Vertiv's Blowout Quarter And Fourth Guidance Raise Collide With A Stock That Had Been Priced For Trouble
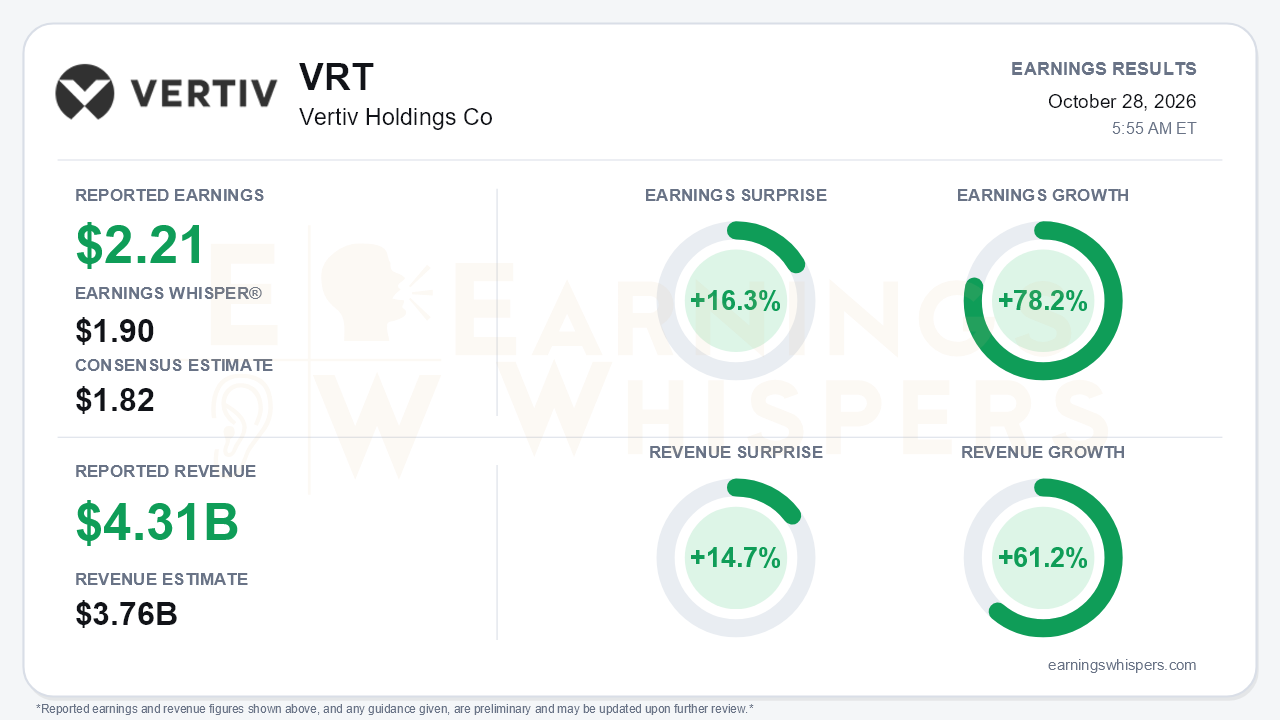
Vertiv delivered the kind of quarter that is hard to argue with on the numbers. Adjusted earnings of $2.21 per share beat the $1.82 consensus by 16.3% and cleared the $1.90 Earnings Whisper number. Revenue of $4.313 billion topped the $3.76 billion consensus by 14.7%. Earnings grew 78.2% year over year, and revenue rose 61.2%, a sharp acceleration from the 24% reported growth (18% organic) posted in the second quarter. GAAP diluted EPS rose 91% to $1.95. The central tension is that this result arrived after investors had spent three months marking the stock down. Shares fell 15.2% from the post-July open, and sentiment flipped from optimistic to pessimistic.
The quality of the beat deserves some scrutiny, though it largely holds up. Management said roughly $100 million to $150 million of revenue delayed from the second quarter's supply-chain timing miss landed in the third quarter, which flatters the sequential comparison. Even after removing that amount, sales still came in comfortably above the company's own $3.75 billion guide. Organic growth reached about 55%, with roughly 6 points added by acquisitions. Adjusted operating margin of 25.2% rose 290 basis points year over year and 70 basis points above guidance, up from 22.6% in the second quarter and 20.8% in the first. The adjustments are modest: intangible amortization, $34.1 million of acquisition-related contingent consideration, and small deal costs.
What changed beneath the surface is geographic breadth. EMEA, a drag all year, swung from a 29% organic decline in the first quarter to 19% organic growth, and its margin expanded 920 basis points to 28%. Management said the EMEA pipeline roughly doubled, with orders up even faster. APAC grew 48% organically and lifted its margin to 17%. The Americas still did the heavy lifting with 66% organic growth. However, its margin was essentially flat at 29.4%, and management attributed weaker incrementals there to capacity-ramp inefficiencies and a product-heavy mix. The headline margin story is strong, but the core region is not yet converting volume as efficiently as the 30%-35% incremental framework implies.
Guidance was raised for the fourth time this year. Full-year targets now call for sales of $14.65 billion (from $14.0 billion), about 38% organic growth (from 31%), adjusted EPS of $7.15 (from $6.70), and adjusted free cash flow of $2.7 billion. Fourth-quarter guidance calls for $4.41 billion in sales, about 50% organic growth, a 25.8% margin, and $2.25 in adjusted EPS. Management also previewed 2027 qualitatively, citing significant above-market organic growth and continued margin expansion. The most striking disclosure was organic orders growth of more than 100% year over year. Management shared it despite a policy, set in February, of not disclosing orders.
Bears still have legitimate ammunition. The fourth-quarter guide implies roughly flat sequential revenue. Management said it will not share orders data going forward, which reduces visibility just as the debate intensifies. Analysts pressed on market chatter about compressor and UPS quality problems, and management acknowledged elevated infant failure rates on new products. That admission matters for a company whose pitch rests on reliability at scale. Inventory has more than doubled since December to $3.29 billion. Third-quarter free cash flow of $652 million, up 50%, trailed the second quarter's $925 million. Deferred revenue rising to $4.12 billion offsets much of that working-capital build, and it signals heavy customer prepayment. Power availability, permitting, and labor remain pacing constraints.
The market setup is more complicated than the surprise implies. Sentiment deteriorated meaningfully, falling from 0.32 to -0.14. Heading into the report, shares sat at $208.56, 22.5% below the 200-day moving average and 30.5% below the August 17 inter-earnings high of $300.30. They were only 11.4% above the October 23 low of $187.24. Executive Chairman Dave Cote's quip that "rumors of our demise" were greatly exaggerated shows management knows it is fighting a narrative, not a numbers problem. The Earnings Whispers trend readings reflect that split: sequential growth and momentum are positive, while price and AVWAP trends remain negative.
The bottom line is that Vertiv answered the second-quarter miss with accelerating growth, broadening regional strength, rising margins, and another across-the-board raise, a combination turnaround skeptics were not positioned for. The fundamental case strengthened materially this quarter. What remains unresolved is trust, specifically product reliability, Americas margin conversion, and reduced orders visibility. Those issues, more than the size of the beat, will likely determine whether the stock's deep discount to its recent trading range narrows.
Read our earnings preview for Vertiv Holdings Co: https://www.earningswhispers.com/article/VRT/20890
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 4 hours | |
| 4 hours | |
| 5 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| 7 hours | |
| 8 hours | |
| 8 hours |
