Equinix Tops AFFO Estimates And Raises Guidance A Third Time As Record Bookings And Pricing Power Offset A One-Time Fee Boost And Rising Leverage
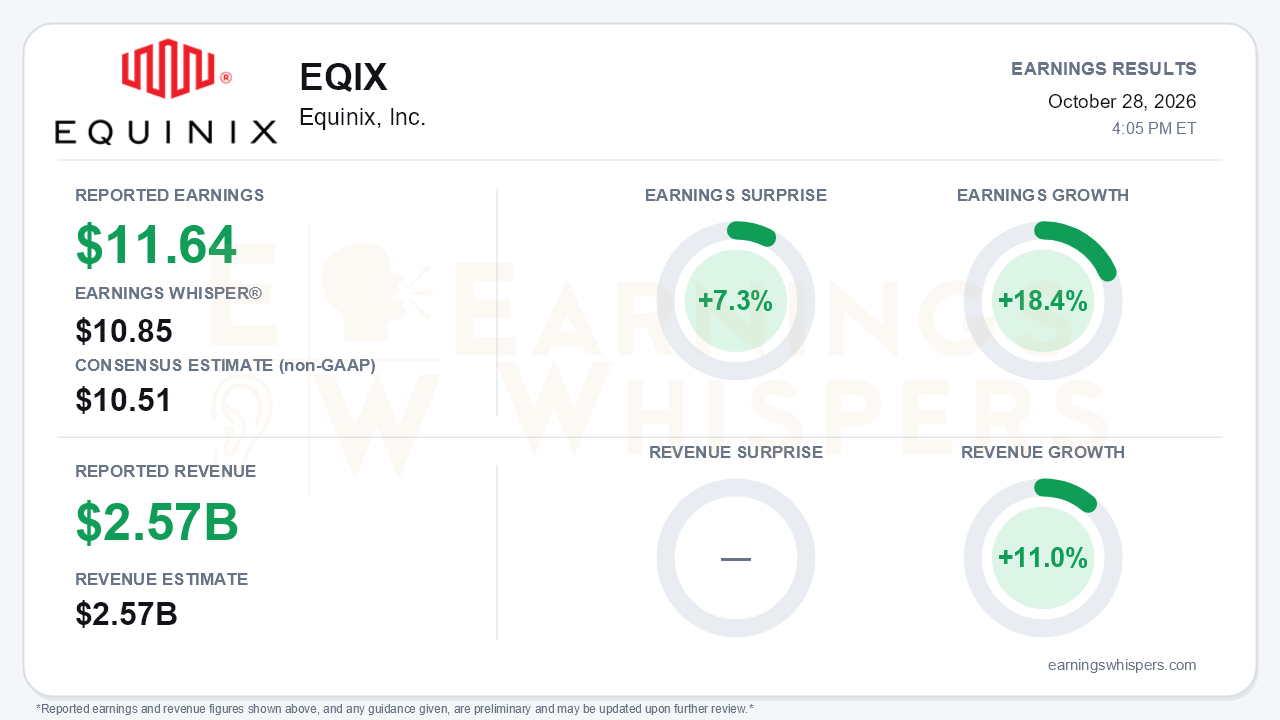
Equinix delivered a clear beat on its primary REIT earnings measure. AFFO per share was $11.64, ahead of the $10.51 consensus by 7.3% and above the $10.85 Earnings Whisper number, while growing 18.4% year over year. Revenue of $2.571 billion matched the $2.57 billion consensus and rose 11.0%. The headline beat is real, but the more important development sits underneath it: bookings, pricing and capacity are all moving in the right direction at the same time. Management raised full-year guidance for the third consecutive quarter. The tension is that the growth engine now runs on more debt, more capital spending and, this quarter, a non-recurring boost.
The quality of the beat deserves scrutiny. Part of the AFFO upside came from a non-recurring fee tied to the atNorth joint venture, which shows up in $54 million of other income. Excluding that fee and on a normalized, constant-currency basis, AFFO per share grew 12%, not 18%. That is still solid, but it is a different growth rate from the headline. GAAP diluted EPS of $4.93 (+29%) carries the same lift. Total revenue fell sequentially from $2.625 billion because non-recurring revenue dropped from $248 million to $129 million. Recurring revenue, the better gauge of the franchise, rose to $2.442 billion from $2.377 billion. Adjusted EBITDA margin of 51.4% expanded 180 basis points year over year, though it was below Q2's unusually strong 53%. Operating income grew 27%.
The call preserved, and arguably strengthened, the growth story:
- **Bookings:** Annualized gross bookings hit a record $533 million, up 35%. That follows $424 million (+23%) in Q2 and $378 million (+9%) in Q1, a clear acceleration. Total sales activity grew 38%, the third straight quarter above 30%.
- **Pricing:** Management disclosed for the first time that new-deal pricing rose 12%. It also framed renewal mark-to-market repricing as a lever.
- **Recurring revenue and churn:** MRR grew 11%, its fourth double-digit quarter. Churn improved to 1.7%.
- **Mature assets:** Stabilized-asset revenue grew 7%, well above the 3-5% norm the CFO described at the start of the year.
- **Interconnection:** Revenue growth improved to 10%, with Fabric up 24%.
The soft spot was net interconnection additions, which fell to 6,900 from a record 9,700 in Q2.
Guidance carried most of the forward signal. Full-year revenue growth is now about 12%, up from a 9-10% range at the start of the year. AFFO-per-share growth moved to 11-12% from 8-10%, and MRR growth to 10-11%. Capacity is also running ahead of plan:
- Retail cabinet deliveries for 2026 are tracking roughly 40% above the original plan.
- A record 13,000-plus cabinets are slated for Q4, more than 20% of them pre-sold.
- 15% of 2027 capacity is already spoken for.
- 60% of the Q4 bookings target was closed by the call, versus 45% at the same point last quarter.
Beyond the core business, liquid-cooling bookings rose more than tenfold. The Inference Exchange with NVIDIA and Fabric One with AWS and Google give Equinix a clearer AI inference narrative.
Bears have legitimate ammunition. Net leverage climbed to 4.1x from 3.6x in Q2, and total debt principal rose to $25.2 billion from $21.4 billion at year-end. Quarterly interest expense increased to $163 million from $128 million a year ago. Free cash flow stayed negative through nine months as capex heads toward $5-6 billion for the year. Management also flagged power constraints, legislative and community pushback, a delayed Dubai project and higher rates. It noted that mark-to-market repricing could deliberately lift churn. Q4 EBITDA margin is guided down seasonally to 49-50%. The 2027-29 outlook was reaffirmed rather than raised, and the full-year churn guide stayed at 2-2.5% despite better run-rates.
Investor sentiment became meaningfully more positive heading into the report, rising from 0.16 to 0.40. The stock did not reflect that improvement. Shares entered earnings at $999.38, down 5.9% since the open after the July report. They sat just below the 200-day moving average of $1,006.34 and roughly 10% under the August 17 high of $1,109.22, though 7.3% off the October 22 low of $931.20. The trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP remain negative. That mix fits a stock whose fundamentals improved faster than its share price.
The bottom line is that Equinix's quarter was better than the in-line revenue suggests and somewhat less pristine than the 18.4% AFFO growth implies. Accelerating bookings, explicit pricing gains, capacity running ahead of plan and a third straight guidance raise point to a business gaining momentum. The atNorth fee, rising leverage and an unchanged long-term outlook keep the debate centered on whether that growth can be funded efficiently. With shares hovering near their 200-day average, the fundamental story has moved ahead of the market's recent treatment of the stock.
Read our earnings preview for Equinix, Inc.: https://www.earningswhispers.com/article/EQIX/20930
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Oct-15 | |
| Oct-14 | |
| Oct-09 | |
| Oct-08 | |
| Sep-28 | |
| Sep-22 |
