Carvana Misses On EPS As Record 39% Unit Growth Comes At The Cost Of Thinner Unit Margins
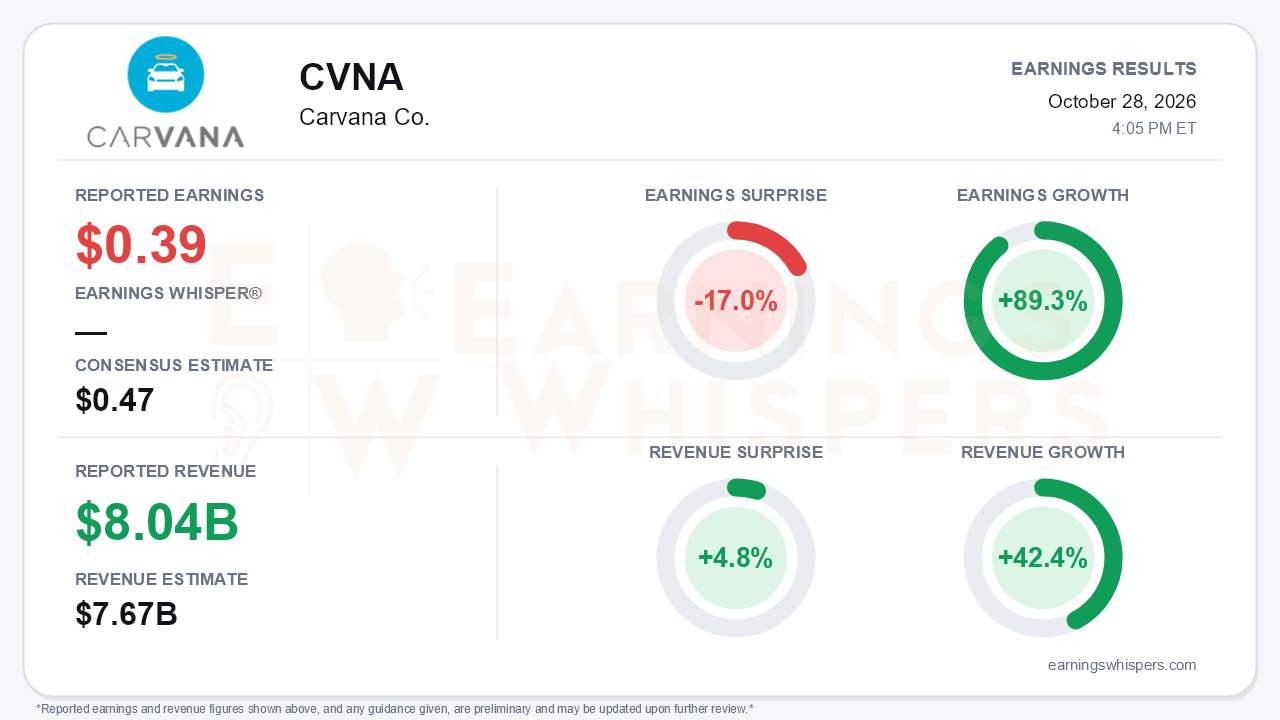
Carvana delivered the biggest quarter in its history and still came up short on the bottom line. The online used-car retailer reported third-quarter earnings of $0.39 per share, missing the $0.47 consensus by 17.0%, even as revenue of $8.04 billion beat the $7.67 billion estimate by 4.8%. Earnings grew 89.3% year over year and revenue rose 42.4%, driven by a record 217,385 retail units, up 39% while the broader used-car industry declined. That is the central tension of the quarter. Carvana is taking share at a pace few retailers can match, but it is paying for that growth with lower profit per car, and the EPS miss reflects that trade-off.
The quality of the quarter deserves a closer look. GAAP operating income reached a record $714 million, up from $552 million a year earlier, with an 8.9% operating margin. Net income rose to $483 million from $263 million, and net income margin expanded to 6.0% from 4.7%. Much of that year-over-year net income gain came below the operating line, however. Other expense fell to $11 million from $154 million, and interest expense declined to $98 million from $125 million. Those gains were partly offset by a $53 million loss on debt extinguishment and a $69 million tax provision, compared with a small tax benefit a year ago. Sequentially, net income slipped from $513 million in the second quarter. Adjusted EBITDA hit a record $800 million, but the adjusted EBITDA margin narrowed to 10.0%, from 10.4% in each of the prior two quarters and 11.3% a year ago. Revenue is compounding faster than profit.
The call explained where the margin went. Management quantified a roughly $200-per-unit hit from rising benchmark rates and fuel costs. Operations expense rose $109 per unit on fuel and logistics, interrupting what had been a steady decline. Advertising rose $45 per unit, with a sharp sequential jump. Other GPU fell $299 year over year, worsening from declines of $192 in Q2 and $88 in Q1, and wholesale GPU dropped $196. SG&A per unit was roughly flat after falling $157 and $170 in the prior two quarters, so operating leverage has stalled for now. There was a genuine bright spot: retail GPU turned positive, up $85 year over year, after four straight quarters of declines. Reconditioning production also topped 200,000 units and outpaced sales, which eases the capacity bottleneck that constrained earlier quarters. Available inventory, however, is still growing more slowly than sales.
The forward-looking story improved. Management now expects full-year adjusted EBITDA at the higher end of its $2.7 billion to $3.0 billion range, narrowed from the full range given in Q2. It also expects a sequential increase in retail units in the fourth quarter, conditioned on a stable environment. The balance sheet continues to de-lever:
- Net debt fell to 0.8 times trailing adjusted EBITDA, from 1.3 times at the end of 2025.
- Refinancing $1.7 billion of senior secured notes should save about $45 million in annual interest.
The tone was notably more expansive. Management framed agentic AI commerce as a structural tailwind, cited Stellantis new-car dealerships as proof of the platform's value, and called FTC pricing-disclosure rules a directional positive. It also plans to shift 2027 reporting emphasis toward GAAP operating income and net income, a sign of confidence in reported profitability. Risks remain concrete: AI could increase loan prepayments and refinancing competition, the ADESA build-outs carry execution risk, and fuel and rate pressures are outside management's control.
The market setup is more complicated than the record figures imply. Investor sentiment swung meaningfully from modestly positive (0.18) to negative (-0.25) heading into the report. Shares were essentially flat since the open after the prior report, up 0.5% to $59.23. That modest change hides a round trip: the stock peaked at $76.80 in late August and slid to an inter-earnings low of $55.92 the day before the snapshot. The shares sit 15% below the 200-day moving average and 22.9% below the quarter's high. Price and AVWAP trend readings remain negative, though momentum has turned positive.
The bottom line is that Carvana's growth engine is accelerating while its unit economics are being squeezed. The EPS miss and the 130-basis-point year-over-year decline in adjusted EBITDA margin give bears legitimate ammunition. Still, record volume, recovering retail GPU, expanding recon capacity, a stronger balance sheet, and high-end guidance preserve a credible growth story. With shares near the bottom of their recent range and sentiment soured, the key question for the next quarter is whether fuel, rate and SG&A pressures ease enough for margins to catch up with volume.
Read our earnings preview for Carvana Co.: https://www.earningswhispers.com/article/CVNA/20922
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-09 |
